
Summary of the IMF forecast update
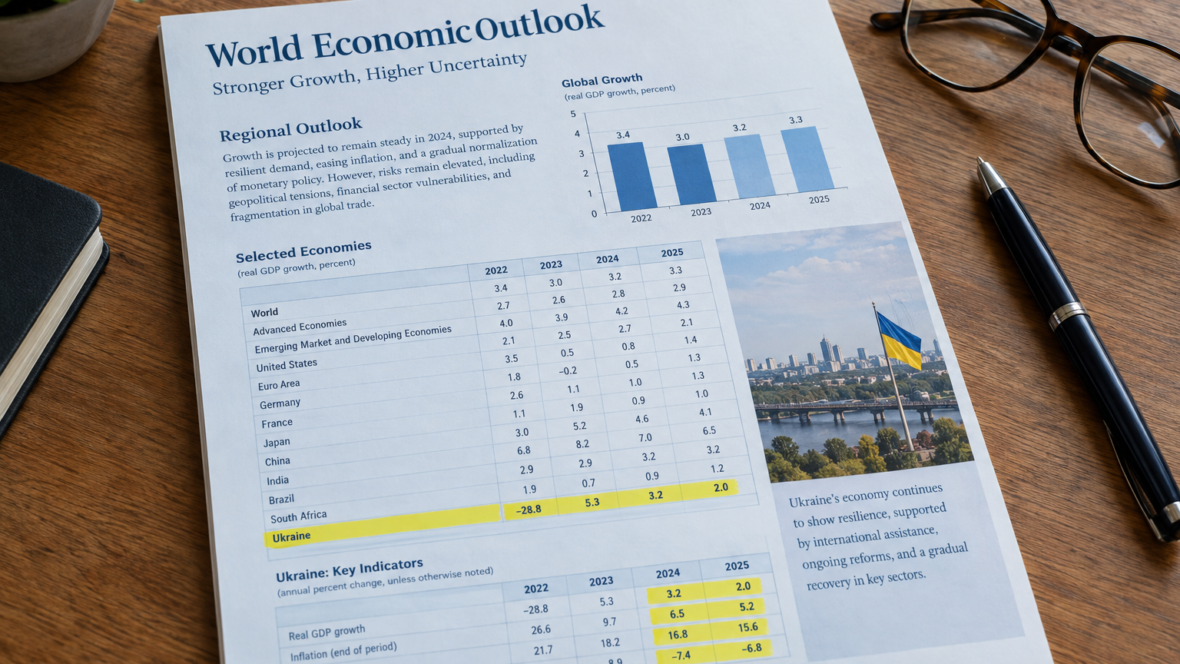
The International Monetary Fund (IMF) in the World Economic Outlook (WEO) published an updated assessment for Ukraine on 13 October. In the IMF report the forecast for economic growth was left at 3,5% in 2027 after slowing to 1,0% in 2026.
The WEO publication was covered by unn. The report also provides expected annual average inflation of 8,9% in 2026 and 8,7% in 2027, as well as current account and unemployment figures.
Forecasts — then and now
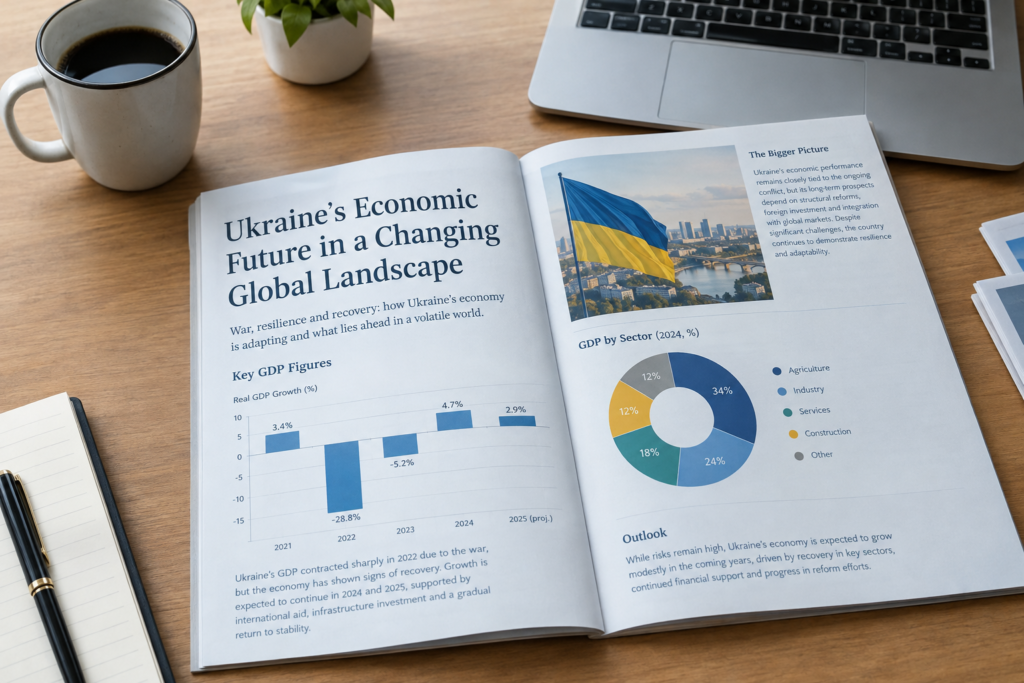
The simplest comparison is between the WEO’s April 2026 forecast and the October update. In April the IMF estimated growth of gross domestic product (GDP) in 2026 at 2,0%. In October that estimate was revised down to 1,0%.
For 2027 the IMF’s forecast remained unchanged at 3,5%. A tabular comparison of the key estimates is given below.
| Indicator | was (WEO April 2026) | is (WEO October 2026) |
|---|---|---|
| GDP growth 2026 | 2,0% | 1,0% |
| GDP growth 2027 | 3,5% | 3,5% |
In June the IMF clarified that growth in 2026 could be 1,0−1,6% due to the consequences of the war. Separately, other international and private institutions also revised their forecasts for Ukraine, including the World Bank and Dragon Capital.
Inflation, the current account and the labour market in the IMF’s estimates
The IMF expects annual average inflation of 8,9% in 2026 and 8,7% in 2027. These figures are presented as annual averages in the WEO report.
According to the forecast, the current account balance in 2026 will be −11,0% of GDP, improving to −4,7% of GDP in 2027. The unemployment rate is expected to be 10,2% in 2026 and 11,3% in 2027.
Risks to the forecast and the impact of attacks on the energy sector
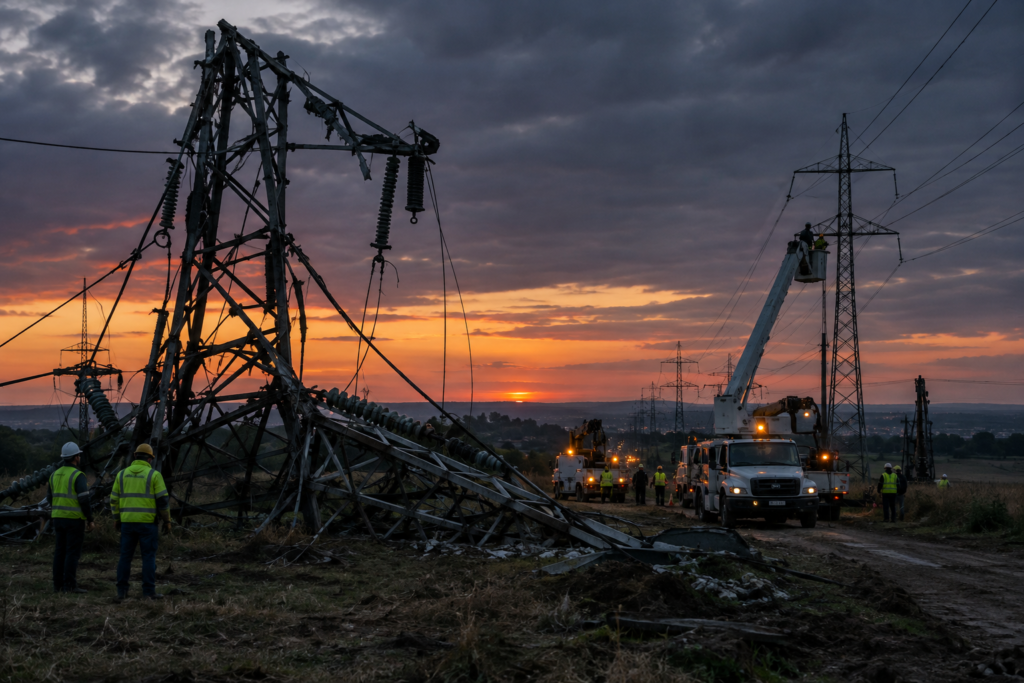
The IMF report notes that large‑scale attacks on energy infrastructure could inflict greater damage than previously expected. Russia has resumed strikes on energy infrastructure well before the onset of cold weather, which could cause power supply disruptions in some regions.
Beyond direct damage, the Fund highlights secondary escalation effects. These include slower income growth due to reduced spending by affected businesses, deteriorating consumer sentiment in major cities and more restrained private investment because of a lack of large‑scale insurance against war risks.