
Starfin recommends that, before signing a loan agreement, you compare the amount, term, costs and payments in the documents prepared specifically for you. As a suggested question it offers: “The loan passport lists one fee, while the contract lists another. Which amount is included in the schedule and why?”.
Documents for the same offer
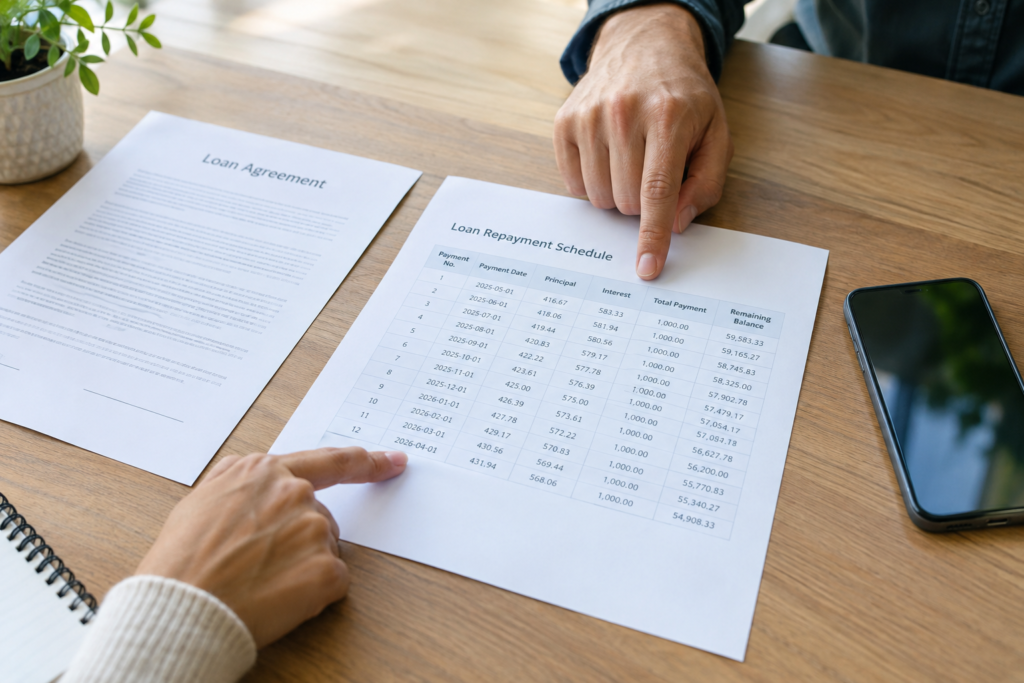
Open the loan passport, the completed draft contract and your personal repayment schedule and compare the details: the lender, product name, your data and the document creation date. A template contract with empty fields is only for preliminary review and does not confirm the amount or the payments.
In the loan passport you should check the date the information was provided and how long it remains current: these details are required by Article 9 of the Law “On Consumer Lending”. If, after reviewing the offer, you change the amount or the payment frequency, ask for a new calculation for your selection. Starfin also lists which documents are required before taking out a loan.
Loan amount and total costs
Total expenses and total cost are different measures: total cost includes the loan amount. To check, add up all the payments in the schedule and determine whether they cover all accounted costs; do not add a fee that is already included in a payment a second time.
The article gives a hypothetical example: if you chose 10 000 UAH, but the calculation was made for 12 000 UAH, you must first agree the amount before comparing the total costs. This is an illustration of possible discrepancies, not a calculation for a specific offer.
First and final payments and explaining discrepancies
The same payment frequency does not mean the amounts are the same. Official terms may include repayment of the principal at the end of the term, payment of interest according to the schedule, and fees in the first calculation period; in your schedule find the date of the first payment, what it comprises, and the final payment that repays the debt.
If you find discrepancies, save both documents and ask for a written explanation or corrected documents. After they have been updated, check the total costs and the schedule: changing one parameter can affect several lines; an explanation of how to read the personal repayment schedule will help reconcile dates and amounts.