
The press service of the State Tax Service of Ukraine (STS) explained when money received under a pawnshop pledge should be regarded as taxable income.
When money received at a pawnshop is not income
Money obtained by pledging one’s own item is a loan, not income. If the borrower repays the loan within the contractually agreed term and retrieves the item, the amount received is not considered income and does not require payment of personal income tax (PIT) and the military levy.
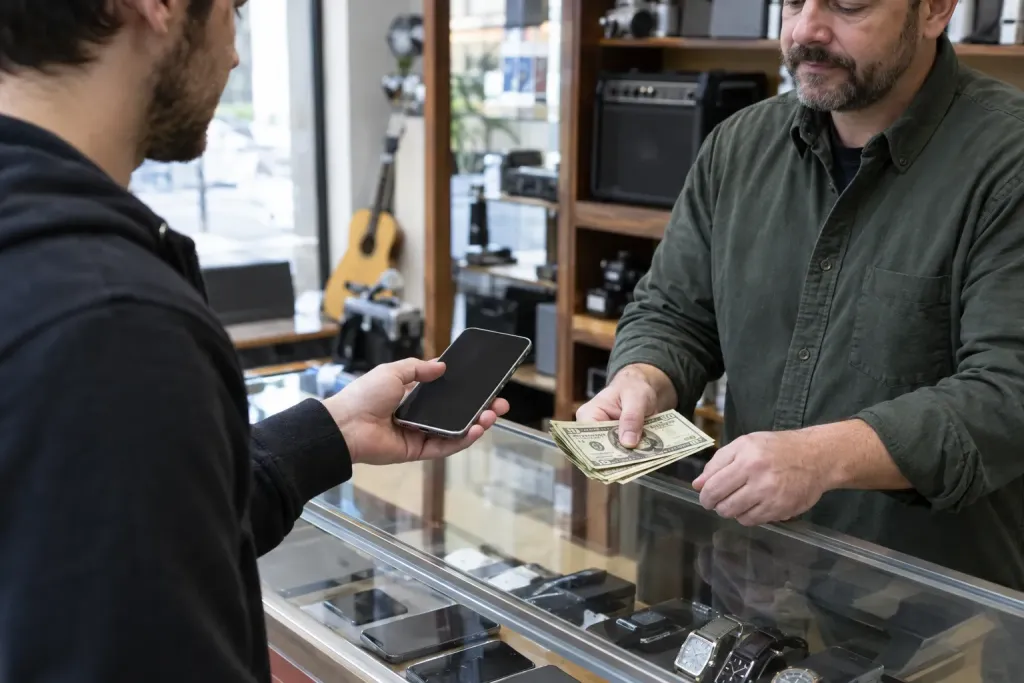
Example in the source: a phone was left as collateral and 8,000 UAH was received; a month later the money was repaid and the device reclaimed - this operation does not create tax liabilities. A tax declaration (an individual’s tax return) therefore does not need to be filed solely because of receiving these funds.
When the pledge is sold - the amount is included in taxable income
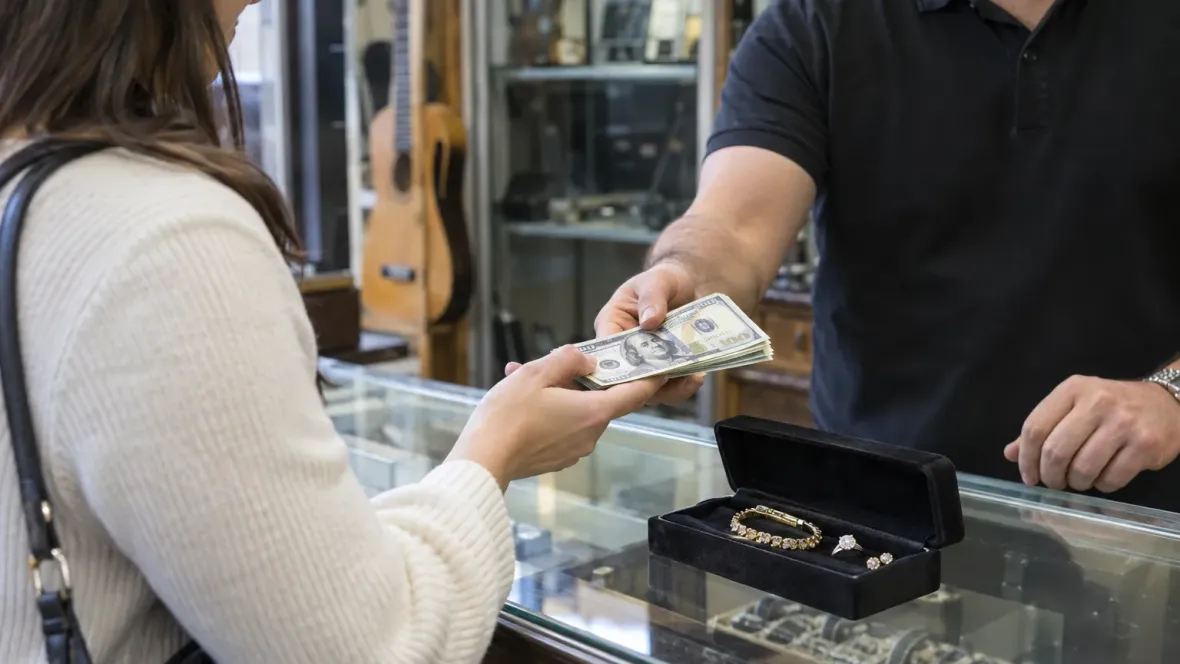
If the borrower does not repay the debt on time and the pawnshop sells the pledged item to cover the arrears, the unpaid portion of the loan is included in the person’s taxable income. Example in the source: jewellery was used as collateral for a 10,000 UAH loan and the debt was not repaid - the unpaid 10,000 UAH is considered income.
If the pawnshop sells the item for more than the outstanding debt, the difference must be returned to the borrower. For example: the debt including interest amounted to 11,000 UAH, the item was sold for 15,000 UAH - the 4,000 UAH difference is returned to the owner, but this amount is also taken into account when determining taxable income, so the actual payment after tax withholdings may be smaller.
Who withholds the taxes and whether a declaration must be filed
The pawnshop acts as the tax agent - it withholds 18% personal income tax (PIT) and 5% military levy from the taxable income. A tax agent is the payer who, by law, is obliged to withhold and pay taxes on behalf of the person who received the income.
If the pawnshop has withheld all due taxes, there is no need to file an annual declaration. A tax declaration is the document in which an individual or a tax agent reports assessed and paid taxes.