
According to the press service of the Ministry of Defence, service members under certain conditions may be exempt from paying the military levy of 1,5% on their monetary remuneration. The right to the exemption applies during direct participation in measures to ensure national security and defence and for the period during which the corresponding tasks are carried out.
Grounds for exemption from the military levy
Under the Tax Code of Ukraine, income in the form of monetary remuneration of service members is exempt from the military levy for the period of their direct participation in measures to ensure national security and defence, and in repelling and deterring the armed aggression of the Russian Federation. The right applies specifically for the period during which participation in the relevant measures continues.
The application of the concession is determined by law, and the final calculation and the right to exemption depend on the actual circumstances of service. To confirm the exemption, corresponding documents and orders are required as obligatory proof.
Which taxes and contributions are charged on monetary remuneration
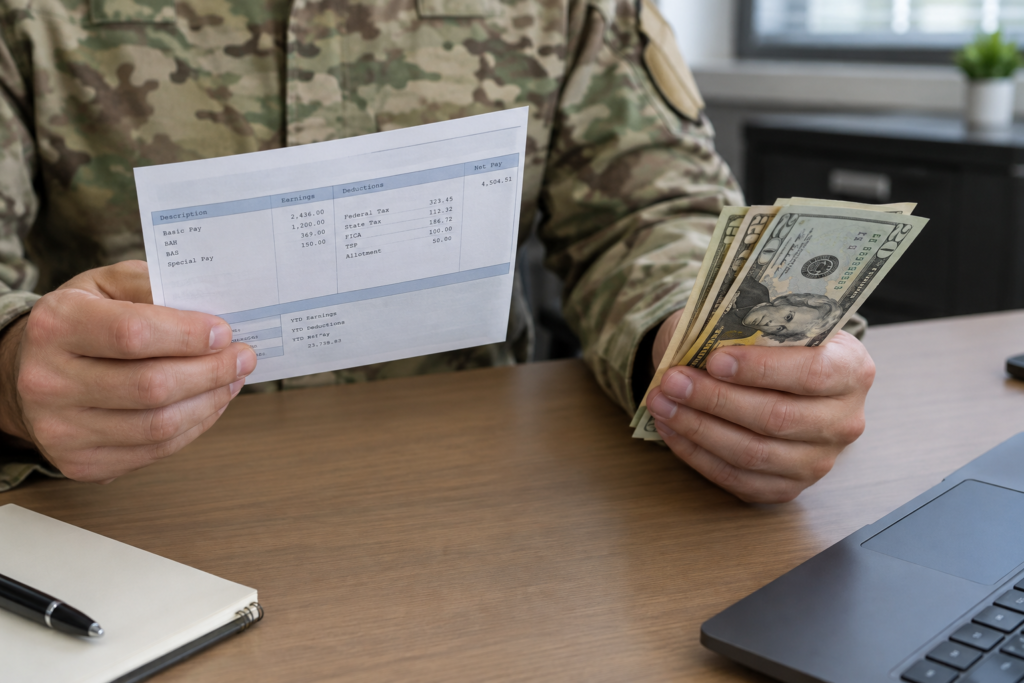
The military levy of 1,5% is the only tax directly withheld from a servicemember’s payments in the absence of grounds for applying the exemption. If the grounds for the exemption exist, the withholding of this levy is not carried out for the relevant period.
Personal income tax (PIT) at a rate of 18% is also charged on monetary remuneration. For service members, amounts of PIT withheld are directed exclusively to the payment of equivalent and full compensation for losses of their income. The single social contribution (SSC) for compulsory state social insurance at a rate of 22% is paid separately by military units and is not withheld from the sum of monetary remuneration due to the servicemember for payment.