
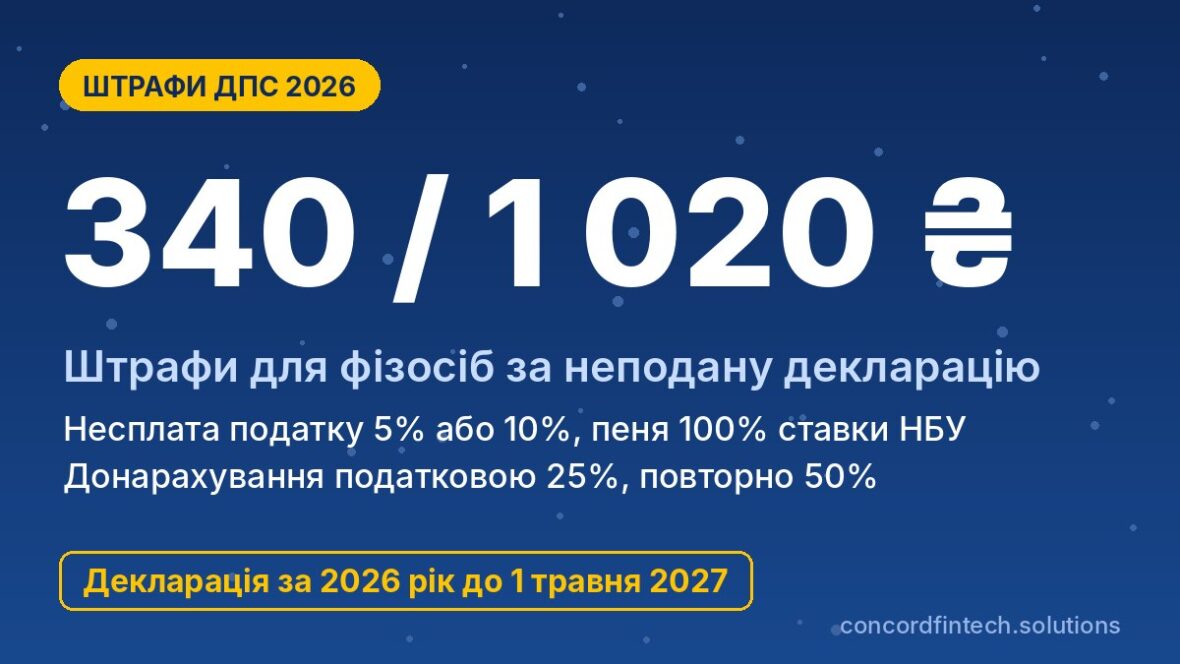
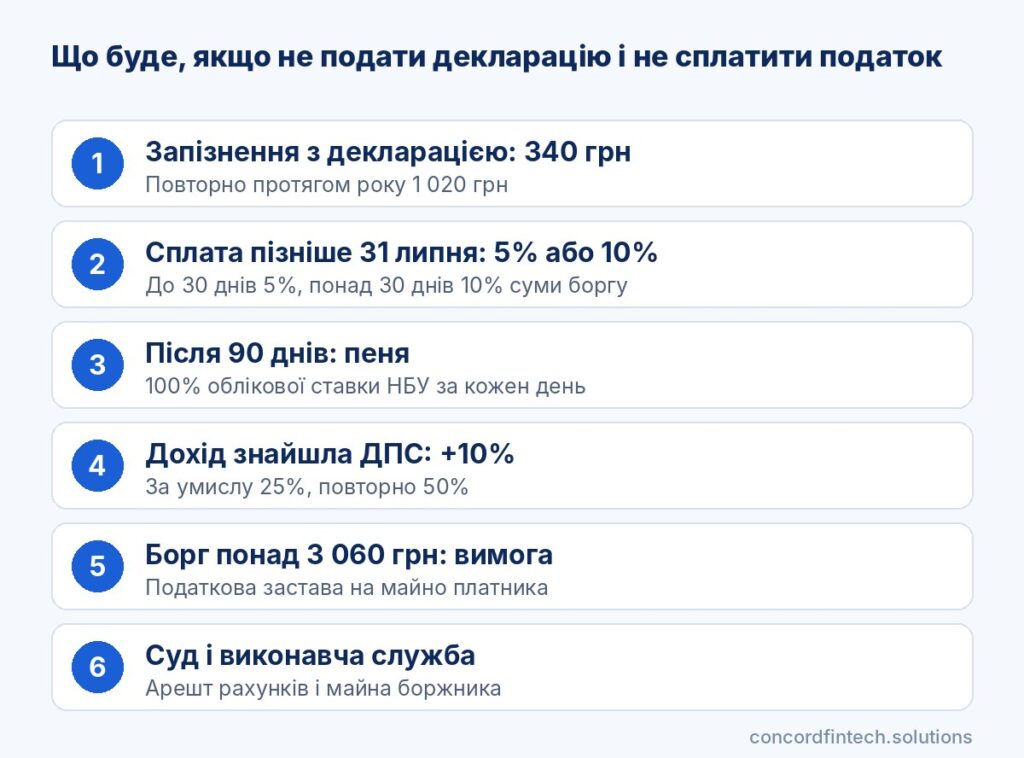
An individual who is not an entrepreneur in 2026 faces three main sanctions from the State Tax Service (DPS): a fine of 340 UAH for a missing or late declaration (1 020 UAH for a repeat offence within a year), a fine of 5% or 10% for late payment of tax, and a penalty calculated at 100% of the National Bank of Ukraine’s (NBU) policy rate. If the tax authority itself discovers undeclared income, it adds a 10% penalty to the reassessed tax, and 25% for intentional understatement (50% for a repeated intentional understatement).
These rules equally apply to income from rent, earnings from abroad, sale of property and inheritance from non-relatives, as well as property, land and transport taxes. Wartime reliefs have applied selectively since 1 August 2023, so below we provide a table of sanctions, calculation examples and the appeal procedure.
Fines and penalties for individuals in 2026: summary table
Main sanctions in one table
The table covers citizens who report and pay taxes themselves, without the status of individual entrepreneur (FOP). The rules are given according to the Tax Code of Ukraine (ПКУ) and the Code of Administrative Offences (КУпАП).
| Violation | Fine | Provision | Note |
|---|---|---|---|
| Failure to file or late filing of a declaration (rent, foreign income, sale of property, inheritance) | 340 UAH | p. 120.1 ПКУ | For each declaration separately |
| Repeat offence within a year | 1 020 UAH | p. 120.1 ПКУ | If a fine was already applied for the first offence |
| Failure to file a declaration (administrative liability) | Warning or 51-136 UAH | art. 164-1 КУпАП | Repeat 85-136 UAH |
| Payment of declared tax late up to 30 days | 5% of the debt | p. 126.1 ПКУ | Payment deadline for 2026 is 31.07.2027 |
| Delay over 30 days | 10% of the debt | p. 126.1 ПКУ | Plus penalty after 90 days |
| Non-payment of property, land or transport tax after a tax notice-decision (PPR) | 5% or 10% | p. 126.1 ПКУ | 60 days for payment from the day the PPR is served |
| Penalty | 100% of the National Bank of Ukraine’s (NBU) policy rate per annum | art. 129 ПКУ | Accrued for each day |
| Understatement of tax discovered by the DPS | 10%, intentional 25%, repeated intentional 50% | p. 123.1 ПКУ | Repeated within 1 095 days |
| Self-correction of an error | 3% or 5% | p. 50.1 ПКУ | No fines for periods of martial law |
| Evasion of payment in large amounts | Criminal liability | art. 212 ККУ | From 4 992 000 UAH in 2026 |
How a tax fine differs from an administrative fine
Tax fines from the DPS are issued by a tax notice-decision (PPR) and are stated directly in hryvnias or as percentages. An administrative fine under the Code of Administrative Offences (КУпАП) is imposed via a protocol, the case is heard by a court, and amounts are tied to the non-taxable minimum of 17 UAH.
Fines for failure to file and late filing of a declaration
First offence: 340 UAH
The declaration of assets and income for 2026 must be submitted by 1 May 2027, and because that is a Saturday it is safer to file by 30 April. Anyone late by even one day or who does not submit the report at all receives a 340 UAH fine under p. 120.1 ПКУ regardless of the tax amount.
Those most commonly fined are people who rent out housing to individuals, received income from abroad, sold a second apartment within a year or inherited property from a non-relative. In all these cases the income does not pass through a tax agent, so a declaration is mandatory.
Repeat within a year: 1 020 UAH
If within a year after the first fine a person again fails to submit a declaration, the sanction rises threefold to 1 020 UAH. For example, an apartment owner who did not declare rent for 2025 and for 2026 may receive 340 UAH for the first report and 1 020 UAH for the second.
Administrative liability under the Code of Administrative Offences
Article 164-1 of the Code of Administrative Offences (КУпАП) provides for a warning or a fine from 3 to 8 non-taxable minimums, that is 51 to 136 UAH. A repeated offence within a year costs 85-136 UAH, and a warning is no longer applied.
Articles 163-2 and 163-4 КУпАП relate to company officials and entrepreneurs, so they do not apply to an ordinary citizen. For an individual without the status of individual entrepreneur (FOP) the administrative sanction is limited to article 164-1.
Fines for late payment of tax
Delay up to 30 days: 5%
Tax declared for 2026 must be paid by 31 July 2027. If the money is received late within 30 calendar days inclusive, p. 126.1 ПКУ provides a fine of 5% of the paid amount of the debt.
For example, rental income of 120 000 UAH gives 21 600 UAH personal income tax (PIT) and 6 000 UAH military levy, together 27 600 UAH. If this amount is paid on 15 August 2027, the fine will be 1 380 UAH.
More than 30 days: 10%
A delay of more than 30 calendar days costs 10% of the debt. For the same rental example that is already a 2 760 UAH fine, to which a penalty is added after 90 days.
The rates of 10% and 20% that still appear in older explanations were in force until 2021. Now the sanctions are half as large, but the penalty is charged only after 90 days of overdue declared tax.
How the delay period is calculated
For declared income the count starts the day after the payment deadline. For property, land and transport tax the deadline is different: 60 days from the day the tax notice-decision (PPR) is served, which the tax authority sends by 1 July.
For example, land tax of 1 800 UAH paid 20 days late means a fine of 90 UAH. Transport tax of 25 000 UAH paid 40 days late will cost an extra 2 500 UAH.
Penalty and its calculation
Penalty rate: 100% of the National Bank of Ukraine’s (NBU) policy rate per annum
Under art. 129 ПКУ the penalty is calculated for each calendar day of delay, including the day of settlement, at the NBU policy rate in effect on that day. As of mid-October 2026 the policy rate is 16% per annum, so one day of delay on each 10 000 UAH of debt costs about 4.38 UAH.
From which day the penalty is charged
If a person declared the tax themselves but did not pay it, the penalty appears only after 90 calendar days from the payment deadline. For tax for 2026 with a deadline of 31 July 2027 this means accrual from 30 October 2027.
If the tax was reassessed by the DPS, the penalty runs from the day following the payment deadline stated in the PPR. While an appeal is pending, the amount is considered disputed and no penalty is charged on it.
Example of penalty calculation
An apartment owner declared 27 600 UAH of tax from rent but paid it only on 15 November 2027. The late-payment fine for more than 30 days is 2 760 UAH, and the penalty is calculated for 17 days, from 30 October to 15 November inclusive.
At a 16% rate the daily penalty equals 27 600 × 16% ÷ 365, i.e. about 12.10 UAH. Over 17 days this totals 205.68 UAH, and together with the fine the overpayment amounts to 2 965.68 UAH.
Fines for understating tax and mistakes
Understatement of tax liability: 10%, 25% and 50%
When the tax authority itself discovers undeclared income or understatement, it reassesses the tax and applies a 10% fine under p. 123.1 ПКУ. If the DPS proves intent, the fine is 25%, and a repeated intentional offence within 1 095 days costs 50% of the reassessed amount.
If the DPS finds an undeclared rental income of 120 000 UAH, it will reassess 27 600 UAH of tax and a 2 760 UAH fine (6 900 UAH if intent is proven). A further 340 UAH will be added for the failure to file, i.e. together 30 700 UAH excluding penalty (34 840 UAH if intent is proven).
Self-correction via an amended declaration
An error can be corrected independently before the tax authority detects it. For this, an amended declaration for the same year is filed in the Electronic Cabinet and the shortfall is paid.
Under the general rule of p. 50.1 ПКУ a 3% fine is added to the shortfall, and if the mistake is shown in the next declaration the rate is 5%. For reporting periods of martial law this fine and the penalty are not applied, so a shortfall of 9 200 UAH would cost only the tax itself instead of a 2 300 UAH fine after an audit.
Incorrect application of the personal tax allowance
The tax social allowance may be applied only at one workplace. If a person submitted claims to two employers, they must declare the underpaid personal income tax (PIT) and pay it themselves.
Without a declaration the tax authority will reassess this amount with a 10% fine (25% if intent is proven) and apply 340 UAH for non-filing. The employer as a tax agent can be fined separately.
Criminal liability under art. 212 of the Criminal Code of Ukraine (ККУ)
Intentional evasion of tax payment in large amounts is punishable under article 212 of the Criminal Code of Ukraine (ККУ). The threshold is 3 000 non-taxable minimums, i.e. 4 992 000 UAH of unpaid taxes in 2026.
For ordinary personal incomes this threshold is almost unreachable. A person is released from criminal liability if they paid the taxes, fines and penalties before being charged.
Wartime reliefs for individuals
Which fines and penalties are not applied
Subdivision 10 of Section XX of the Tax Code left a few specific reliefs, but only under certain conditions. A payer may avoid fines if they:
- corrected an error for a reporting period during martial law independently, under the rules of art. 50 ПКУ;
- paid the amount from a PPR following a documentary audit within 30 days of receipt;
- could not fulfil a tax obligation because of martial law and fulfils it within six months after its end;
- have housing or land in occupied territory or in an active combat zone according to the list of the Ministry for Communities Development.
Exemptions for military personnel and residents of occupied territories
The Tax Code does not contain a separate general relief that would exempt servicemen from the obligation to submit a tax declaration. If a serviceman could not file on time because of service, they may cite inability to fulfil the obligation and confirm it with documents.
For owners of property in occupied territories and in zones of active hostilities property tax and land fees are not charged. The exemption applies from the first day of the month when hostilities or occupation began until the last day of the month when they end.
What changed from 1 August 2023
At the start of the full-scale war fines and penalties for most payers were effectively not applied. From 1 August 2023 liability returned to the general procedure, and reliefs are tied to a specific action by the payer, so there is no automatic exemption simply because martial law is in effect.
How the DPS collects tax debt
Tax demand and tax lien
An unpaid agreed amount becomes a tax debt. If the debt exceeds 180 non-taxable minimums, i.e. 3 060 UAH, the DPS sends a tax demand, and for declared but unpaid tax a separate PPR is not required.
From the moment the debt arises, the tax lien right applies to the payer’s property. A tax manager may seize property and register the lien in the state register, after which the property cannot be sold without coordinating with the DPS.
Enforcement through the courts and seizure
The DPS can only write off funds from an individual’s accounts by court decision. The tax authority files a claim to recover the debt, and after a court ruling the enforcement service may seize the debtor’s accounts and property.
Limitation period 1 095 days
Under art. 102 ПКУ the tax authority can determine tax and apply a fine within 1 095 days after the filing deadline. If a declaration was not filed at all, this period does not limit the tax authority and tax can be reassessed for any period.
The limitation period for collecting an agreed debt is also 1 095 days. During quarantine and martial law the running of terms was partially suspended, so the exact limit should be checked for the specific year.
How to appeal a DPS fine
Administrative appeal
A complaint against a PPR is submitted to the DPS of Ukraine, most easily via the Electronic Cabinet. The steps are:
- check the date the PPR was served - all deadlines are counted from it;
- reconcile the amount with the declaration, payment receipts and cabinet data;
- check whether a wartime relief or the 30-day rule after an audit applies;
- submit a written complaint with copies of documents within the set term;
- await the decision - the amount is considered disputed while this is pending;
- if refused, apply to the administrative court.
Judicial appeal
You can go to court immediately or after an administrative complaint. If the complaint has already been considered, a claim is filed within three months from the day the DPS decision was received, and until the court decision the amount is not considered agreed.
Deadlines and documents
The general deadline for a complaint against a PPR under p. 56.3 ПКУ is 10 working days from the day after receipt. For PPRs regarding property, land and transport tax p. 56.12 gives 30 calendar days, but it is safer to meet the 10 working-day limit.
Attach to the complaint a copy of the PPR, the declaration, payment receipts and documents supporting your position, for example a purchase agreement, a service certificate or an extract from a register. The complaint is signed by the payer or a representative under power of attorney.
Frequently asked questions
Are you fined for filing a declaration one day late?
Yes, p. 120.1 ПКУ makes no exceptions for small delays, so even one day overdue is grounds for a 340 UAH fine. To avoid risk, the declaration for 2026 should be filed by 30 April 2027.
Is the penalty charged during martial law?
Yes, since 1 August 2023 the penalty is charged in the usual way. Exceptions concern self-correction of errors for wartime periods, payment of reassessments within 30 days after an audit and proven inability to fulfil the obligation.
How to appeal a tax fine online?
A complaint can be filed through the Electronic Cabinet, signed with a qualified electronic signature (QES) or the Diia.Signature. It is important to meet the 10 working-day deadline, and for property taxes the 30 calendar-day limit from receipt of the PPR.
What happens if you do not pay the fine?
An unpaid fine becomes a tax debt on which a penalty accrues. If the total amount exceeds 3 060 UAH the DPS will send a tax demand and may later recover the debt through the courts with seizure of accounts and property.