
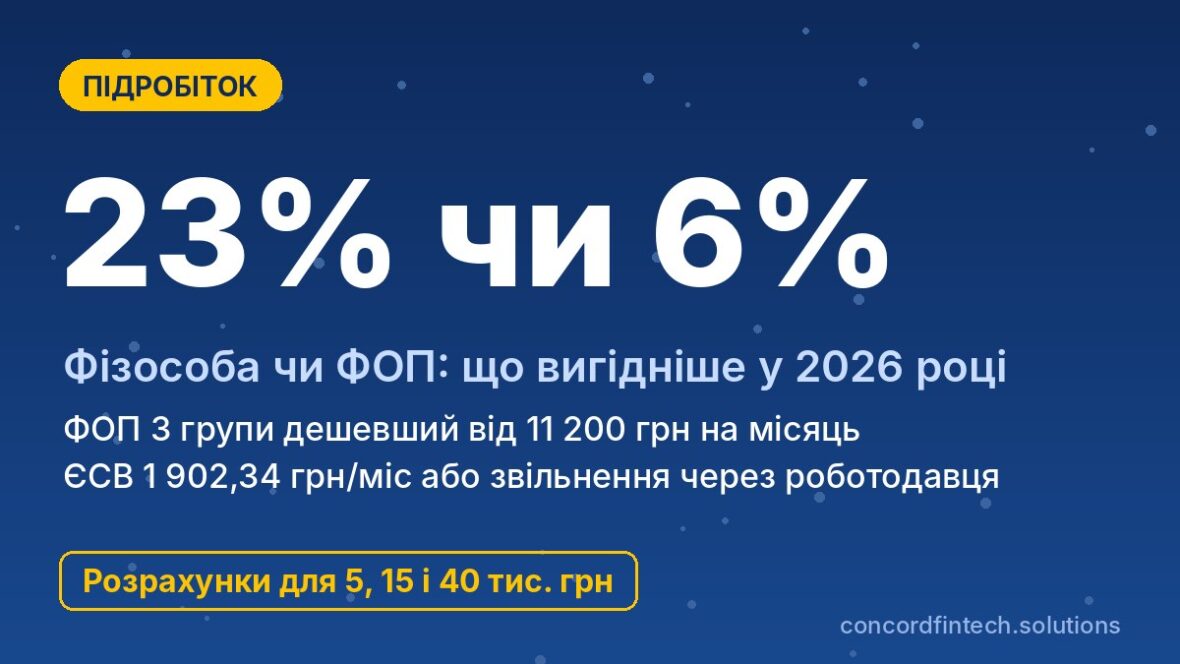
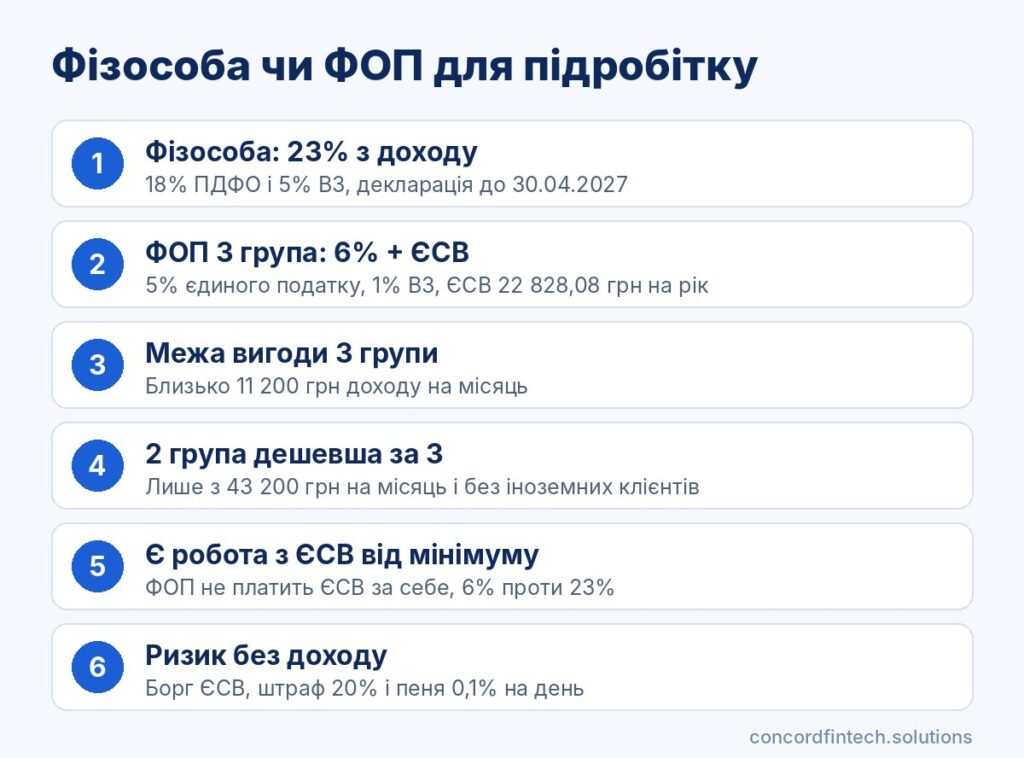
For side gigs up to 11 000 UAH per month it is usually cheaper for an individual to pay 23% tax on income without registering as an individual entrepreneur (FOP), while from roughly 11 200 UAH per month a third‑group individual entrepreneur (FOP) already works out cheaper thanks to the 5% single tax and 1% military levy. The main expense for an FOP is not the tax but the minimum unified social contribution (USC) of 1 902,34 UAH per month, which must be paid even without income.
The picture is different for those who already work under an employment contract. From 1 October 2025 an FOP does not pay the USC for months when an employer has paid at least the minimum contribution for them, so registering as an FOP is advantageous almost from the first hryvnia of side income.
How much an individual without FOP status pays
Income from a company under a civil‑law contract: the payer withholds taxes
Under a civil‑law contract (CPC) with a company, the client is the tax agent: it withholds 18% personal income tax (PIT) and 5% military levy, so you receive 77% of the amount net. Separately the company accrues 22% USC at its own expense, so such cooperation is more costly for them than contracting with an FOP.
Income from private individuals and from abroad: you declare and pay yourself
Money from private clients, foreign customers or freelance platforms you declare yourself and pay 18% PIT and 5% military levy, together 23%. Income for 2026 must be declared by 30 April 2027 and the tax paid by 31 July 2027, otherwise fines of 340 UAH for non‑submission and 5-10% for late payment apply.
“Self‑employed person” status in Ukrainian law
There is no separate simplified regime for the self‑employed, as in some countries. Under the Tax Code a self‑employed person means an individual entrepreneur (FOP) or a person engaged in independent professional activity (a lawyer, notary, auditor), so a freelancer chooses only between being an individual and registering as an FOP.
Insurance (pension) record without USC
No USC is paid on income an individual declares themselves, so insurance (pension) record is not accrued. You can build it up under a voluntary participation agreement, but the contribution is not lower than the minimum, i.e. it costs the same as the entrepreneur’s USC.
FOP taxes for 2nd and 3rd groups in 2026
Fixed single tax and military levy 864,70 UAH for the 2nd group
On the 2nd group the single tax does not depend on income and equals up to 20% of the minimum wage, i.e. up to 1 729,40 UAH per month. The military levy is fixed and equals 10% of the minimum wage, or 864,70 UAH per month.
However the 2nd group works only with the general public and other single‑tax payers. Foreign companies and limited liability companies on the general system are not available to it, so it rarely suits freelancers.
5% single tax and 1% military levy for the 3rd group
On the 3rd group taxes are calculated from received income: 5% single tax and 1% military levy, together 6%. Clients can be any type, declarations are filed quarterly, and the 10 091 049 UAH annual limit for side income is not restrictive.
Minimum USC 1 902,34 UAH per month
USC for oneself equals 22% of the minimum wage of 8 647 UAH, i.e. 1 902,34 UAH per month or 22 828,08 UAH per year. It is paid quarterly, no later than the 19th day of the month after the quarter, at 5 707,02 UAH per quarter.
It is precisely the USC that determines whether it makes sense to be an FOP for a side gig. It must be paid even in months without income, unless there are grounds for exemption.
Comparing the burden on real examples
Break‑even point: from what income an FOP is cheaper
The table shows annual taxes for an individual who declares income themselves and for an FOP without exemption from USC. For the 2nd group the maximum rate was taken.
| Income per month (per year) | Individual, 23% | FOP 2nd group | FOP 3rd group |
|---|---|---|---|
| 5 000 UAH (60 000 UAH) | 13 800 UAH | 53 957,28 UAH | 26 428,08 UAH |
| 15 000 UAH (180 000 UAH) | 41 400 UAH | 53 957,28 UAH | 33 628,08 UAH |
| 30 000 UAH (360 000 UAH) | 82 800 UAH | 53 957,28 UAH | 44 428,08 UAH |
| 40 000 UAH (480 000 UAH) | 110 400 UAH | 53 957,28 UAH | 51 628,08 UAH |
| 100 000 UAH (1,2 mln UAH) | 276 000 UAH | 53 957,28 UAH | 94 828,08 UAH |
The boundary between an individual and the 3rd group is about 134 300 UAH per year, or 11 190 UAH per month, because the 17% difference in rates must cover the USC. An individual loses out to the 2nd group from around 19 550 UAH per month, and the 2nd group becomes cheaper than the 3rd group only from 43 200 UAH per month, if clients allow choosing it.
Freelance with income of 30 000 UAH per month
A designer or developer with a foreign client as an individual will pay 82 800 UAH per year. On the 3rd group that is 44 428,08 UAH including USC, so the saving is over 38 000 UAH.
The 2nd group is unavailable here because of the foreign client. An individual would also have to convert foreign income at the rate of the National Bank of Ukraine (NBU) and declare it themselves.
Renting an apartment for 15 000 UAH per month
An individual landlord pays 23%, i.e. 41 400 UAH per year, while an FOP on the 3rd group pays 33 628,08 UAH. The gain is small and partly eaten by reporting, and single tax rules do not allow renting housing with an area over 100 sq. m.
The Law No.4903‑IX on 5% PIT from rent was adopted by the Rada but not signed as of mid‑October 2026. If it comes into force, individual status would become more advantageous for landlords.
Selling handmade goods through marketplaces
Regular sales of self‑made items can be treated as entrepreneurial activity without registration. Therefore for systematic sales the 2nd or 3rd group FOP is safer, and at income above 11 200 UAH per month it is also cheaper.
FOP for those who already work under an employment contract
Exemption from USC for oneself from 1 October 2025
Law No.4536‑IX rewrote paragraph 6 of Article 4 of the Law on USC. An FOP is exempt from paying the contribution for months when an employer paid USC for them not less than the minimum, i.e. 1 902,34 UAH.
It no longer matters whether this is their main job or a part‑time engagement. No notification to the tax office is required because it receives contribution data automatically.
How the calculation of advantage changes
Without USC a 3rd‑group FOP pays only 6% versus 23% for an individual, so the advantage exists at any income. For a side gig of 5 000 UAH per month that is 3 600 UAH in tax per year instead of 13 800 UAH, and at 15 000 UAH per month 10 800 UAH instead of 41 400 UAH.
For the 2nd group without USC the annual burden remains 31 129,20 UAH, so compared with an individual it pays off from roughly 11 300 UAH per month. It has an advantage over the 3rd group only from 43 200 UAH per month.
When you will have to top up the USC
If the employer accrued less than the minimum, for example for a part‑time day, an FOP on the single tax pays the difference up to 1 902,34 UAH. The same applies to months without salary.
The tax authority clarified that the exemption does not apply if a person works only under a civil‑law contract. You can check monthly records via the OK‑7 information on the Pension Fund portal.
Non‑fiscal benefits and risks of being an FOP
P2P limits and using a business account
Banks, under a Memorandum, set P2P receipt limits for personal cards, including 100 000 UAH per month. An FOP account is intended for payments from clients, and companies are more willing to work with an entrepreneur because they do not pay the extra 22% USC.
Insurance record and sick pay
The minimum USC gives a full month of insurance record. FOPs who pay the contribution are also entitled to temporary disability and maternity benefits, subject to sufficient insurance record.
An individual who declares income themselves does not have such protection. This matters if you lack record: in 2026 a pension at 63 requires 23 years’ insurance record.
Reporting, inspections and USC without income
The main risk is a USC debt that accumulates when there are no orders and the FOP is not closed. For non‑payment a 20% fine and a 0.1% daily penalty are charged, and the law does not provide for instalments.
Below are arguments specifically for irregular income. For a full business the balance is different:
- for FOP: tax 6% instead of 23%, insurance record, business account without P2P limits;
- against FOP: 22 828,08 UAH USC per year regardless of income, if there is no exemption;
- against FOP: declarations, software cash registers (PRRO) for some activities, client limits for the 2nd group;
- against FOP: USC debt remains the person’s responsibility even after closing the FOP.
Registration, choosing a group and closing an FOP
Registration via Diia in one day
You can open an FOP online for free. The extract is usually sent within a day, and the procedure is as follows:
- Log in to the Diia portal with Diia.Signature or a qualified electronic signature (QES) and select the FOP registration service.
- Enter the address, contacts and types of activity according to the Classification of Economic Activities (KVED).
- In the same application choose the simplified system and the single‑tax group.
- Sign the application and wait for the extract and registration with the tax office.
- Open an FOP account at a bank and monitor USC payment deadlines.
Choosing KVED and the single‑tax group
For freelancing with foreign or corporate clients choose the 3rd group, and the 2nd group only for services to the public with income above 43 000 UAH per month. Specify all necessary KVED codes, because income from unlisted activities is taxed at 15%.
Rates for 2027 depend on the minimum wage in the budget. If the proposed 9 546 UAH is approved, the minimum USC will rise roughly to 2 100 UAH per month, and the break‑even threshold will need recalculating.
How to close an FOP without debts
If the side gig ends, close the FOP immediately via Diia, because USC is accrued monthly, then submit the liquidation declaration and pay amounts for the last period. You can close an FOP with a debt, but it transfers to you as an individual, so first reconcile calculations in the electronic cabinet.
Frequently asked questions
From what income is it worthwhile to open an FOP?
Without exemption from USC a 3rd‑group FOP becomes cheaper than individual status from about 11 200 UAH per month, if income is stable for the whole year. If an employer already pays the minimum USC for you, the 3rd group is advantageous practically from any income.
Can you work under an employment contract and as an FOP at the same time?
Yes, the law allows it, and since October 2025 an FOP does not pay USC for months when the employer paid at least the minimum contribution. Just avoid providing services to your employer that are similar to employment, as they may be recognised as a concealed employment contract.
Do you have to pay USC if an FOP has no income?
Yes, an FOP on the single tax pays the minimum USC even without income. Pensioners by age, persons with disabilities, FOPs for whom an employer has paid the minimum contribution, and mobilised persons are exempt for the period of service.
How will the “tax on OLX” affect the choice between FOP and an individual?
Law No.4903‑IX envisages that platforms will withhold taxes from seller‑individuals, and sales up to 2 000 euros per year will remain tax‑free. As of mid‑October 2026 it has not been signed, and for regular sales an FOP will still be cheaper.