
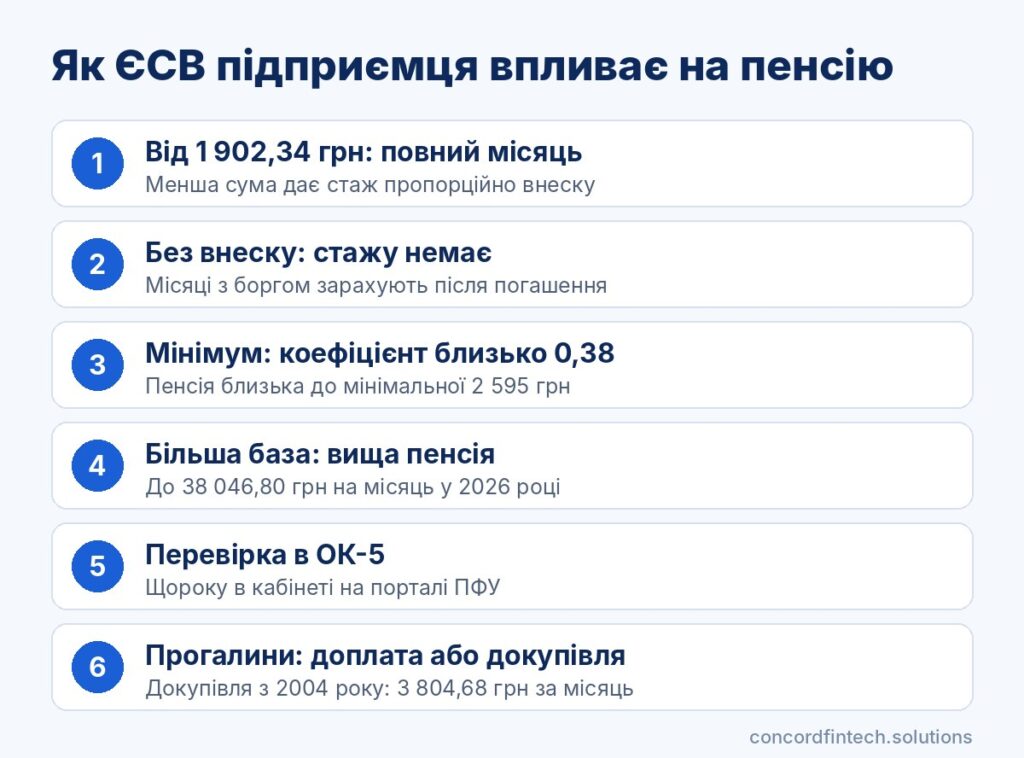
An individual entrepreneur (FOP) receives a full month of pensionable service only when at least the minimum Unified Social Contribution (ESV) for that month has been paid, i.e. 1 902,34 UAH in 2026. If less is paid, the month is counted partially, and months with no payment at all are not included in the service record.
Pensionable service determines the right to a pension, while the pension amount depends on the base on which the contribution was paid. Therefore an FOP who pays the minimum for years typically retires with a pension close to the minimum.
How the Unified Social Contribution (ESV) builds pensionable service for FOP
Pensionable service is defined by article 24 of Law No. 1058-IV. For an entrepreneur, service comprises months for which they personally paid the ESV or for which another payer paid it on their behalf.
Rule for a full month of service
A month is counted in full if the contribution for it is not less than the minimum insured contribution. In 2026 this is 22% of the minimum wage (MZP) of 8 647 UAH, i.e. 1 902,34 UAH per month or 5 707,02 UAH per quarter.
Partial service when underpaid
If the contribution is below the minimum, the month is counted proportionally: the amount paid is divided by the minimum contribution. For example, 951,17 UAH will give only half a month of service. For such months, since 2004 the law allows payment of the difference to reach the minimum, after which the month is counted as full.
Periods without ESV payments
Months without contributions are not included in pensionable service, in particular for FOPs on the general tax system with no net income. If there is a debt for those months, the service will be recorded after the debt is settled; if there was no obligation to pay, the gap can only be closed by voluntary payment or by purchasing service months.
Why the minimum ESV means a minimum pension
Under article 27 of Law No. 1058-IV the pension equals the average salary used to calculate pensions multiplied by the earnings coefficient and the service coefficient. For FOPs, earnings are the base on which ESV was calculated, so with the minimum contribution the earnings equal the minimum wage.
Earnings coefficient and the average salary
The earnings coefficient for each month equals the person’s earnings divided by the average salary in Ukraine on which contributions were paid for that month. According to the Pension Fund of Ukraine (PFU), at the start of 2026 that indicator was 21 876-23 218 UAH, so the minimum wage of 8 647 UAH yields a coefficient of about 0.38. The service coefficient is 1% per year, so 33 years of service gives 0.33.
Example of an FOP pension calculation
For awards in 2026 the average salary indicator is 17 482,87 UAH. If a person has 33 years of service and paid the minimum ESV throughout, the calculation gives approximately 17 482,87 × 0.38 × 0.33 = 2 192 UAH, which is below the minimum pension of 2 595 UAH. Another example: 15 years of employed work at average wages and 18 years as an FOP with minimum contributions give an earnings coefficient of about 0.66 and a pension of roughly 3 818 UAH.
Service requirements by age in 2026
In 2026 an old‑age pension is granted at 60 years with 33 years of service, at 63 years with 23 years, or at 65 years with 15 years. For FOPs this means that each unpaid year can delay retirement from 60 to 63.
Voluntary top‑up of ESV above the minimum
An FOP on the single tax regime can choose the ESV base independently within the range from the minimum to the maximum. Such a top‑up does not give additional months of service, but it increases the earnings coefficient.
How to declare a higher base
An FOP indicates the chosen base in Appendix 1 to the single taxpayer declaration. Groups 1-2 submit it annually as part of the yearly declaration within 60 days after the year ends, while Group 3 submits it with the declaration for the fourth quarter within 40 days. The increased contribution must be paid by the 19th day of the month following the quarter.
Maximum contribution in 2026
The maximum assessment base is 20 times the minimum wage (MZP), i.e. 172 940 UAH per month. Therefore the largest contribution for oneself in 2026 equals 38 046,80 UAH per month, and the pension is capped at a maximum of 25 950 UAH.
Is top‑up profitable: a calculation
The table shows the approximate effect of different monthly contributions assuming the person paid that amount for all 33 years of service. The calculation is simplified: the earnings coefficient is taken against an average salary of about 23 000 UAH, and indexation is not considered.
| Monthly ESV | Service per month | Earnings coefficient | Approximate effect on pension |
|---|---|---|---|
| 1 902,34 UAH (minimum) | 1 month | about 0.38 | about 2 190 UAH, below the minimum pension |
| 3 804,68 UAH (2 MZP) | 1 month | about 0.75 | about 4 330 UAH |
| 9 511,70 UAH (5 MZP) | 1 month | about 1.88 | about 10 850 UAH |
| 38 046,80 UAH (maximum) | 1 month | about 7.5 | capped by the maximum pension 25 950 UAH |
The payback period for the top‑up is slow. If the register contains roughly 25 years of earnings, one year of contributions at a 2 MZP base instead of the minimum costs an additional 22 828 UAH and raises the pension by only 80-90 UAH per month, so the investment returns in about 20 years without accounting for indexation.
Service for FOPs exempted from ESV
Exemption from paying ESV for oneself does not always mean loss of service. It depends on whether a contribution is made by another payer.
An FOP who also works under an employment contract
From 1 October 2025 an entrepreneur does not pay ESV for months in which an employer paid at least the minimum contribution on their behalf. Service in that case is formed thanks to the salary, so the month is counted in full. If the employer accrued less than the minimum, the obligation to pay ESV for oneself remains.
Mobilised persons: recognition of service
Mobilised FOPs do not pay ESV for themselves from the month of conscription through the month of demobilisation inclusive. The period of military service is counted toward pensionable service, and contributions for that period are paid by the military unit from monetary provisions.
FOPs who are pensioners
Entrepreneurs who already receive an old‑age or disability pension are exempt from paying ESV for themselves. They may voluntarily pay the contribution to acquire additional service. Working pensioners who have at least 24 months of service after the pension was granted or after the previous recalculation will have their pension recalculated by the Pension Fund of Ukraine (PFU) from 1 April; with less service, a recalculation is possible not earlier than two years later.
Maternity leave and child care
During the period of receiving child care allowance the ESV for the recipient is paid by the Pension Fund of Ukraine (PFU) as the paying authority, so the FOP is exempt from paying for themselves and does not lose service. During maternity leave a female entrepreneur may also not pay ESV for herself. However, it is advisable to check with the PFU in advance whether these months will be credited to service.
How to check an FOP’s service in the Pension Fund
It is worth checking service every year rather than just before retirement. Data for the year appears in the register after processing Appendix 1, so spring is a convenient time to check.
Personal account on the PFU portal
You can log in to the account on the Pension Fund of Ukraine (PFU) electronic services portal using a qualified electronic signature (QES) or Diia.Signature. The following documents and services are needed for verification:
- form OK‑5 with data on contributions and service from 2000;
- form OK‑7 with data from 2011;
- the taxpayer’s electronic account at the State Tax Service (DPS) to reconcile paid ESV;
- payment receipts for contributions for each quarter.
Forms OK‑5 and OK‑7
In form OK‑5 you can see for each month the contribution amount, the earnings for pension calculation and the number of service days. A partial month shows a reduced number of days, and a month with no contribution is absent.
What to do in case of discrepancies
If a payment exists in the bank but is missing in the register, first reconcile calculations with the State Tax Service (DPS): an error in details or in Appendix 1 is corrected through the tax service. If the register contains incorrect data on service or earnings, submit to the Pension Fund of Ukraine (PFU) an application for correction together with the payment receipts.
How to close gaps in service
The method to close a gap depends on why the month was not counted. The procedure for an FOP who has found unpaid or partial months is as follows:
- Order form OK‑5 and list the months that are missing or counted partially.
- Check in the State Tax Service (DPS) account whether there is a debt for ESV for those months.
- Settle the debt together with fines and penalties, after which the months will be recorded.
- For partial months from 2004 onward submit to the Pension Fund of Ukraine (PFU) an application to top up to the minimum.
- For months when there was no payment obligation, conclude an agreement to purchase service months.
- One to two months after payment, check form OK‑5 again.
Paying ESV debt for past periods
An ESV debt is not written off even after closing an FOP, and instalment payments are not provided. A 20% fine and a penalty of 0.1% for each day of delay are added to the amount.
Top‑up to the minimum contribution
For months since 2004 for which the contribution was lower than the minimum, the PFU issues a notification‑calculation with the top‑up amount. It must be paid within 10 calendar days, after which the month is counted as full. Top‑up is not possible for months with no contributions at all.
Purchasing service months: conditions and cost
Months without contributions from 1 January 2004 can be purchased under an agreement on voluntary participation with the State Tax Service (DPS). The cost of one month equals double the minimum contribution, i.e. 3 804,68 UAH, and a year costs 45 656,16 UAH. This is relevant for those who in 2022-2023 used the temporary right not to pay ESV.
Frequently asked questions
Does an FOP get a full month of service with the minimum ESV?
Yes, a contribution of 1 902,34 UAH per month gives a full month of service in 2026. However, the earnings for the pension will then equal the minimum wage, so the pension will be low.
How many years of service does an FOP need for a pension in 2026?
The requirements for entrepreneurs are the same as for employed workers: 33 years to retire at 60, 23 years at 63 and 15 years at 65.
Can I top up ESV for past years?
An ESV debt can be repaid at any time, and months will be recorded after payment. Partial months since 2004 are closed by top‑up to the minimum through the Pension Fund of Ukraine (PFU), and months without contributions can be purchased at the double rate under an agreement with the State Tax Service (DPS).
Is it worth paying ESV above the minimum?
Top‑up increases the pension, but it pays back in roughly 20 years, so it mainly makes sense for those who expect a long retirement and have no other savings. More important is to avoid gaps in service in the first place.