
If you look only at taxes, a third‑group individual entrepreneur (FOP) remains more advantageous for a developer in 2026 than a Diia.City gig contract: the entrepreneur pays 6% of income and the minimum single social contribution (ЄСВ), while a gig specialist loses 10% of the fee. At an income of 3 500 dollars per month the difference in favour of the FOP is about 52 771,92 UAH per year, and at 6 000 dollars it is already over 106 771,92 UAH.
At the same time, the gig contract relieves the person of accounting, reporting and the risk of reclassification and provides paid leave. Below are calculations for three income levels, the guarantees, booking (reserve) rules and a decision algorithm.
How a third‑group FOP IT contractor is taxed
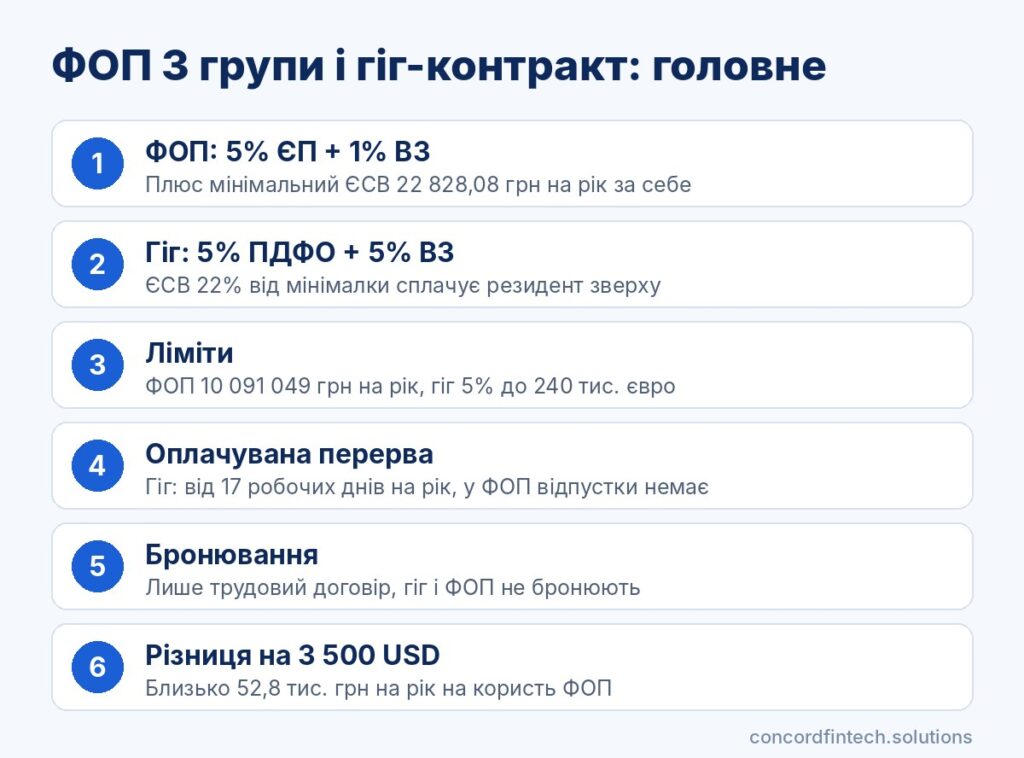
5% single tax
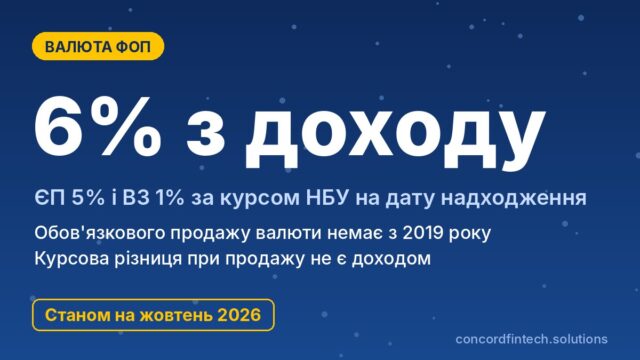
Most developer‑entrepreneurs work on the third group without value‑added tax (VAT) and pay 5% of all received income. Costs for equipment, rent or training are not deductible from the tax base, so the tax is calculated on the amount that arrives in the account, and foreign‑currency income is converted into hryvnia at the rate of the National Bank of Ukraine (NBU) on the date of receipt.
The tax is paid and declared quarterly. The revenue ceiling for the third group in 2026 is 10 091 049 UAH per year.
1% military levy
For the third group the military levy equals 1% of income and is paid on the same deadlines as the single tax. Thus, together with the single tax (ЄП) the entrepreneur gives up 6% of revenue, while employed workers and gig specialists have only the levy of 5%.
Minimum single social contribution (ЄСВ)
The single social contribution (ЄСВ) for oneself is paid regardless of income, and in 2026 the minimum amounts to 1 902,34 UAH per month, or 22 828,08 UAH per year. It must be paid quarterly no later than the 19th day of the month following the quarter, and paying more than the minimum is voluntary, up to a base of 20 minimum wages.
How a Diia.City gig specialist is taxed
Personal income tax (PIT) 5%
Under a gig contract with a Diia.City resident the fee is taxed with the preferential personal income tax (PIT) rate of 5% instead of the usual 18%. The preference applies within EUR 240 000 of income per year from that resident, and amounts above that threshold are withheld at 18%.
The tax is withheld and paid by the resident as the tax agent. The gig specialist does not need to register, keep records or submit a declaration for that income.
Military levy
Initially a 1.5% military levy applied to gig specialists’ fees, but Law No.4015‑IX increased the rate to 5%, as for the resident’s employees. Therefore, together with PIT 10% is withheld from the fee, and as of mid‑October 2026 no other changes have been adopted.
ЄСВ on a minimum base
The resident pays the single social contribution for the gig specialist at a rate of 22% of the minimum wage, i.e. 1 902,34 UAH per month regardless of the size of the fee. This contribution is charged on top of the fee and is not withheld from the person’s remuneration.
Thus, for the specialist the tax burden is 10%, while for the company the total cost of the contract is higher by 22 828,08 UAH per year. If the resident budgets ЄСВ for the person, the net («take‑home») amount will be slightly less than the calculations below.
Comparison of tax burden by examples
Income 2 000 dollars per month
For the calculations we use an indicative rate of 45 UAH per dollar, close to the official NBU rate at the beginning of October 2026. Income of 2 000 dollars gives 90 000 UAH per month, or 1 080 000 UAH per year.
An FOP will pay 64 800 UAH in single tax and military levy and 22 828,08 UAH in ЄСВ, totalling 87 628,08 UAH. A gig specialist will lose 108 000 UAH, so the FOP will have 20 371,92 UAH more in hand.
Income 3 500 dollars per month
At the same rate this is 157 500 UAH per month, or 1 890 000 UAH per year. The FOP will pay 113 400 UAH in income taxes and 22 828,08 UAH in ЄСВ, a total of 136 228,08 UAH.
The gig specialist on the same fee will give up 189 000 UAH. The difference in favour of the FOP rises to 52 771,92 UAH per year, i.e. almost 4.4 thousand UAH per month.
Income 6 000 dollars and nearing the limit
Income of 6 000 dollars equals 270 000 UAH per month, or 3 240 000 UAH per year, and is still far from the third‑group limit. The FOP will pay 217 228,08 UAH, the gig specialist 324 000 UAH, so the entrepreneur’s advantage is 106 771,92 UAH.
The FOP ceiling will be exhausted only at an income of approximately 18 600 dollars per month at this rate. Income above the limit is taxed at 15% and the entrepreneur must switch to the general taxation system, whereas for the gig specialist 5% PIT applies up to EUR 240 000 per year, which at an exchange rate of about 50 UAH per euro exceeds 12 million UAH.
| Income/month | FOP: taxes per year | FOP: net per year | Gig: taxes per year | Gig: net per year | Difference |
|---|---|---|---|---|---|
| 2 000 USD (90 000 UAH) | 87 628,08 UAH | 992 371,92 UAH | 108 000 UAH | 972 000 UAH | +20 371,92 UAH in favour of FOP |
| 3 500 USD (157 500 UAH) | 136 228,08 UAH | 1 753 771,92 UAH | 189 000 UAH | 1 701 000 UAH | +52 771,92 UAH in favour of FOP |
| 6 000 USD (270 000 UAH) | 217 228,08 UAH | 3 022 771,92 UAH | 324 000 UAH | 2 916 000 UAH | +106 771,92 UAH in favour of FOP |
In the table for the gig contract only PIT and the military levy are taken into account, because ЄСВ of 22 828,08 UAH per year is paid by the resident on top of the fee. With a different exchange rate the sums in hryvnia will change, but the ratio of 6% versus 10% remains.
Social guarantees: leave, sick pay, maternity
What the gig contract guarantees
The gig contract is a civil law agreement with elements of employment, so the guarantees are defined by Law No.1667‑IX and by the contract itself, not by the Labour Code (KZpP). The law provides for an annual paid leave of at least 17 working days after six months of work, and terms for its payment, overtime and compensation on termination are set out in the contract.
The gig specialist is insured in the social insurance system and therefore entitled to sick pay and maternity benefits. However, these payments are calculated from the ЄСВ base, that is from the minimum wage, so without additional contract terms they are small.
What an FOP has
An entrepreneur who pays ЄСВ is also entitled to sick pay and maternity benefits from the Pension Fund provided they have insurance record. With the minimum contribution these payments are modest as well.
There is no paid annual leave for an FOP, nor severance pay on contract termination. Anything the company promises additionally to an entrepreneur is only a term of the service agreement and has no statutory protection.
Voluntary insurance and pension record
With the minimum ЄСВ both the FOP and the gig specialist receive a full month of insurance record, but a pension calculated on that base will be close to the minimum. Therefore, developers with high income should consider separate savings, for example via a non‑state pension fund or investments.
Risks of each model
Reclassification of an FOP into employment
The biggest risk for an FOP arises when they effectively work as a staff employee for a single client. The tax authority may regard such relations as employment if there is a fixed schedule, a workplace, subordination to internal rules and payment “per month” rather than by result. The main risks of the two models are:
- FOP: additional charges to the client for PIT, the military levy and ЄСВ at payroll rates and fines if the contract is recognised as employment;
- FOP: exceeding the 10 091 049 UAH limit due to exchange‑rate growth and a forced switch to the general taxation system;
- FOP: bank questions about the origin of foreign currency receipts and account restrictions if documents are incomplete;
- gig specialist: dependence on the resident’s status, because if it is lost the preferential rates cease to apply;
- gig specialist: guarantees only within the contract, so unfavourable termination terms should be negotiated in advance.
Dependence on the Diia.City resident
The preferential 5% PIT applies only while the company meets the requirements for a resident. These include an average monthly remuneration for employees and gig specialists of at least the equivalent of 1 200 euros, at least nine such specialists on average and not less than 90% of revenue from IT activities.
If the company loses the status, contracts will have to be reissued and taxation will become ordinary. In addition, within this model you cannot work directly with foreign clients.
Financial monitoring and foreign currency receipts
An FOP receiving payment from abroad undergoes the bank’s foreign‑currency control and must explain the nature of operations with contracts and acts. Banks also set their own turnover limits on accounts, so a sharp increase in receipts may trigger document requests.
The gig specialist receives the fee in hryvnia from a Ukrainian resident, so for the bank such income looks like wages. This simplifies obtaining a loan or a mortgage.
Booking (reserve) and mobilisation: the difference for an FOP and a gig specialist
Booking through a Diia.City resident
The booking procedure under Cabinet of Ministers of Ukraine (CMU) Resolution No.76 of 27.01.2023 applies only to those employed under labour contracts. A gig contract is not an employment contract, so as of mid‑October 2026 a resident cannot book a gig specialist, even if the company is recognised as critically important.
The idea of allowing booking for gig specialists was discussed, for example in draft law No.9319 (2023), but these changes have not been introduced into the current Procedure. To arrange booking the person must be transferred to an employment contract with the resident, where the same rates of 5% PIT and 5% military levy apply.
Requirement for a salary of 2.5 minimum wages
For most companies a booked employee must receive at least 2.5 minimum wages, which in 2026 equals 21 617,50 UAH per month. Diia.City residents are exempt from this individual criterion because ЄСВ for them is charged from the minimum base.
Instead, the company’s average salary for the last month must not be lower than the regional average. For a company with remuneration from 1 200 euros this is usually not a problem.
FOP status
An entrepreneur cannot book themselves, and a service agreement with a company does not give the right to booking under Resolution No.76. If an FOP is mobilised, during service they do not pay the single tax, the military levy or ЄСВ for themselves and do not report.
What a developer should choose in 2026
Freelancer with several clients
If you work with several clients, including foreign ones, the third‑group FOP is almost irreplaceable. A gig contract is only possible with a Diia.City resident, while an FOP can accept payment from anyone, and the risk of reclassification with several independent clients is minimal.
Developer working for a single company
When all the work is for a single resident company, the choice depends on priorities. The FOP gives more money in hand, while a gig contract or an employment contract provides transparency, paid breaks, no reporting and the possibility of booking under an employment contract. Three questions will help decide:
- Do you have other clients or foreign customers? If yes, remain an FOP.
- Do you need booking? If yes, ask for an employment contract with the resident, because a gig contract does not provide it.
- Are you willing to keep records and reporting and bear the reclassification risk for the sake of a 4% saving? If not, choose the gig contract.
A VAT scenario for FOPs
As of mid‑October 2026 there is no law or registered draft law on mandatory VAT for FOPs. In the memorandum with the International Monetary Fund (IMF) the target is to pass changes by April 2027 with effect from 1 January 2028, and the Ministry of Finance (MinFin) discussed a threshold of about 4 million UAH of revenue.
For some IT services to foreign clients the place of supply is determined by the customer’s location, so VAT may not affect them. For developers with large income from Ukrainian companies the reform could reduce the FOP advantage.
Frequently asked questions
Which is more profitable for a developer: FOP or a gig contract?
By taxes the third‑group FOP is more advantageous: 6% of income plus 22 828,08 UAH ЄСВ per year versus 10% withholding under a gig contract. The gig contract wins on convenience, paid breaks and no risk of reclassification, so for working in a single company the decision depends on your priorities.
Can a gig specialist obtain booking?
As of mid‑October 2026 no, because Resolution No.76 allows booking only for employees under labour contracts. To obtain a deferral through a Diia.City resident you need to sign an employment contract with them instead of a gig contract.
Can you be an FOP and have a gig contract at the same time?
Yes, the law does not prohibit being an entrepreneur while also working under a gig contract, provided these are different agreements and different work. Taxes are calculated separately for each model, and the resident should consider that its expenses on services from single‑tax payers beyond a certain share may be taxed under the distributed profit tax rules.