
According to ARX, in the first quarter of 2026 the average payout for auto-civilka (compulsory motor third-party liability insurance) in Ukraine was 57 455 UAH, which is 52% higher than a year earlier. The average premium for the same period rose by 8.8% — to 3 237 UAH.
Rising payouts and reasons for change
The rise in payouts is explained by several factors: after the reform, wear and tear is no longer deducted from losses, and both spare parts and workshop labour have become more expensive. As a result, the cost of compensating losses is growing faster than premium income.
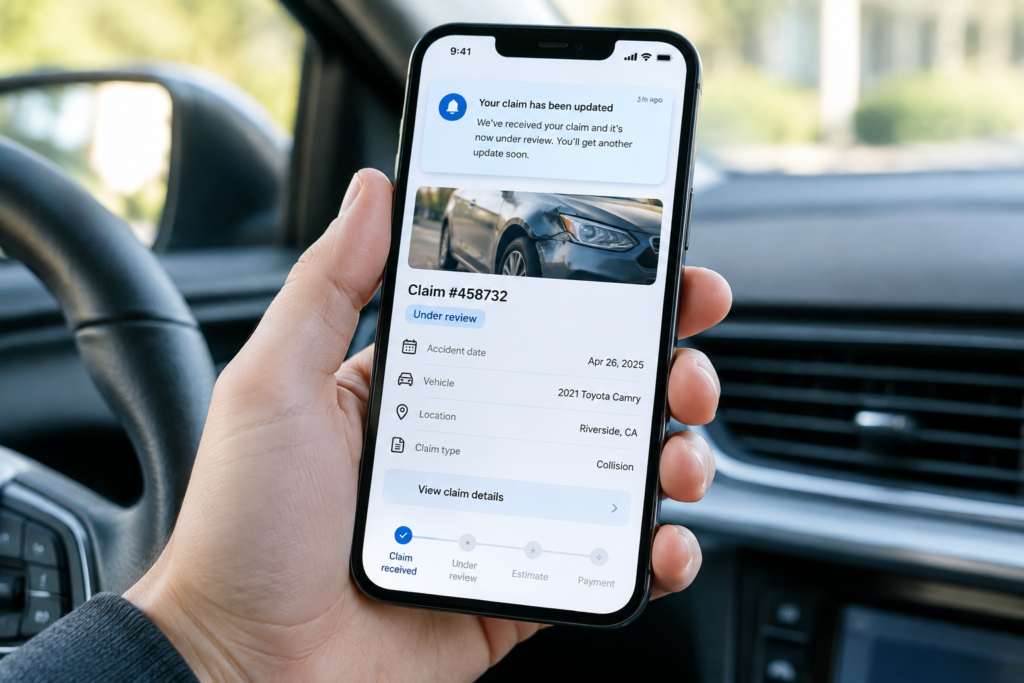
The statement notes that understanding the client portfolio and rapid claims settlement are becoming central for insurers. “For an insurer this means a simple thing: you can only make money on auto-civilka when you know exactly whom you are insuring and can settle losses quickly,” the piece says.
Direct settlement shortens claim settlement times
Direct settlement allows the injured party to contact their own insurer rather than the at-fault party’s insurer. In the first quarter of 2026 cases handled under direct settlement were closed on average in 32 days, while under the standard procedure the process took 57 days.
Direct settlement already covers 55% of all settled cases. This allows the client to assess their insurer’s service and makes the service experience an important element of market competition.
Personalisation of tariffs and bonus–malus
Since 2025 insurers have been setting payments using their own methodologies, which has allowed tariffs to be personalised. The launched bonus–malus system takes into account the driver’s and the vehicle’s insurance history, offering discounts for years without accidents — the discount can reach 40%.
Data for the calculations are taken from the centralized database of the Motor (Transport) Insurance Bureau of Ukraine (MTSBU), so the calculation does not require certificates and is performed when the policy is issued. For new vehicles or first-ever policies a standard tariff is used, and the discount accumulates over the years.
Market indicators and the role of service
The auto-civilka market has low margins and a high claims frequency: in 2025 some 150 982 claims were settled, the accident frequency rose to 2 cases per 100 contracts, and in the first quarter of 2026 it approached three. Over the year the market received 446 complaints — 0.3%.
ARX emphasises that the winner will be the insurer that combines accurate risk calculation with high-quality service. “I would not claim that tariff personalisation will automatically make auto-civilka profitable for the market. Rising repair costs may offset that effect, and the true picture will be seen after several years of observation,” the piece says.
ARX has operated in Ukraine for 31 years and has been the leader of the Ukrainian comprehensive auto insurance (KASKO) market for 17 years. The company notes that it has transferred services from KASKO into its compulsory product: a client with an ARX auto-civilka policy can report an event in the MyARX app and receive 24/7 information support and the “Autoconcierge” service.