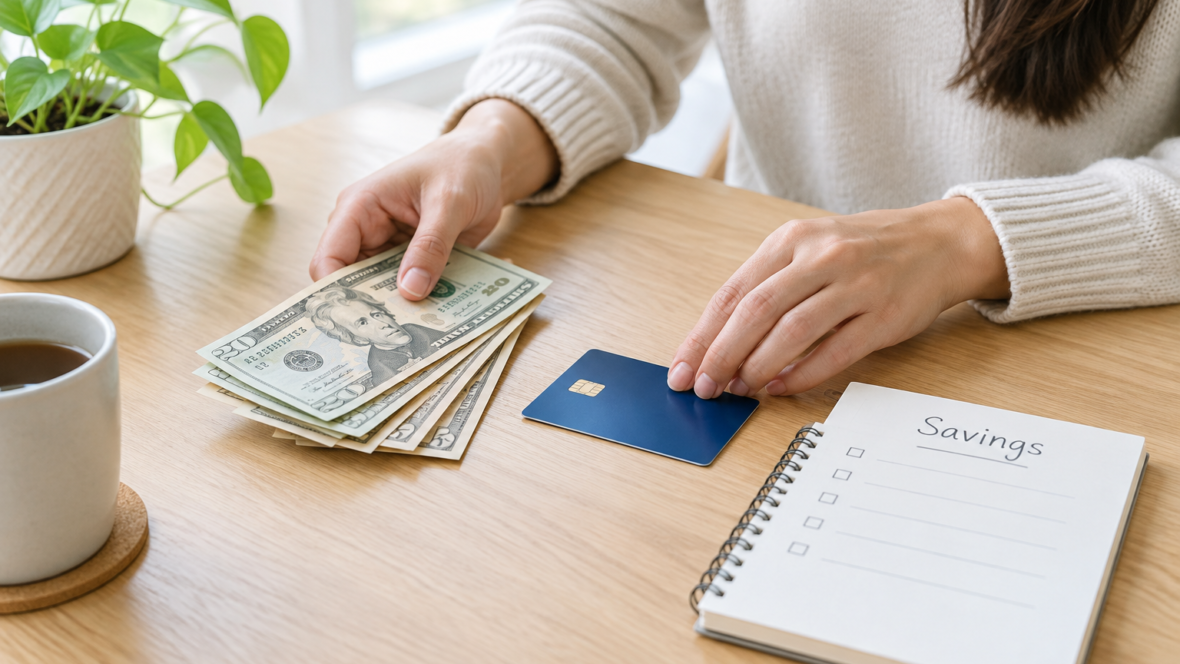
Спеціалісти «Фінкульт» пояснили, які варіанти зберігання грошей підходять для різних потреб: картка і поточний рахунок — для щоденних розрахунків, депозит — для накопичень, готівка — для швидкого доступу.
Card and current account — for daily payments
A current account with a payment card is intended for everyday transactions: paying for purchases, making transfers and quick access to funds. Before opening an account you should check the account maintenance fees, transfer commissions and the mobile banking capabilities.
A deposit is described as money that a client hands over to a bank under certain conditions; the bank may pay interest for using those funds. The size of the return and the procedure for paying interest depend on the terms of the deposit.
Financial cushion and cash at home
A financial cushion is part of your savings for unexpected expenses that should remain accessible without restrictions. A client needs to assess what portion of their savings should be kept easily available.
Regardless of the chosen storage method, you should use strong passwords, enable transaction notifications and never disclose your PIN, CVV code or one‑time confirmation passwords to anyone.
Who will repay and how much if a bank becomes insolvent
In Ukraine, depositors’ funds are protected by the Deposit Guarantee Fund for Individuals (Фонд гарантування вкладів фізичних осіб, ФГВФО).
The guarantee of full compensation applies during martial law and for three months after it is lifted or cancelled.
After that, the guaranteed amount will be at least 600 000 UAH per depositor in a single bank — regardless of the number of accounts and deposits. The protection covers deposits, current and card accounts of individuals and individual entrepreneurs (FOP) in banks that are participants in the system. If a bank is declared insolvent, the Fund will organise payment of the guaranteed compensation in accordance with the law.