
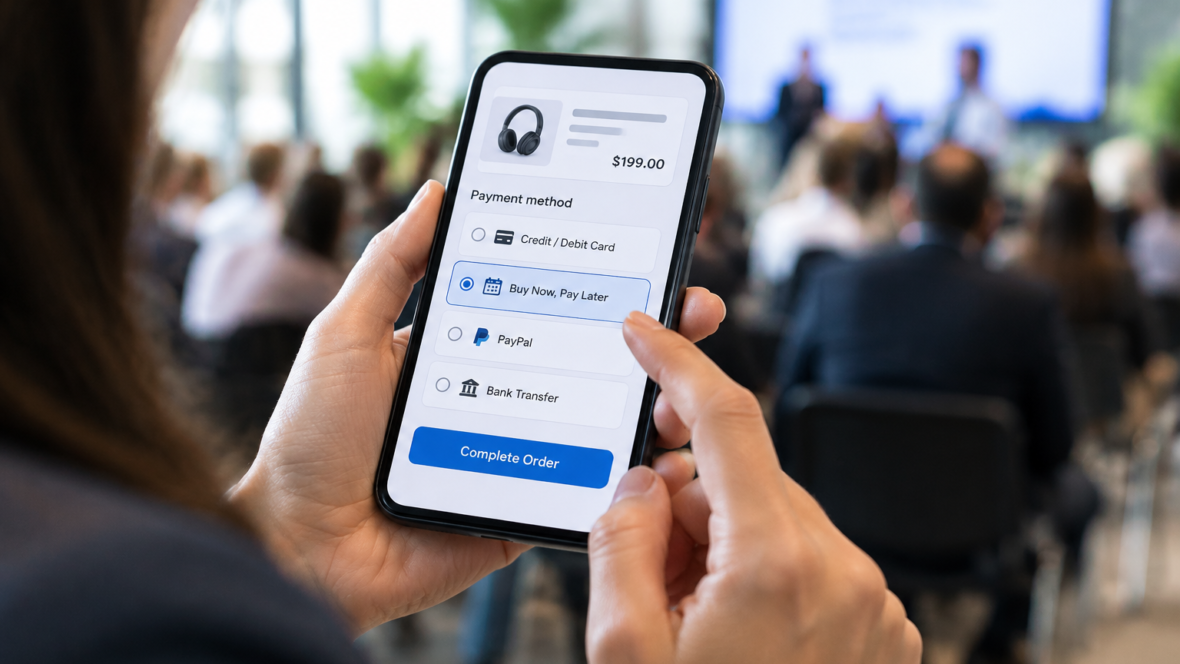
MyCredit at the FinRetail 2026 conference explained how alternative financing helps online stores preserve sales when a bank refuses a buyer an instalment plan. The buyer selects a product, the bank declines the instalment, and the store risks losing the sale.
Alternative financing as a complement to bank solutions
The company proposes working with retailers not to compete with banks but to provide an additional way to finance a purchase. If a bank approves an instalment for the required amount, the customer completes the order as usual.
If the bank refuses or offers an insufficient credit limit, alternative financing can serve as an alternative payment method. The company’s proprietary risk-assessment system sometimes approves applications that banks have rejected, evaluating each request according to the company’s own criteria and making decisions quickly.
Technology backbone — the Kolibri service
Development of the company’s own Kolibri service under the “buy now, pay later” model (Buy Now, Pay Later — BNPL) began before the full-scale invasion. The project allowed rapid processing of applications, but regulatory restrictions prevented the planned model of direct settlements with stores, so it was put on hold.
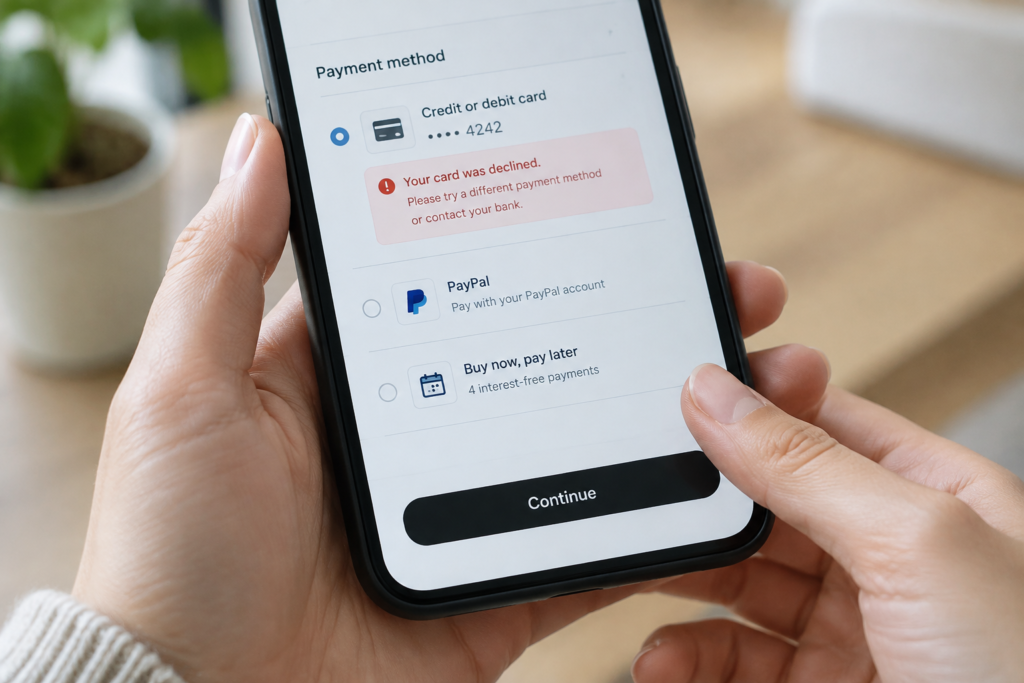
Speed of decision-making is cited as one of the key advantages for e-commerce. The less time a buyer spends waiting for a financial decision, the higher the chances they will complete the purchase.
Responsible lending and returns
When assessing an application, the scoring system evaluates the available information about the customer and their ability to pay. Based on this assessment, the company may approve the requested amount, offer a smaller sum, or refuse financing.
In the event of a product return, the store transmits the information through the system and the outstanding credit is recalculated. This is intended to avoid additional procedures and document exchanges between the buyer, the store and the lender.
Invitation to retailers to test
During his presentation, Vladyslav Bilan urged retail representatives to move to practical testing of the solution. He suggested giving the company a single basket and a segment of buyers who were refused by banks so they could demonstrate the effect in practice.
“We are not taking customers from banks — we are returning to the store the sales it might otherwise have lost. Give us one basket and a segment of buyers who were refused by the bank. We will show in practice how many sales can be saved without undue risk or complication,” summarised Vladyslav Bilan.
The company is inviting online stores to collaborate and test alternative financing solutions to assess their potential to increase conversion and preserve sales.