
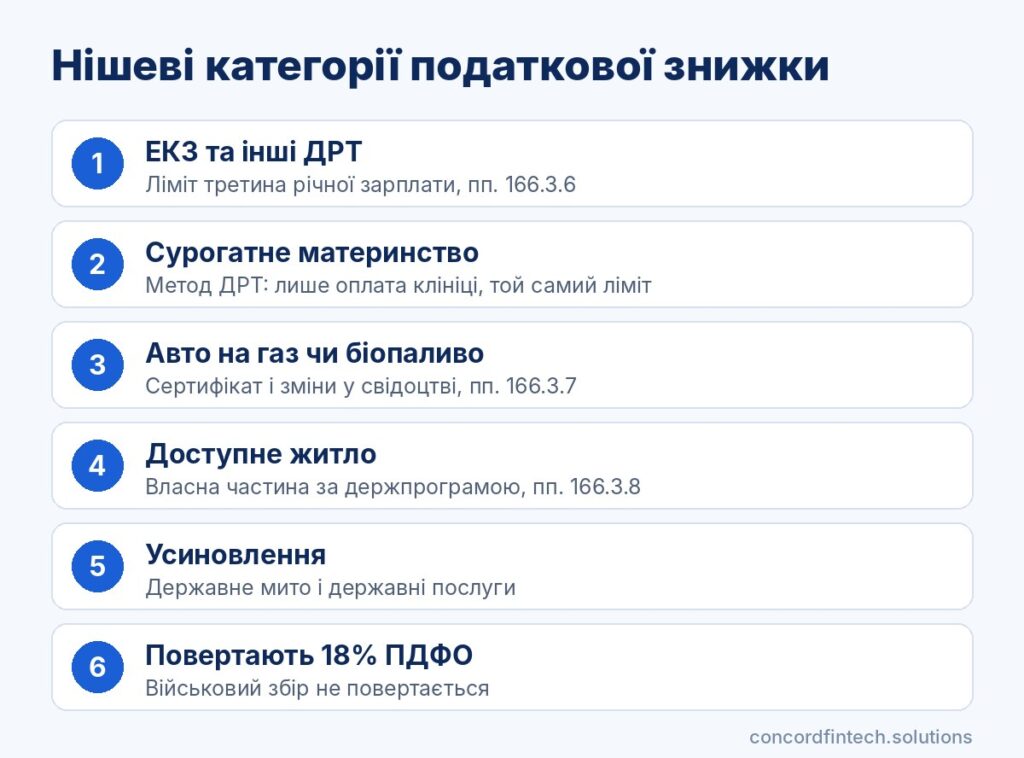
The tax deduction for in vitro fertilisation (IVF) allows an employee to reclaim 18% of the amount paid to a clinic for assisted reproductive technologies (ART), but only expenses up to one third of the annual salary are taken into account. The same principle applies to less well known categories: surrogacy as a method of assisted reproductive technologies (ART), converting a personally owned car to run on gas or biofuel, construction or purchase of affordable housing under a state programme, and state services related to adoption. Only personal income tax (PIT) withheld from salary is returned; the 5% military levy remains with the budget.
Expenses for 2026 are declared in the tax return with Annex F3, which can be submitted until 31 December 2027 inclusive. For 2025 expenses the deadline is 31 December 2026, so those who have not yet filed should do so before the end of the year. The conditions for each category, the documents required and calculation examples are summarised below according to Article 166 of the Tax Code of Ukraine (TCU).
| Category | Limit | Documents | Provision of the Tax Code |
|---|---|---|---|
| IVF and other assisted reproductive technologies (ART) | No more than 1/3 of annual salary | Contract with the clinic, service acts, payment documents | subparagraph 166.3.6 |
| Surrogacy (as an ART method) | Within the same 1/3 salary limit | Contract with the clinic for the programme, payment documents, marriage certificate | subparagraph 166.3.6 |
| Converting a car to run on gas or biofuel | Actual expenses, but not more than annual salary | Payment documents, certificate of conformity or technical expert report, vehicle registration certificate | subparagraph 166.3.7 |
| Affordable housing under a state programme | Actual expenses, but not more than annual salary | Purchase or investment contract, payment documents, bank statement | subparagraph 166.3.8 |
Deduction for IVF and other assisted reproductive technologies (ART)
Which procedures and expenses qualify
Subparagraph 166.3.6 of the Tax Code of Ukraine allows inclusion of expenses for assisted reproductive technologies (ART) in the deduction, in line with conditions set by law. The list of methods and mandatory examinations is established by the Procedure for the application of ART, approved by the Ministry of Health (MoH) under Order No. 787, so the deduction covers not only extracorporeal fertilisation itself but also consultations, analyses and examinations that are part of the programme. The law does not limit the number of attempts; only the total amount per year matters.
Medicines bought separately at a pharmacy are a risk area. The deduction for treatment under subparagraph 166.3.4 is not in force as of October 2026, so the tax authority may not recognise pharmacy receipts as ART expenses. It is more reliable if the drugs used during the programme are included on the clinic’s invoice and service act.
Limit: one third of annual salary
The amount of ART expenses cannot exceed one third of salary income for the reporting year. For example, with a salary of 20 000 UAH per month the annual income is 240 000 UAH and the limit is 80 000 UAH. If an IVF programme cost 95 000 UAH, only 80 000 UAH are taken into account and 14 400 UAH are refunded. The remaining 15 000 UAH cannot be carried forward to the next year.
Requirements for the clinic and who can claim
Services must be provided by a healthcare institution licensed for medical practice, and the licence details should be checked in the contract. In tax guidance the claimant of the deduction is usually the woman who underwent the ART programme, and she must have paid for the services. If the contract and payment documents are issued to the husband, it is wise to obtain an individual tax consultation before filing, because the position of the State Tax Service (STS) regarding payments made by the husband on behalf of his wife is not unequivocal.
Documents from the clinic
Payment documents must identify the seller and buyer, the cost of services and the date of payment. Copies are attached to the return and originals must be kept for 1 095 days in case of inspection. A basic package for IVF looks like this:
- a contract with the clinic specifying the ART programme and licence details;
- acts of provided services or an extract from medical records documenting the programme;
- fiscal receipts, payment slips or bank statements in the claimant’s name;
- a certificate from the employer about wages and withheld personal income tax (PIT) or records from the State Register of Individuals - Taxpayers (DRFO).
Deduction for surrogacy
Why surrogacy is treated as ART
There is no separate subparagraph for surrogacy in the Tax Code, but the Procedure for the application of ART classifies it as a method of assisted reproductive technologies (ART), so such expenses are assessed under the same subparagraph 166.3.6 and within the same one‑third salary limit. The Family Code of Ukraine allows surrogacy only for married couples and only where there are medical indications.
Who can claim the deduction
The right to the deduction belongs to the spouse who receives salary from an employer and whose name appears on the clinic contract and payment documents. Foreigners and citizens who are not tax residents of Ukraine do not have this right.
Which expenses are accepted and which are not
The least problematic amounts are those paid to the clinic for the medical part of the programme: examinations, fertilisation, embryo transfer and medical support. Compensation to the surrogate, payment for her accommodation, legal and agency fees are not payments to a healthcare facility, so the tax authority will most likely refuse to include them. Therefore, the contract should clearly separate the cost of medical services from other payments.
Deduction for converting a car to run on gas or biofuel
What counts as conversion
Subparagraph 166.3.7 allows costs paid in connection with converting a taxpayer’s vehicle to operate on mixed motor fuel, bioethanol, biodiesel, compressed or liquefied gas and other types of biofuel. Buying a car that already has factory‑installed gas equipment is not considered a conversion and does not qualify for the deduction.
Certificate of conformity and registration of changes
After installation the service provider issues a certificate of conformity or a technical expert report in accordance with the procedure approved by a Cabinet of Ministers of Ukraine (CMU) resolution No. 607. The changes must then be entered in the vehicle registration certificate through the service centre of the Ministry of Internal Affairs. Without these documents the tax authority will treat the payments as ordinary repairs and deny the deduction.
Vehicle ownership limits and calculation example
The vehicle must be registered in the name of the person filing the return, and the conversion must have been paid for by that person. There is no separate limit for this category, but the total deduction cannot exceed the annual salary. For example, the owner of a car with a salary of 15 000 UAH per month paid 28 000 UAH for gas equipment and work, so the refund due is 5 040 UAH.
Deduction for affordable housing and adoption
State affordable housing programme
Subparagraph 166.3.8 covers expenses for construction or purchase of affordable housing under state programmes, including repayment of a subsidised mortgage for these purposes and the interest on it. Under the procedure approved by Cabinet of Ministers of Ukraine (CMU) Resolution No. 819, the state pays 30% of the cost of the standard area, and for certain categories, including internally displaced persons (IDPs) and veterans, 50%. The deduction includes only the purchaser’s own share - that is, 70% or 50% of the cost.
The “YeOselia” mortgage programme is not included in this category because the state does not pay part of the housing cost. Interest under that programme is taken into account as for a regular mortgage under subparagraph 166.3.1 and Article 175 of the Tax Code of Ukraine (TCU).
Who is eligible and what documents are required
The deduction is granted to the programme participant who paid their share from their own funds. Required documents include the purchase or investment contract, documents confirming participation in the programme, payment documents, and for a loan a bank statement showing repaid principal and interest paid during the year. Because the contribution is usually large, it is typically limited by annual salary in practice; someone earning 25 000 UAH per month would be able to reclaim no more than 54 000 UAH.
Adoption: fees and state services
Subparagraph 166.3.6 also lists expenses for state services related to adoption, including state fees. These are confirmed by the court decision on adoption and payment receipts.
How to claim the deduction and avoid refusal
Annex F3 and the deadline of 31 December 2027
The deduction for all categories is claimed using Annex F3 to the tax return on property and income, which is filed in the Electronic Cabinet or at a State Tax Service (STS) service centre. For 2026 expenses the deadline is 31 December 2027, and the general 30 April deadline does not apply to such a return. The steps are as follows.
- Gather contracts, service acts, payment documents and documents recording changes for 2026.
- Request records from the State Register of Individuals - Taxpayers (DRFO) or obtain a certificate from the employer about wages and withheld personal income tax (PIT).
- Check the one‑third salary limit for ART and the overall annual salary cap.
- Complete the tax return with Annex F3 and attach scanned copies of documents.
- Include a refund request with your IBAN and wait for funds within 60 days.
Combining categories
You can claim several categories in one return, for example IVF, a child’s education and car conversion. Each item is first checked against its own limit, and then the total amount is compared to annual salary, reduced by the tax social allowance if it was applied. You cannot receive more than the employer withheld in personal income tax (PIT) during the year.
Common reasons for refusal
The tax authority most often refuses when payment documents are issued to someone other than the claimant. Other frequent reasons include absence of a certificate or updates in the vehicle registration certificate, pharmacy receipts unlinked to the clinic’s programme, and including the military levy in the refundable amount. Decisions can be appealed under Article 56 of the Tax Code of Ukraine (TCU) within 10 working days, or you can file an amended return with a corrected calculation.
Frequently asked questions
Are medicines accounted for during IVF?
Medications whose cost is included on the clinic’s invoice for the ART programme are generally accepted together with other services. Medicines bought separately at a pharmacy may be rejected by the tax authority because the deduction for treatment was not in force as of October 2026.
Can a husband claim the deduction for his wife’s IVF?
The deduction is claimed by the person who receives salary and whose name is on the contract and payment documents. In tax guidance the authority tends to focus on the woman who underwent the programme, so if the husband paid, obtain an individual tax consultation in advance.
Does conversion to gas qualify?
Yes - subparagraph 166.3.7 explicitly mentions compressed and liquefied gas, so installing LPG or CNG equipment for propane or methane qualifies. Mandatory conditions are: the vehicle is owned by the claimant, there is a certificate of conformity or an expert report, and the changes have been entered in the vehicle registration certificate.
How do I get a deduction for affordable housing?
You must first join the state programme and pay your share of the housing cost or contributions on a subsidised loan. After that you declare the year’s expenses in Annex F3; the refund is limited to the personal income tax (PIT) withheld from salary.