
In 2026 an individual entrepreneur (FOP) in group 1 pays at least 3 099,84 UAH per month, and an individual entrepreneur in group 2 pays 4 496,44 UAH, if the single tax (ЄП) is taken at the maximum rate, together with the military levy (VZ) and the minimum Unified Social Contribution (ЄСВ) for themselves. On group 3 and on the general tax system the only fixed amount is the Unified Social Contribution (ЄСВ) of 1 902,34 UAH per month, while the single tax (ЄП), personal income tax (PIT, ПДФО) and the military levy (VZ) depend on income.
Below all sums are consolidated into one table for month, quarter and year, and payment and reporting deadlines through the end of 2026 are shown. Rates of the single tax (ЄП) for groups 1 and 2 are set by local councils, so the calculations use the maximum sizes provided by the Tax Code.
Key 2026 figures for calculating FOP taxes
Minimum salary and subsistence minimum
Almost all fixed payments for entrepreneurs are linked to two indicators as of 1 January 2026. The minimum wage is 8 647 UAH, and the subsistence minimum for able-bodied persons is 3 328 UAH.
The Unified Social Contribution (ЄСВ), the military levy (VZ) for groups 1 and 2, the group-2 single tax (ЄП) rate and income limits are calculated from the minimum wage. The single tax (ЄП) for group 1 depends only on the subsistence minimum: the maximum amount equals 10% of that indicator.
Maximum base for ЄСВ
The minimum contribution equals 22% of the minimum wage, i.e. 1 902,34 UAH per month or 5 707,02 UAH per quarter. The maximum assessment base is 20 minimum wages, i.e. 172 940 UAH per month.
Therefore the largest possible Unified Social Contribution (ЄСВ) for oneself in 2026 equals 38 046,80 UAH per month. Single-tax payers may voluntarily pay more than the minimum to increase future pension entitlements, while for the general tax system the amount depends on net income.
Group income limits
The annual revenue caps for single-tax payers are also calculated from the minimum wage as of 1 January. For group 1 this is 1 444 049 UAH, for group 2 7 211 598 UAH, and for group 3 10 091 049 UAH.
The consolidated table below shows the cap amounts for each regime. For group 3 the example assumes income of 500 000 UAH per quarter, and for the general system a net income of 300 000 UAH per year.
| Group | ЄП | VZ | ЄСВ | Total per month | Total per year | Payment deadline |
|---|---|---|---|---|---|---|
| Group 1 | up to 332,80 UAH/month | 864,70 UAH/month | 1 902,34 UAH/month | 3 099,84 UAH | 37 198,08 UAH | ЄП and VZ by the 20th day of the current month, ЄСВ quarterly |
| Group 2 | up to 1 729,40 UAH/month | 864,70 UAH/month | 1 902,34 UAH/month | 4 496,44 UAH | 53 957,28 UAH | ЄП and VZ by the 20th day of the current month, ЄСВ quarterly |
| Group 3 (5%, income 500 000 UAH/qtr.) | 25 000 UAH/qtr. | 5 000 UAH/qtr. | 5 707,02 UAH/qtr. | 11 902,34 UAH | 142 828,08 UAH | ЄП and VZ within 50 days after the quarter |
| General system (net income 300 000 UAH/year) | PIT 18%: 54 000 UAH | 5%: 15 000 UAH | 22%: 66 000 UAH | 11 250 UAH | 135 000 UAH | Advance payments quarterly, year-end calculation by 1 May |
With no income on group 3 the only mandatory payment remains the minimum Unified Social Contribution (ЄСВ) of 22 828,08 UAH per year, while on the general system in months without net income ЄСВ may not be payable. For groups 1 and 2 the fixed amounts do not decrease even if there were no sales.
FOP taxes for group 1 in 2026
Single tax 332,80 UAH
The rate for group 1 cannot exceed 10% of the subsistence minimum for able-bodied persons, so the maximum is 332,80 UAH per month. Check the specific rate for your activity in the decision of the local council for your tax address.
The tax is paid in advance no later than the 20th day of the current month. At the maximum rate this amounts to 3 993,60 UAH per year.
Military levy 864,70 UAH
For group 1 the military levy is fixed and equals 10% of the minimum wage, i.e. 864,70 UAH per month. It is paid with a separate payment order on the same deadlines as the single tax (ЄП).
For group 1 the military levy is more than twice the maximum single tax. Over a year this payment portion totals 10 376,40 UAH.
ЄСВ and payment deadlines
The minimum Unified Social Contribution (ЄСВ) for group 1 is the same as for other entrepreneurs and equals 5 707,02 UAH per quarter. The contribution is paid no later than the 19th day of the month following the quarter.
The differences between the groups are most visible in monthly sums. For quick orientation, here is the minimum each group pays per month including ЄСВ for themselves:
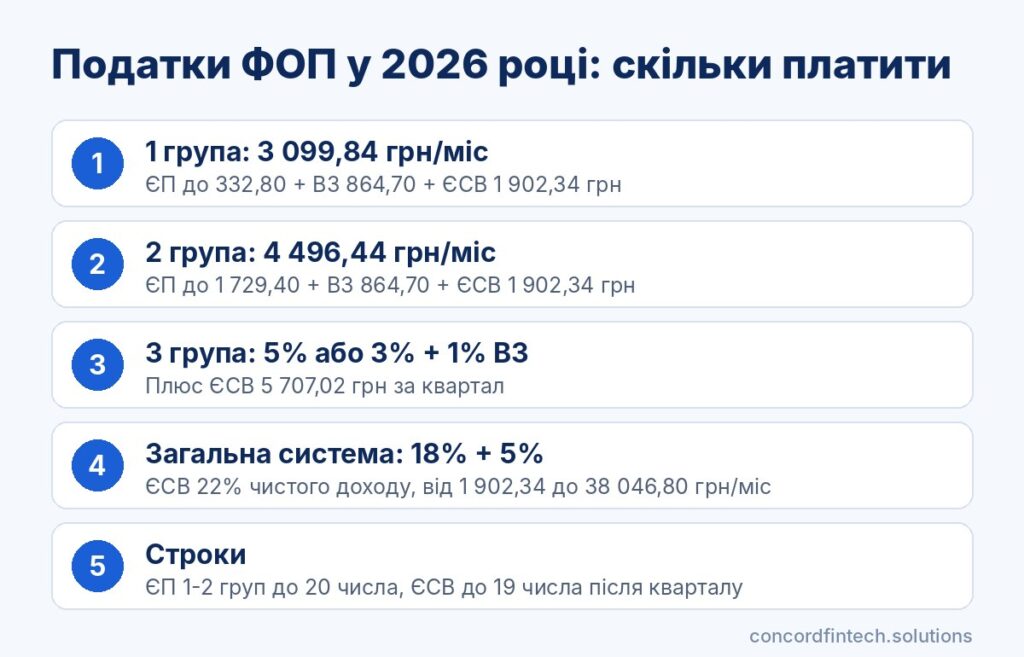
- Group 1: 3 099,84 UAH (332,80 ЄП + 864,70 VZ + 1 902,34 ЄСВ);
- Group 2: 4 496,44 UAH (1 729,40 ЄП + 864,70 VZ + 1 902,34 ЄСВ);
- Group 3: 1 902,34 UAH ЄСВ plus 6% of income at the 5% rate or 4% of income at the 3% rate with VAT (value-added tax, VAT, ПДВ);
- General system: ЄСВ from 1 902,34 UAH plus 23% of net income in the form of personal income tax (PIT, ПДФО) and the military levy.
FOP taxes for group 2 in 2026
Single tax 1 729,40 UAH
The maximum rate for group 2 is set at 20% of the minimum wage, i.e. 1 729,40 UAH per month. A local council may approve a lower rate, so before paying check the amount in the Electronic Cabinet.
At the maximum rate the entrepreneur pays 20 752,80 UAH of single tax per year. The deadline is the same as for group 1: in advance by the 20th day of the current month.
Military levy 864,70 UAH
The military levy for group 2 does not depend on the ЄП rate and also equals 864,70 UAH per month. Together with the single tax this is 2 594,10 UAH per month excluding ЄСВ.
Absence of income does not exempt from this payment. Exemptions apply only in cases explicitly provided by the Tax Code, so a business downtime is not a basis for relief.
ЄСВ for oneself and employees
For themselves a group-2 entrepreneur pays at least 1 902,34 UAH per month, so the total burden is 4 496,44 UAH per month or 53 957,28 UAH per year. The contribution for oneself is paid quarterly no later than the 19th day of the month after the quarter.
For each employee ЄСВ equals 22% of salary, but not less than 1 902,34 UAH per month for full employment. This contribution is paid together with salary payments, no later than the 20th day of the following month, and reported quarterly in the unified tax return within 40 days after the quarter.
FOP taxes for group 3 in 2026
5% or 3% with VAT
On group 3 the single tax (ЄП) is calculated on all received income without deducting expenses. The rate is 5% for non–VAT payers or 3% for registered VAT payers, while in the latter case VAT is also paid separately.
With income of 500 000 UAH per quarter the single tax is 25 000 UAH at the 5% rate or 15 000 UAH at the 3% rate. The tax is paid within 10 days after the deadline for filing the quarterly declaration, i.e. effectively within 50 days after the quarter.
1% military levy
The military levy for group 3 is 1% of income regardless of the chosen ЄП rate. In the example with 500 000 UAH quarterly income this is 5 000 UAH.
The levy is reported in the same declaration and paid on the same deadline as the single tax. If there was no income for the quarter, the military levy is zero.
Quarterly ЄСВ
On group 3 ЄСВ does not depend on income and equals at least 5 707,02 UAH per quarter. In the example the total payments for the quarter equal 35 707,02 UAH, and 142 828,08 UAH for the year.
The declaration for Q3 2026 must be filed by 9 November 2026, and ЄП and the military levy paid by 19 November. The annual calculation of ЄСВ is submitted as an annex to the Q4 declaration.
Taxes for FOPs on the general tax system
PIT 18% and VZ 5%
An entrepreneur on the general tax system pays 18% personal income tax (PIT, ПДФО) and 5% military levy (VZ) on taxable net income, that is income minus documented expenses. Without expenses taxes on the general system total 23% compared with 6% on group 3.
In the example with net income of 300 000 UAH per year PIT equals 54 000 UAH and the military levy 15 000 UAH. The example is simplified because the exact base depends on the entrepreneur’s accounting of income and expenses.
ЄСВ 22% of net income
On the general system ЄСВ is calculated as 22% of net income, but not less than the minimum contribution of 1 902,34 UAH per month. The maximum is limited by the assessment base of 172 940 UAH, so the contribution cannot exceed 38 046,80 UAH per month or 456 561,60 UAH per year.
With net income of 300 000 UAH ЄСВ equals 66 000 UAH per year. The annual calculation of the contribution is submitted in annex ЄСВ-1 to the declaration of property status and income.
Advance payments
During the year an entrepreneur on the general system pays advance payments of PIT and the military levy for Q1, Q2 and Q3. The advance for Q3 2026 must be paid by 19 October, and no advance is calculated for Q4.
The 2026 declaration is filed by 1 May 2027, and the final amount is paid within 10 days after the filing deadline. Previously paid advances are credited against the annual obligation.
Payment deadlines for FOP taxes in 2026
Monthly payments for groups 1–2
The single tax (ЄП) and the military levy (VZ) for groups 1 and 2 are paid in advance no later than the 20th day of the month for which they are due. It is possible to pay in advance for a quarter or a year, but not later than the end of the current reporting year.
In December 2026 the 20th falls on a Sunday. To avoid disputes about shifting the deadline, it is better to make December payments by 18 December.
Quarterly payments for group 3
Group-3 entrepreneurs file their declaration within 40 days after the quarter and pay taxes within the following 10 days. For Q4 2026 the declaration must be filed by 9 February 2027 and ЄП and the military levy paid by 19 February 2027.
Entrepreneurs of groups 1 and 2 report once a year. Their annual declaration for 2026 is filed within 60 days after year-end, i.e. by 1 March 2027.
ЄСВ quarterly by the 19th
The law “On the collection and accounting of the single contribution” requires ЄСВ for oneself to be paid by the 20th day of the month after the quarter, so the last acceptable day is considered the 19th. Deadlines in 2026 coincide for all single-tax groups and the general system.
There are several tight deadlines at the end of the year. The calendar of main payments for Q4 2026 looks like this:
- by 19 October: ЄСВ for Q3 (5 707,02 UAH) and advance PIT and VZ for the general system;
- by 20 October: ЄП and VZ for groups 1–2 for October;
- by 9 November: group-3 declaration and the employer’s unified calculation for Q3;
- by 19 November: ЄП and VZ for group 3 for Q3;
- by 20 November: ЄП and VZ for groups 1–2 for November;
- by 18 December (20 December is Sunday): ЄП and VZ for groups 1–2 for December;
- by 19 January 2027: ЄСВ for Q4 2026.
What will change in FOP taxes in 2027
New minimum wage in the 2027 budget
The draft state budget for 2027 No.16000 envisages a minimum wage of 9 546 UAH and a subsistence minimum for able-bodied persons of 3 691 UAH. As of October 2026 this is only a draft, so figures may change.
If the indicators are approved, the minimum ЄСВ will rise to 2 100,12 UAH per month, the military levy for groups 1–2 to 954,60 UAH, and the single tax (ЄП) for group 2 to 1 909,20 UAH. Then the annual fixed payments for group 2 would be 59 567,04 UAH versus 53 957,28 UAH in 2026.
NACE 2.1-UA replacing KVED
From 1 January 2027 the classification NACE 2.1-UA under the State Statistics Service order No.191 comes into force. During 2027 the old KVED-2010 codes and the new codes will be used in parallel.
There is no need to submit applications to change codes before 2027. It is worth checking your activities against the concordance tables in advance, because tax-group eligibility depends on the codes.
VAT status for FOPs
As of October 2026 mandatory registration of single-tax payers as VAT payers has not been introduced by law. The Ministry of Finance published draft laws with thresholds first at 1 million and then 4 million UAH of annual income, but none has been adopted.
Therefore ЄП and military levy rates for 2027 will depend primarily on the approved budget. The table in this article will be updated after its adoption.
How to pay FOP taxes without mistakes
Where to find payment accounts
Account details depend on the tax address and the type of payment, so there is no single account for the whole country. The easiest way to get them is in the Electronic Cabinet in the “Budget settlement status” section or on the SFS website in the budget accounts section for your region.
ЄСВ, the single tax (ЄП) and the military levy (VZ) are credited to different accounts. Therefore you cannot transfer one sum for all payments — each requires a separate payment instruction.
Payment purpose
The payment description begins with the payment type code; for a standard tax or contribution payment this is code 101. Then indicate the payment name, period and taxpayer ID, for example “101 ЄСВ for QIII 2026”.
If you make a mistake with the account, the money does not disappear but will be credited to the wrong place. You can request a transfer or refund by application, while the deadline for the required payment may already have passed.
Typical mistakes by entrepreneurs
The most common mistakes by groups 1 and 2 are forgetting the military levy or paying it together with ЄП in one payment. Another common error is not paying ЄСВ in months without income, although for single-tax payers the obligation does not depend on income.
For non-payment of ЄСВ a penalty of 20% and a daily fine of 0.1% for each day of delay are applied, and there is no instalment plan for such a debt. Rules for tax payments are set by the Tax Code, and for the contribution by the Law No.2464-VI.
Frequently asked questions
How much does a group-2 FOP pay per month in 2026?
At the maximum rate a group-2 entrepreneur pays 1 729,40 UAH single tax (ЄП) and 864,70 UAH military levy (VZ) per month. Together with the minimum Unified Social Contribution (ЄСВ) of 1 902,34 UAH this is 4 496,44 UAH per month or 53 957,28 UAH per year.
Does an FOP pay the military levy if there is no income?
For groups 1 and 2 the military levy is fixed, so it is paid even without income. For group 3 and the general system the levy is calculated from income, so nothing is payable if there is no income.
When will FOP tax amounts change?
Fixed payments are reviewed from 1 January together with the minimum wage and the subsistence minimum. New amounts for 2027 will be final after the state budget is adopted.
Can the single tax be paid in advance for the year?
Yes, entrepreneurs in groups 1 and 2 can pay the single tax and the military levy in advance, but not for more than the end of the current year. If the rate changes during the year or the FOP closes, an overpayment can be credited to other payments or refunded upon application.