The Verkhovna Rada Committee on Finance, Tax and Customs Policy recommended that parliament adopt, at second reading and in its entirety, draft law No. 16037-d, which provides for the simplification of the administration of the value-added tax (VAT).
Changes to inspection and reporting procedures
The draft raises the threshold for unscheduled documentary inspections concerning the declaration of budget reimbursement and/or negative VAT balances from UAH 100,000 to UAH 1,000,000. It also proposes to give VAT payers — individual entrepreneurs (FOP) — the option to choose their reporting period themselves: monthly or quarterly.
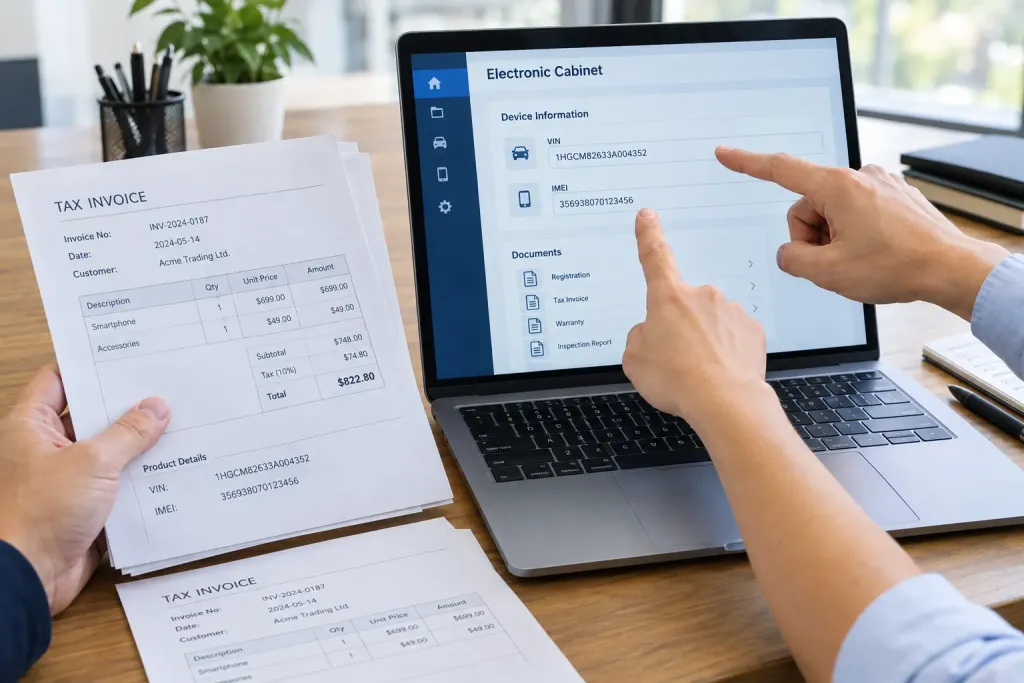
The document provides for expanding the capabilities of the taxpayer electronic cabinet with automatic pre-filling of reports and tax invoices. New rules for issuing consolidated tax invoices are being introduced: a single consolidated invoice may be issued no later than the last day of the month for supplies to persons who are not VAT payers.
- Raising the threshold for unscheduled inspections from UAH 100,000 to UAH 1,000,000.
- VAT-paying individual entrepreneurs (FOP) will be able to choose their reporting period — monthly or quarterly.
- Automatic pre-filling of reports and tax invoices in the electronic cabinet.
- Rules for consolidated tax invoices — a single consolidated invoice by the last day of the month for supplies to non-VAT payers.
- A mechanism to encourage voluntary payment of liabilities assessed as a result of documentary inspections during the period of martial law.
- Simplification of the transfer of negative VAT balances when a legal entity is transformed, provided timely re-registration without a documentary inspection.
- Temporary easing of restrictions on the purchase of excise stamps without applying anti-forestalling restrictions.
- Harmonisation of tax law provisions with changes in the field of mortgage bonds after the entry into force of the Law of Ukraine «On Securitisation and Covered Bonds».
Additional amendments on technical requirements and taxation of car sales
During the revision, amendments were taken into account concerning the specifics of filling in tax invoices for transactions involving the supply of vehicles and phones — the mandatory inclusion of VIN codes and IMEI numbers. This requirement has been added to the provisions on issuing tax invoices.
Provisions were also added regarding the taxation of individuals’ income from the sale of vehicles, taking into account the period of ownership by the taxpayer. An exception is made for cases where the vehicle is received as an inheritance.