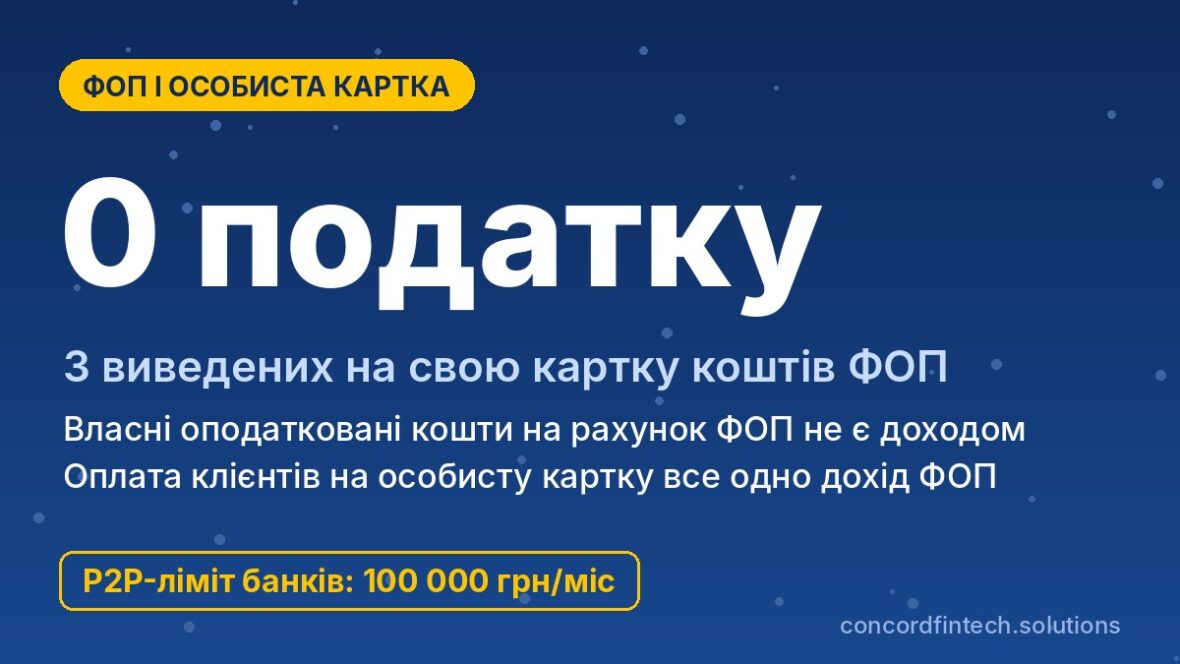
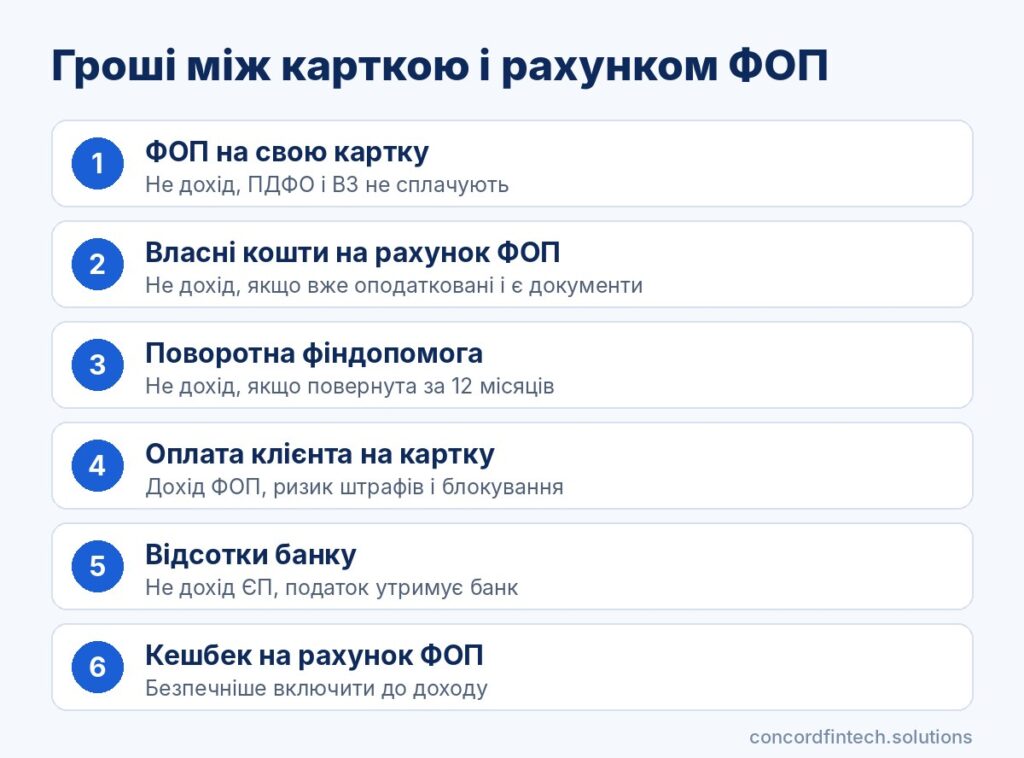
Transfer from an individual’s personal card to an individual entrepreneur (FOP) and the reverse withdrawal of funds are not prohibited by law, but the tax consequences of these operations differ. Money that an entrepreneur transfers from the FOP account to their personal card after paying taxes is not taxed again. Top-ups of an FOP account with personal funds are not regarded as income if those funds have already been taxed and their origin can be documented.
The greatest risk arises when clients pay for goods or services to a personal card instead of the FOP account. Such money is nevertheless income of the entrepreneur, and the method of receipt violates bank rules and may have consequences regarding cash registers (RRO/PRRO).
Transfer from an FOP account to a personal card
Is withdrawing funds taxable?
A payer of the single tax pays tax on income at the moment it is received into the account. Funds remaining after payment of the single tax and the single social contribution (SSC) belong to the entrepreneur as an individual, so personal income tax (PIT) and the military levy are not charged again when transferring them to a personal card. The law does not limit how often or how much may be withdrawn, nor does it require reporting what the money was spent on.
Correct payment purpose
Suitable wording includes “Transfer of FOP’s own funds for personal needs” or “Transfer of own funds, without value added tax (VAT)”. Avoid writing “salary” or “payment for services”, because an entrepreneur cannot be their own employer or contractor, and such wording will only raise questions from financial monitoring.
Bank limits and fees
A transfer from an FOP account to one’s own card is not a P2P transfer between individuals, but banks apply separate monthly limits for new and “dormant” FOPs. From 14 November 2026 they are 400 000 UAH for the 1st group and 1 000 000 UAH for the 2nd–3rd groups. Fees depend on the tariff: transfers within the same bank are often free, while transfers to a card at another bank may incur a charge.
Top‑up of an FOP account from a personal card
When this is not income
Paragraph 292.11 of the Tax Code of Ukraine does not explicitly list personal funds as an exception. However, the State Tax Service (DPS) in the ZIR (category 107.01.05) explains that an FOP’s own funds credited to a current account for entrepreneurial activity are not included in income if they were already taxed when accrued or paid.
This usually concerns salary, proceeds from sale of property or other amounts already taxed. Evidence includes data from the State Register of Individuals on income and withheld tax, a certificate from the employer or payment documents showing PIT has been paid.
How to indicate the payment purpose
The payment description determines whether the tax authority will treat the receipt as turnover. Common formulations are:
- “Top‑up of account with own funds (salary, from which personal income tax (PIT) and the military levy have been withheld)”.
- “Deposit of cash proceeds for the period from 01.10.2026 to 15.10.2026” for cash already accounted for in income.
- “Reimbursable financial assistance under agreement No. ___ dated ___” for funds from another person.
What to record in accounting and the declaration
Personal funds that have already been taxed are not entered in revenue accounting and are not shown in the single tax payer’s declaration. Cash proceeds are recorded once, on the day received from the buyer, and the amount deposited to the account must not exceed the income already recognised for that period.
Reimbursable financial assistance is not income if it is returned within 12 calendar months. Any amount not returned within that period becomes income after the deadline.
Client payments to a personal card: risks
Why this is FOP income
Money for goods or services received on a personal card remains income from entrepreneurial activity, and the State Tax Service requires it to be included in accounting and taxed. In addition, the Instruction of the National Bank of Ukraine (NBU) No. 162 of 29.07.2022 prohibits using an account for personal needs in entrepreneurial transactions, so a bank may restrict card servicing.
Risk of additional charges and fines
If such receipts are not reflected in accounting, the tax authority may assess additional tax and penalties during an audit. There is also a risk that the income will be classified as personal income and taxed at 23% without deducting expenses. Unrecorded proceeds may also indicate exceeding the group turnover limit, which in 2026 is 1 444 049 UAH for the 1st group and 7 211 598 UAH for the 2nd group.
Violation of cash register requirements (RRO/PRRO)
For FOPs required to use a registrar of settlement operations (RRO) or a software RRO (PRRO), payment to a card number is considered a settlement operation under the Law No. 265/95‑VR. From 1 August 2025 fines apply: 100% of the product value for the first violation and 150% for each subsequent violation if there is no fiscal receipt.
If a client pays via the bank to the entrepreneur’s IBAN, that is a banking operation and a check is usually not required. The obligation for the 1st group to use PRRO has been postponed until three months after the end of martial law.
P2P limits and enhanced monitoring in 2026
Abolition of the regulatory 150 000 UAH limit
NBU Resolution No. 102 of 27.08.2024 temporarily limited outgoing card‑to‑card transfers to 150 000 UAH per month from 1 October 2024. From 1 April 2025 this limit ceased to apply, and now banks set limits themselves within a risk‑based approach.
Internal bank limits under the Market Transparency Memorandum
The Market Transparency Memorandum for payment services, updated on 14 May 2026, envisages 100 000 UAH per month for low‑ and medium‑risk clients and 50 000 UAH for high‑risk clients without confirmed incomes. The limit applies to outgoing transfers, so more may be received, but frequent receipts from different people increase the risk level.
Signs of trading via personal cards
Financial monitoring pays attention to dozens of small transfers from various individuals, identical amounts and comments such as “for goods”. A scheme where money is credited to the FOP account and almost entirely withdrawn to a personal card on the same day also looks suspicious.
What is considered FOP income: case analysis
Loan from a relative
Funds from a relative to an FOP account without documents may be treated by the tax authority as income. To avoid this, draw up a reimbursable financial assistance agreement or receive the gift on a personal card, since gifts from first‑degree relatives are taxed at a zero rate.
Refund from a supplier
A supplier’s return of an advance payment for a cancelled order is a return of own funds, not proceeds. The payment purpose should be “Return of advance payment under invoice No.___”, and when the FOP returns money to a buyer, that amount under subparagraph 292.11 of the Tax Code of Ukraine is not included in income.
Cashback and bank interest
Interest on the account balance is passive income, which under subparagraph 1 of paragraph 292.1 of the Tax Code of Ukraine is not included in the single tax payer’s income, and PIT and the military levy on it are withheld by the bank. There is no separate exception for cashback to an FOP account, so it is safer to include cashback in income.
| Situation | FOP income? | Justification | Risk |
|---|---|---|---|
| Top‑up with own already taxed funds | No | Position of the State Tax Service in ZIR 107.01.05 | No documents proving taxation |
| Client payment to a personal card | Yes | Income from activity, subparagraph 1 of paragraph 292.1 of the Tax Code of Ukraine | Additional assessment, PRRO fines |
| Reimbursable financial assistance | No, if returned within 12 months | Subparagraph 3 of paragraph 292.11 of the Tax Code of Ukraine | Unreturned amount becomes income |
| Supplier’s refund of advance payment | No | Return of own funds | Unclear payment purpose |
| Refund to a buyer | Reduces income | Paragraph 292.11 of the Tax Code of Ukraine | No document confirming the refund |
| Cashback to an FOP account | Safer to treat as income | No direct exception | Dispute over classification |
| Interest on balance | No | Passive income | None, bank withholds tax |
| Transfer from a relative without an agreement | May be recognised as income | Uncompensated received funds | Additional single tax assessment |
In short, the rule is as follows. Income is payment for goods and services and funds without a confirmed source:
- income: payments from clients to an account or a personal card, unreturned reimbursable assistance, cashback to an FOP account;
- not income: own already taxed funds, returned reimbursable assistance, supplier refunds of advance payments, bank interest.
How to withdraw FOP funds correctly
Frequency and amounts
A bank pays attention not to the mere fact of withdrawal but to the pattern, so withdrawing the entire amount a few minutes after each receipt resembles transit operations. Simple rules help:
- First pay the single tax and the SSC, and withdraw only the remainder.
- Withdraw funds regularly, not immediately after each payment.
- Keep a reserve on the account for taxes and business expenses.
- Indicate in the payment purpose “Transfer of FOP’s own funds”.
- Pay suppliers from the FOP account, not from a personal card.
Separate cards for business and personal expenses
The most reliable approach is to have a business card linked to the FOP account and a separate personal card. This makes it easier to keep income records, and the bank sees a clear separation between business and household transactions.
Documents in case of a query
Keep contracts with clients, invoices, acceptance acts, declarations, income certificates and reimbursable assistance agreements. If the bank sends a query, respond on time and explain each operation separately, because a full response usually removes restrictions.
Frequently asked questions
Can I transfer money from the FOP account to my card?
Yes, an entrepreneur may at any time transfer funds from the FOP account to a personal card. After paying the single tax and the SSC, these funds are not taxed again.
Is topping up an FOP account from a personal card income?
No, if the funds have already been taxed and this can be proven with documents. In the payment purpose it is worth indicating the source, for example salary from which personal income tax (PIT) and the military levy were withheld.
Is there currently a limit on P2P transfers?
There is no NBU regulatory limit since April 2025, but banks under the Memorandum limit outgoing transfers to 100 000 UAH per month. For high‑risk clients without confirmed incomes the limit is 50 000 UAH.