
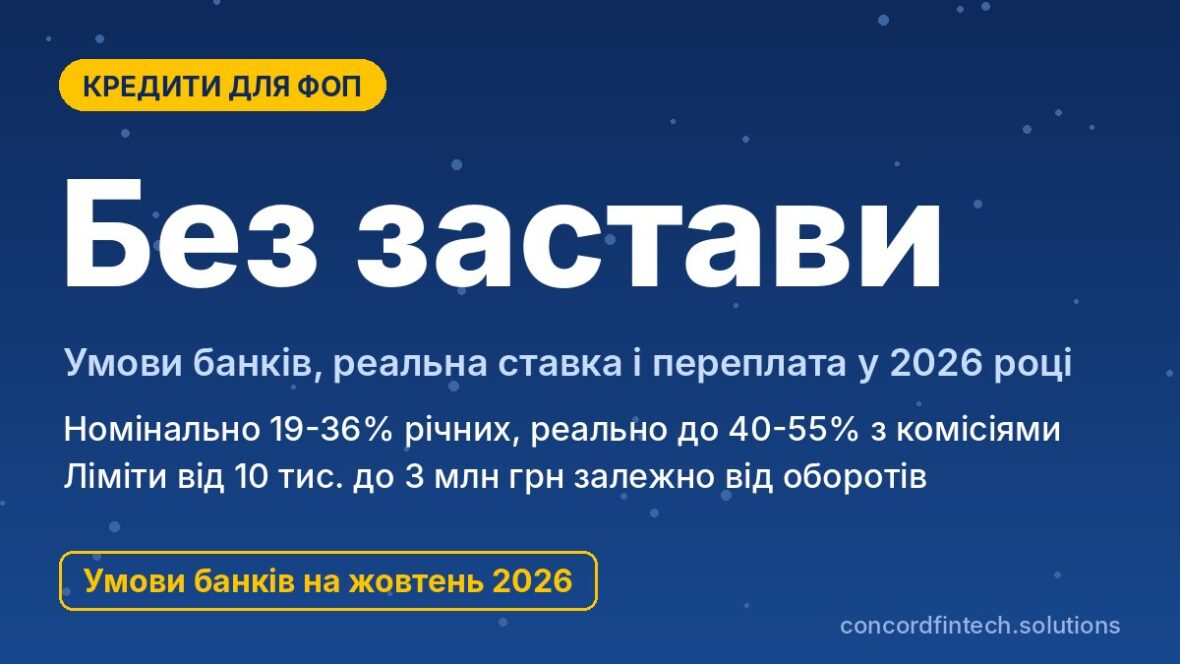
A loan for individual entrepreneurs (FOP) without collateral in 2026 can be obtained as a credit limit on a business card, an overdraft on a current account or an online loan with a repayment schedule. As of mid-October 2026 banks offer entrepreneurs unsecured amounts from 10,000 to 3,000,000 hryvnia, but nominal rates are roughly 19-36% per annum and, taking commissions into account, the real cost often reaches 40-55% per annum.
Below we explain how banks assess FOP and how much an entrepreneur actually overpays. All bank terms are given as at the time of preparing the article based on their official websites, so you should check them again before signing an agreement.
Which unsecured loans are available to FOP
Unsecured development loans
This is a classic loan with a fixed amount, term and equal monthly payments. For example, the online loan «vseBIZNES» at FUIB is issued to a sole proprietor for amounts from 50,000 to 3,000,000 hryvnia for terms of 12-36 months without collateral or guarantees.
Overdraft on an account
An overdraft lets you go “into the red” on a current account within an agreed limit, and any incoming funds automatically repay the debt. Interest is charged only on the amount actually used and only for the days of use. It is important to read carefully for whom the product is intended: for example, the business overdraft on the PrivatBank website is marked as a product for legal entities, while the bank offers entrepreneurs a credit limit.
Credit lines and business cards
A credit limit on a business card works similarly to an overdraft but has a grace period during which interest is not charged. At PrivatBank this is the credit limit «Pidpryiemnytskyi» up to 500,000 hryvnia with a grace period of up to 55 days; at Raiffeisen Bank there is the business card «100 days» with a limit of 10,000-500,000 hryvnia.
How banks assess FOP without collateral
Account turnover
Without collateral the bank risks its own funds, so the size of the limit is almost always tied to the entrepreneur’s inflows. PrivatBank sets the credit limit «Pidpryiemnytskyi» individually, at 10% of annual income according to financial statements. FUIB for the online loan requests statements from accounts in other banks for the last 12 months, which helps to obtain a larger limit.
Tax reporting
Declarations of the single tax payer confirm official income and for new bank customers are often the main document. If account turnover is high but the declaration shows significantly less, the bank will base its decision on the lower figure.
Credit history
The bank checks the entrepreneur’s credit history as a natural person, since legally an individual entrepreneur and the person are the same individual. Delinquencies on consumer loans, credit cards or instalment plans reduce the chances of approval for a business loan. The minimum operating period is not specified on most product pages, but for example the credit line at PrivatBank states an operating period of at least 12 months.
Nominal and real rate: how to calculate
One‑off commissions
A one‑off fee on issuance is withheld immediately, so the entrepreneur effectively receives less money than they will repay with interest. A 1-1.5% fee on a 12‑month loan adds roughly 2-3 percentage points per annum to the real cost.
Monthly commission instead of interest
Some banks set a token interest rate, while the main income comes from a monthly commission on the initial loan amount. Such a commission does not decrease as the debt is repaid. Because of this, a commission of 1.6-2% per month on the initial amount is roughly equivalent to a nominal rate of about 36-45% per annum, and including a one‑off fee the real rate exceeds 42-55%.
Formula for the real annual rate
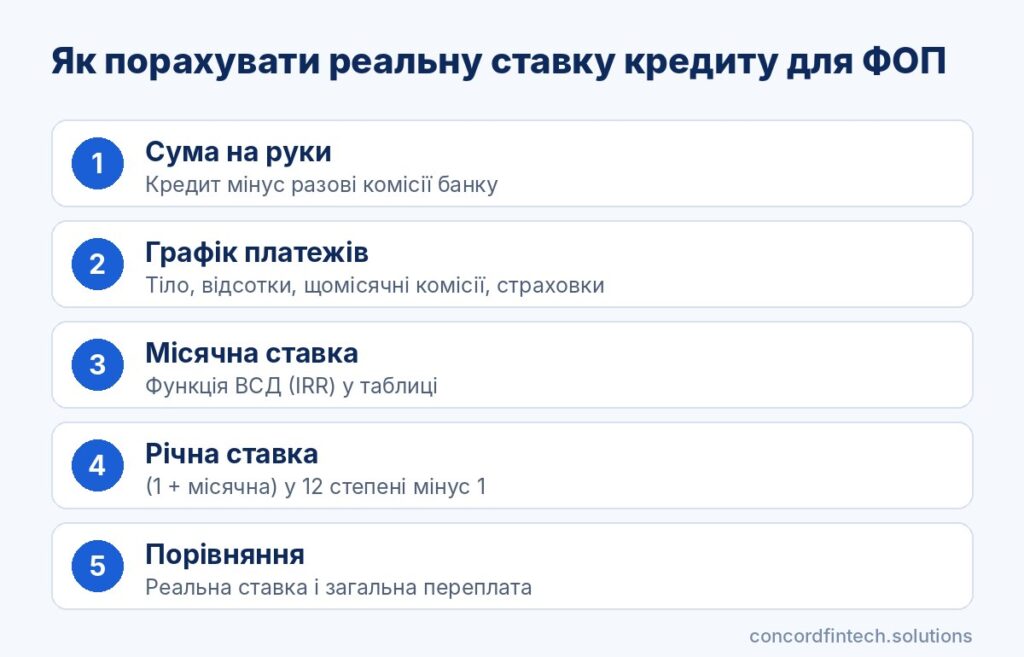
The Law “On Consumer Lending” requires showing the real annual percentage rate only for consumer loans, and loans for entrepreneurial activity do not fall under this law. So the easiest way to calculate the real rate for a business loan is to do it yourself in Excel or Google Sheets using the following algorithm:
- Write down the amount you actually receive to your account, i.e. the loan minus one‑off fees.
- Create a schedule of all bank payments by month: principal, interest, monthly commissions, insurance.
- Compute the internal rate of return of this cash flow (the IRR function); this will be the real monthly rate.
- Convert it to an annual rate: add one to the monthly rate, raise to the 12th power and subtract one.
As a rule of thumb: a rate of 3% per month on the outstanding balance gives about 42.6% per annum with compounding, and 2.9% per month gives about 40.9% per annum.
Comparison of banks’ offers
State banks
The largest state bank for sole proprietors, PrivatBank, offers entrepreneurs an unsecured credit limit «Pidpryiemnytskyi» on a business card at 36% per annum with no monthly commission. The limit is provided for 12 months with automatic renewal; the minimum monthly payment is 7% of the outstanding balance at month end. Transfers to other accounts and cash withdrawals cost 3%, card payments are free.
Commercial banks
Raiffeisen Bank offers sole proprietors and legal entities an overdraft from 30,000 hryvnia at 18.9% per annum, with no annual commission and continuous use for up to 180 days. The size of the limit depends on the customer’s turnover and financial condition. It is difficult to get a large limit without a history of turnover in the bank.
Online loans for FOP
FUIB’s online loan «vseBIZNES» is arranged remotely with documents from Diia. The bank’s website lists two tariffs: with a rate of 2.7-2.9% per month on the outstanding balance with no commissions, and with a one‑off commission of 1-1.5% plus a monthly commission of 1.6-2% of the initial amount. In the bank’s calculator for 700,000 hryvnia over 24 months at 2.9% per month the monthly payment is 40,898.28 hryvnia and the total cost of the loan is 981,558.72 hryvnia.
The comparison table below contains terms published on banks’ websites as of mid‑October 2026. The column for the real rate was calculated by us for full use of the sum for a year and is indicative.
| Bank | Product | Amount | Term | Nominal rate | Commissions | Real rate (estimate) |
|---|---|---|---|---|---|---|
| PrivatBank | Credit limit «Pidpryiemnytskyi» | up to 500,000 hryvnia (10% of annual income) | 12 months, automatic renewal | 36% per annum, grace period up to 55 days | 0% monthly; 3% for transfers and cash | about 42.6% without transfers |
| FUIB | «vseBIZNES», tariff without commissions | 50,000 - 3,000,000 hryvnia | 12-36 months | 2.7-2.9% per month (32.4-34.8% per annum) | 0% | 37.7-40.9% |
| FUIB | «vseBIZNES», tariff with commissions | 50,000 - 3,000,000 hryvnia | 12-36 months | token | 1-1.5% one‑off; 1.6-2% per month of the initial amount | 42-55% (for 12 months) |
| Raiffeisen Bank | Overdraft | from 30,000 hryvnia, depending on turnover | up to 36 months, “minus” up to 180 days | 18.9% per annum | 0% annual | about 20.6% |
| Raiffeisen Bank | Business card «100 days» | 10,000-500,000 hryvnia | grace period up to 100 days | 3% per month after the grace period | 3% for cash and transfers; 1% for overdue (min. 50 hryvnia) | about 42.6% outside the grace period |
| Participating banks | «5-7-9%», working capital | for FOP up to 3,000,000 hryvnia | under bank conditions | 15% per annum (7% in high military risk zones) | one‑off commission depends on the bank | about 17-18% with a 1% commission |
Examples of overpayment calculations
Loan of 200,000 hryvnia for 12 months
Take a hypothetical loan of 200,000 hryvnia for one year at 2.9% per month on the outstanding balance with equal monthly payments and no commissions. The monthly payment would be about 19,973 hryvnia and the total overpayment for the year approximately 39,672 hryvnia, or 19.8% of the loan principal. The real annual rate here equals about 40.9%.
Now compare with a hypothetical loan for the same amount with a one‑off commission of 1.5% and a monthly commission of 2% of the initial amount with a token interest rate. The entrepreneur would pay 16,667 hryvnia of principal per month plus 4,000 hryvnia commission, i.e. 20,667 hryvnia. The total overpayment including the one‑off fee of 3,000 hryvnia would be 51,000 hryvnia, and the real annual rate would reach about 55%.
Overdraft of 100,000 hryvnia
An overdraft is advantageous when money is needed for a few weeks, for example to buy stock before a season. If you use 100,000 hryvnia at 18.9% per annum for 30 days, interest will be about 1,553 hryvnia, and for 90 days about 4,660 hryvnia.
With a credit limit on a card the calculation is different. If you pay for goods with the card and repay within the grace period, there will be no overpayment at all. However, a transfer of 100,000 hryvnia to a supplier’s account will cost 3,000 hryvnia commission immediately, and after the grace period interest of about 3,000 hryvnia will be added for each month of using the full amount.
Comparison with “5-7-9”
Under the programme “Affordable loans 5-7-9%” the rate for working capital is 15% per annum, and 7% for high military risk zones. A loan of 200,000 hryvnia for 12 months at 15% with equal payments produces an overpayment of about 16,620 hryvnia, and with a one‑off commission of 1% about 18,620 hryvnia. This is 2-3 times cheaper than unsecured commercial products, but under the preferential programme the bank more often requires collateral or a guarantee and takes longer to process the application.
Risks of an unsecured loan for FOP
Liability with all assets
The absence of collateral does not mean the bank has nothing to seize. According to Article 52 of the Civil Code, an FOP is liable for obligations related to entrepreneurial activity with all their property, except that which cannot be subject to enforcement by law. Closing the FOP does not cancel the debt: the loan obligation remains with the person as a natural person.
Penalties for overdue payments
Business loans are not subject to the penalty limits provided by the Law “On Consumer Lending”, so the size of penalties and fines is determined by the contract. For example, under the terms of Raiffeisen Bank’s business card, missing the minimum payment costs 1% of the overdue amount, but not less than 50 hryvnia, and voids the grace period.
Spouse’s guarantee
If an FOP is married, the bank may request the consent or guarantee of the spouse, especially for larger sums. According to part 2 of Article 52 of the Civil Code the entrepreneur in marriage is liable with personal property and their share in the joint property of the spouses. A guarantee makes the other spouse a joint debtor.
How to improve approval chances and compare offers
Turnover through one bank
A bank is more willing to lend to clients whose funds regularly pass through its accounts. If revenue is spread across several banks, the limit at each will be smaller.
Timely tax payments and a clean credit history
Tax debt and delinquencies on personal loans are among the most common reasons for refusal. Before applying it is useful to take a few simple steps:
- check in the e‑cabinet that there are no debts for the single tax and the single social contribution (ЄСВ);
- submit all declarations on time and ensure that declared income corresponds to turnover;
- order a credit history from a credit bureau and clear small delinquencies;
- prepare statements from accounts in other banks for 6-12 months.
How to compare offers before signing
Compare not the advertised rates but the total amount you will return to the bank and the real annual rate calculated by the algorithm above. Separately check commissions for transfers and cash, early repayment conditions and the size of penalties. The article is for information purposes only and is not personal financial advice.
Frequently asked questions
Can an FOP get a loan without collateral?
Yes, as of mid‑October 2026 several large banks issue unsecured loans, overdrafts and credit limits to FOP. Amounts are usually from 10,000 to 3,000,000 hryvnia and depend on turnover and the entrepreneur’s financial statements.
What is the real rate of a loan for FOP?
For unsecured commercial products the real rate in our calculations usually ranges from 20% per annum for overdrafts to 40-55% for loans with monthly commissions. The exact figure for a specific offer can be obtained by calculating all payments and commissions according to the schedule.
What documents are required for an FOP loan?
Usually a passport, tax identification number, single tax payer declarations and account statements for the last 6-12 months are required. For online loans documents are often submitted via Diia.
Which is better: an overdraft or a loan?
An overdraft is more convenient for short‑term cash gaps because interest is charged only for the days of actual use. A loan with a repayment schedule is more appropriate for purchasing equipment or other expenses that pay off over several months or years.