
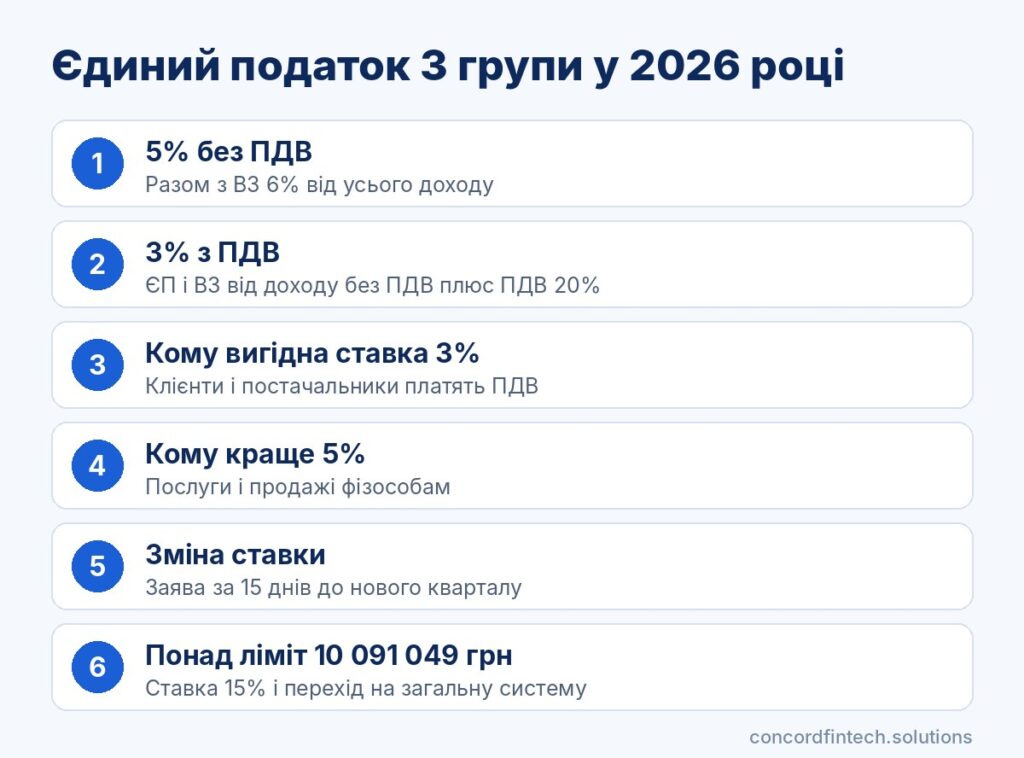
Individual entrepreneurs (FOP) on group 3 in 2026 pay the single tax at one of two rates: 5% of income without registering as a payer of value-added tax (VAT) or 3% of income together with VAT 20%. Additionally, a military levy (MV) of 1% is withheld from all income, and the single social contribution (SSC) for themselves is paid separately each quarter.
The 3% rate is not advantageous for everyone, because value-added tax is added to it and separate reporting is required. Below are calculations, payment deadlines and the conditions under which 3% is actually cheaper.
Who can operate on group 3 in 2026
Income limit 10 091 049 UAH
The maximum annual income for group 3 is 1 167 minimum wages set on 1 January. In 2026 the minimum wage is 8 647 UAH, so the limit is 10 091 049 UAH. Income is counted cumulatively from the start of the year.
No restriction on the number of employees
Unlike groups 1 and 2, a group-3 entrepreneur may hire any number of employees. There are no restrictions on the circle of clients either, so you can work with both individuals and legal entities on any tax system.
Prohibited types of activity
The simplified system is unavailable for certain types of activity listed in the Tax Code. These include gambling, currency exchange, mineral extraction and production of excisable goods. If a FOP receives income from such activity, that income is taxed at 15%, and the entrepreneur risks losing the right to the simplified system.
5% rate without VAT: how to calculate the tax
What counts as income for 5%
For a FOP the cash method applies, meaning income arises at the moment money is received to the account or cash register. Advance payments and prepayments are included in the income of the quarter when they are received, even if the goods have not yet been shipped. If the buyer is refunded in the same period, the amounts are not included in income; a refund in another quarter reduces income in the period of the actual refund.
Loans and personal funds deposited by the entrepreneur into their account are not income. The 5% rate applies to all income without deducting expenses.
Quarterly calculation example
Suppose a FOP on the 5% rate received 600 000 UAH for Q3, and for half a year their income was 1 000 000 UAH. The calculation is performed in the following order:
- Determine income for the quarter from the accounting book and bank statements: 600 000 UAH.
- Calculate the single tax: 600 000 × 5% = 30 000 UAH.
- Calculate the military levy: 600 000 × 1% = 6 000 UAH.
- Report income cumulatively in the declaration for 9 months, i.e. 1 600 000 UAH.
- Pay 30 000 UAH single tax and 6 000 UAH MV as separate payments by 19 November 2026.
Total burden for the quarter is 36 000 UAH, or 6% of income. To this is added the SSC for oneself.
Foreign-currency proceeds
Income in foreign currency is converted into hryvnia at the official exchange rate of the National Bank of Ukraine (NBU) on the date it is credited to the account. According to clarifications from the State Tax Service (DPS), positive exchange differences from subsequent sale of currency are not considered income for a single-tax payer.
3% rate with VAT: how it works and who benefits
Registration as a VAT payer on group 3
The 3% rate may be chosen only by a FOP who is registered as a payer of value-added tax (VAT). For a single-tax payer on the 5% rate registration is not mandatory even with income over 1 million UAH, so this decision is always voluntary. The VAT registration application is submitted together with the application to change the rate.
Tax credit and registration of tax invoices
A VAT payer charges 20% on their sales and deducts input VAT from purchases from suppliers who also operate with VAT. A tax invoice must be registered for each operation in the Unified Register and a separate VAT declaration filed; penalties apply for missed registration deadlines of invoices.
Calculation of the burden with examples
The single tax 3% and the military levy 1% are calculated on income excluding VAT. If a FOP received 360 000 UAH, of which 60 000 UAH is VAT, the taxable base will be 300 000 UAH: the single tax equals 9 000 UAH and the MV 3 000 UAH. VAT payable is determined separately as the difference between tax liabilities and tax credit.
Military levy and SSC on group 3
MV 1% of income within the declaration
For group 3 the military levy is 1% of the actually received income regardless of which single-tax rate was chosen. It is shown in the same declaration and is paid in the same deadlines as the single tax, but as a separate payment.
Minimum SSC per quarter
The single social contribution (SSC) for oneself is 22% of the minimum wage, i.e. 1 902,34 UAH per month or 5 707,02 UAH per quarter in 2026. The contribution is paid no later than the 19th day of the month following the quarter and does not depend on income. It must be paid even with no receipts, unless the FOP has an exemption as an age pensioner or a person with a disability.
Voluntary top-up of SSC
An entrepreneur may pay SSC on a larger base to increase the pensionable earnings, but this does not reduce the single tax. The maximum base in 2026 is 15 minimum wages, i.e. 129 705 UAH, and the maximum contribution is 28 535,10 UAH per month.
Declaration and payment deadlines for group 3
Quarterly declaration within 40 days
The declaration is submitted within 40 calendar days after the end of the quarter. If the last day falls on a weekend, the deadline shifts to the next working day.
Payment of single tax and MV within 50 days
The tax and levy must be paid within 10 days after the final deadline for submitting the declaration, i.e. effectively within 50 days after the quarter. Deadlines for 2026 for group 3 are shown in the table.
| Period | Submit declaration by | Pay single tax and MV by |
|---|---|---|
| IV quarter 2025 | 9 February 2026 | 19 February 2026 |
| I quarter 2026 | 11 May 2026 | 20 May 2026 |
| II quarter 2026 | 10 August 2026 | 19 August 2026 |
| III quarter 2026 | 9 November 2026 | 19 November 2026 |
| IV quarter 2026 | 9 February 2027 | 19 February 2027 |
Annual declaration via the IV quarter report
There is no separate annual declaration for group 3; its role is performed by the IV quarter report with income for the whole year. Annex 1 with monthly SSC amounts is attached to that report. For 2026 the declaration must be submitted by 9 February 2027, and taxes paid by 19 February 2027.
When 3% with VAT is actually cheaper than 5%
Comparison formula
At the 5% rate together with MV the entrepreneur pays 6% of income. At the 3% rate they pay 4% of income excluding VAT plus the difference between VAT on sales and input VAT. If clients are VAT payers and agree to pay the price plus 20%, that tax is neutral for them, and the FOP effectively saves 2% of income and gains a tax credit.
A different situation arises when the price for the buyer is fixed and VAT must be carved out of it. Then 3% is advantageous only if input VAT exceeds about 14% of revenue, i.e. purchases with VAT make up more than 84% of the sales price.
Scenario with high input costs
The table compares three cases with income of 300 000 UAH for the quarter excluding VAT. In the wholesale example the FOP buys goods for 240 000 UAH, of which 40 000 UAH is VAT.
| Scenario | Quarter income | Input VAT | Taxes at 5% | Taxes at 3%+VAT | Conclusion |
|---|---|---|---|---|---|
| IT services to VAT-paying companies | 300 000 UAH + 60 000 UAH VAT | 2 000 UAH | 18 000 UAH | 12 000 UAH single tax and MV + 58 000 UAH VAT | 3% is cheaper by 8 000 UAH |
| Wholesale trade with VAT payers | 300 000 UAH + 60 000 UAH VAT | 40 000 UAH | 18 000 UAH | 12 000 UAH single tax and MV + 20 000 UAH VAT | 3% is cheaper by 46 000 UAH |
| Retail and services to individuals | 300 000 UAH, VAT included within the price | 5 000 UAH | 18 000 UAH | 10 000 UAH single tax and MV + 45 000 UAH VAT | 5% is cheaper by 37 000 UAH |
In the first two rows the VAT is paid by the client on top of the price and returned via the tax credit. In the wholesale example the entrepreneur retains 88 000 UAH on 3% versus 42 000 UAH on 5%.
Scenario with final consumers (individuals)
An individual cannot use a tax credit, so raising the price by 20% is usually impossible. In the third row, from the same 300 000 UAH VAT is 50 000 UAH, and the burden rises from 18 000 to 55 000 UAH per quarter. For services to the public the 3% rate is almost always more expensive, and it is worth considering mainly for businesses with the following features:
- most clients are VAT payers and require a tax invoice;
- a significant share of costs is for goods or services from VAT payers;
- margins are low and turnover is large, as in wholesale trade or construction;
- there is an accountant or software to register invoices and file VAT reports.
Switching between 5% and 3% rates and changing groups
Application to change the rate
You can change the rate only from the start of the next quarter. The application must be submitted no later than 15 calendar days before its start, so to switch from 1 January 2027 it must be submitted in the first half of December 2026. The application can be conveniently submitted via the Electronic Cabinet.
VAT registration and cancellation
To switch to 3% you must submit the VAT registration application together with the application to change the rate within the same deadline. If VAT registration is cancelled, the FOP is obliged to move to the 5% rate or opt out of the simplified system from the next quarter.
Exceeding the group-3 limit
Income above 10 091 049 UAH is taxed at 15%, and from the next quarter the entrepreneur must switch to the general taxation system. The same 15% rate applies to income in non-cash form and to income from activities prohibited for the simplified system. The military levy 1% is also charged in these cases.
As of October 2026 there is discussion about mandatory VAT registration for single-tax payers with large turnover, linked to requirements of the International Monetary Fund (IMF). No law has yet been adopted, and implementation, according to reports, has been postponed at least until 2028.
Frequently asked questions
Does a group-3 FOP pay single tax if there was no income?
No, the single tax and military levy for group 3 are calculated only on actual income, so for a zero quarter they equal zero. However, the declaration must be submitted, and the minimum SSC of 5 707,02 UAH per quarter is paid regardless of income.
When to pay the single tax for Q3 2026?
The single tax and military levy for Q3 must be paid by 19 November 2026. The 9-month declaration is submitted by 9 November, and SSC for July–September had to be paid no later than 19 October.
Can a group-3 FOP have employees without limits?
Yes, the number of hired employees for group 3 is not limited. For each employee the FOP pays SSC, withholds personal income tax (PIT) and the military levy, and reports as an employer.
How to switch from 5% to 3% with VAT?
You need to submit an application to change the single-tax rate and the VAT registration application no later than 15 calendar days before the start of the new quarter. The new rate takes effect from the first day of the quarter, and from that day the FOP charges VAT on sales.
