
A few months ago a deposit at 14% looked like a good find. Now some banks are offering noticeably more: in October 2026 rates on certain hryvnia deposits reach up to 17.5% per annum. Interestingly, the most generous offers often come not from market giants but from banks whose names are not familiar to everyone.
There is a real battle for depositors. Some banks raise rates on short deposits, others try to lure those ready to leave money for six months or longer. On paper a few percentage points look small, but on UAH 100,000–300,000 they already turn into real money.
Where is it most profitable to keep hryvnia now, how much remains after taxes, and is it risky to put money in a small bank?
Why smaller banks suddenly became more generous
A fight for every client
Big banks do not need to hunt for customers. Millions of people already receive salaries with them, pay with their cards and keep their savings there. Smaller institutions have to fight for every depositor.
The simplest way is to offer a higher rate. Someone used to seeing 13–14% is unlikely to pass up an offer at 17%. Of course, rates are influenced by decisions of the National Bank of Ukraine (NBU) and market conditions, but each bank decides for itself how much to pay depositors.
Who raised rates in September
At the end of September Yuneks Bank raised the rate on a three‑month UAH deposit to 17.2%. Kredytvest Bank went further and added 1.5 percentage points at once: six‑month deposits now pay 17%, annual — 16.75%.
And these are not isolated cases. Several other banks also raised rates to attract money for certain terms.
Highest rates in October 2026
Who pays the most
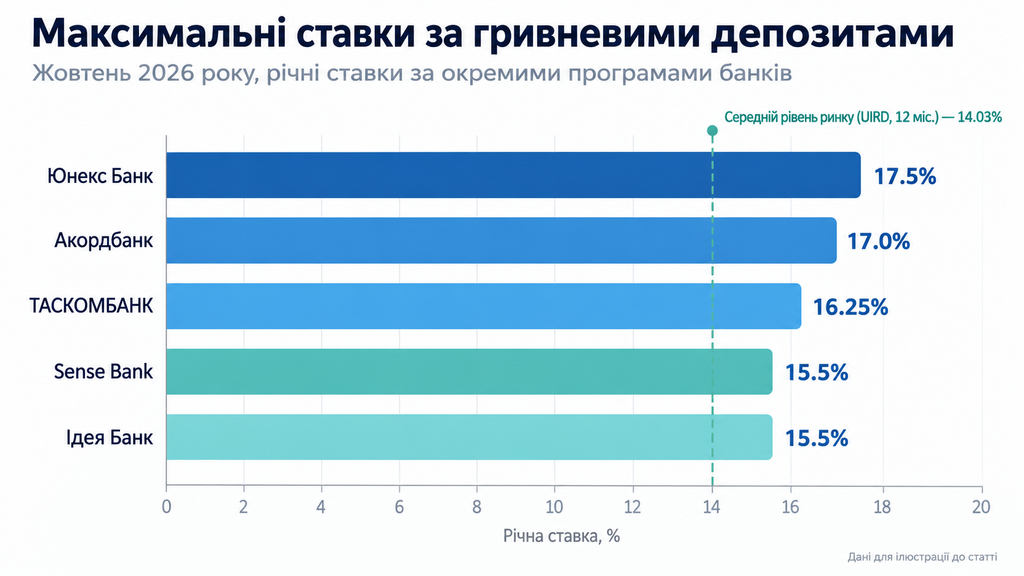
While some banks stick around 13–14%, others have raised the bar to 16–17.5%. Here are the most lucrative offers in mid‑October:
| Bank | Maximum rate |
|---|---|
| Yunex Bank | up to 17.5% |
| Akordbank | up to 17% |
| TASKOMBANK | up to 16.25% |
| Sense Bank | up to 15.5% |
| Idea Bank | up to 15.5% |
But these are maxima for specific programmes. Placing money for an arbitrary term does not necessarily mean you will get that exact figure.
Yuneks and Akord: 17–17.5%
At Yuneks Bank the most interesting programme is “YUNEKS Maximum”, up to 17.5% per annum. The minimum deposit is 5,000 UAH.
Akordbank under the “Maximum” programme offers up to 17%, and the starting amount is also 5,000 UAH. Both offers are worth comparing, but first find out for which term the maximum rate applies, when interest is paid and whether you can withdraw money early. And don’t forget about auto‑renewal: after three months the bank may offer a completely different rate.
The average rate is considerably lower than the advertised 17.5%
What the UIRD shows
Because of the high rates at some banks it may seem that the whole market has suddenly become more expensive. That is not the case.
The Ukrainian Index of Retail Deposit Rates (UIRD) at the start of October showed 13.82% for three months, 14.21% for six months and 14.03% for a year. Nine‑month deposits yielded even more — 14.54%. So putting money for a year is not always more profitable than for nine months.
A difference of a few percentage points
Between average rates and the most generous offers there are a few percentage points. On UAH 10,000 that is trivial.
But when an account holds serious savings these points turn into thousands of hryvnia. Let’s calculate.
How much UAH 100,000 will bring in a year
Taxes first
Take UAH 100,000 and two banks: one pays 14%, the other 17.5%. How significant is the difference?
First taxes. Interest on deposits is subject to 18% personal income tax (PIT) and a 5% military levy, together 23%. Here is what remains net after a year:
| Rate | Net income for the year |
|---|---|
| 13% | 10,010 hryvnia |
| 14% | 10,780 hryvnia |
| 15% | 11,550 hryvnia |
| 16% | 12,320 hryvnia |
| 17% | 13,090 hryvnia |
| 17.5% | 13,475 hryvnia |
Calculation for an annual deposit of UAH 100,000, without capitalization and without fees.
The difference — almost UAH 2,700
At 14% you will earn 10,780 hryvnia, at 17.5% — 13,475. The difference is 2,695 hryvnia, and on UAH 300,000 — already 8,085.
Just remember: 17.5% may not apply to an annual deposit. Before signing check the rate for the term you need.
Three months or a year: how long to place money for
Short deposit
Here everything is decided by one question: when might you need the money? A high rate looks good in the app, but if in a month you suddenly need to repair a car or pay for treatment, a locked deposit will be a problem.
A three‑month deposit allows you to withdraw money quickly. UAH 100,000 at 17% for three months will bring roughly 3,273 hryvnia net. But if during that time the bank cuts rates, you may not be able to redeposit at the same 17%.
Long deposit
An annual deposit locks in the percentage for longer. If a bank promised 16.5%, usually that rate will apply until the end of the contract, even if the market falls.
The downside is that early withdrawal is often not allowed. So before signing honestly ask yourself whether you will need the money this year.
Is it safe to put money in a small bank?
Guarantees do not depend on the bank’s size
An unfamiliar bank name is alarming, especially when it pays a few percentage points more than the large ones. But deposit protection does not depend on the size of the bank.
Ukraine has a system of deposit insurance for individuals. During martial law and for three months afterwards guaranteed deposits are returned in full together with interest, except for cases provided by law. After that the guaranteed amount is at least 600,000 hryvnia per depositor in one bank.
What to check
Before opening a deposit, make sure the bank has a licence and that it participates in the Deposit Guarantee Fund. Also read the terms of the specific programme carefully.
It will take a few minutes. The peace of mind it brings will last much longer.
When 16% is better than 17%
Flexibility has a price
Imagine: one bank gives 17% but you cannot withdraw early. Another pays 16% but is more flexible with your money. On UAH 100,000 the difference in net income for a year is only 770 hryvnia.
But the difference in access to your own money can be significant. Sometimes those 770 hryvnia are the price of freedom.
Interest payments and capitalization
One more detail that is often forgotten. Some banks pay interest monthly, others at the end of the term. With capitalization net income is added to the deposit and subsequent interest is calculated on a larger sum.
Therefore deposits should be compared by real profit after taxes, not by the large figure in the advertisement.
What to check before opening a deposit
Key terms of the contract
To avoid unpleasant surprises after signing, find out:
- whether the stated rate applies for the whole term;
- whether the deposit can be withdrawn early;
- when interest is paid and whether there is capitalization;
- whether there are fees for transfers or withdrawals;
- how and at what rate the deposit is automatically renewed.
Don’t forget about inflation
17% per annum does not mean your money will gain 17% in real terms. After taxes net yield is 13.09%, and the real result depends on how prices change.
In October 2026 the highest hryvnia rates reach 17.5%, while the market average is around 14%. A few extra percentage points can bring thousands of hryvnia, but the final amount depends on the contract terms, taxes and the term for which you place your money.