
The pension paid by the Pension Fund of Ukraine (PFU) in 2026 is not taxable: since 23 May 2020 personal income tax (PIT) is not withheld from it regardless of amount, and the military levy (VZ) is also not charged on PFU pensions. This applies to regular old‑age pensions, length‑of‑service pensions and so‑called special pensions.
At the same time, pensioners are not entirely exempt from taxes. Salary, rental income, deposit interest, part of payments from a non‑state pension fund (NPF) and pensions from abroad each have their own rules. Below we go through each type of income, the concessions available to pensioners and common myths.
Pension from the PFU: is it taxed?
Absence of PIT
Pensions from the Pension Fund of Ukraine (PFU) and the budget, including indexation, supplements and allowances, are not included in taxable income under subparagraph 165.1.1 of the Tax Code of Ukraine (TCU) (link). The PFU calculates the pension and transfers it to the card or through Ukrposhta in full, without any withholdings in favour of the budget. The pension amount does not matter: the maximum payment of 25 950 UAH is also paid without tax.
Absence of the military levy
The military levy (VZ) is calculated on the same base as PIT. Since a PFU pension is not included in taxable income, the 5% rate is not applied to it. The levy is likewise not withheld from indexation, supplements and pension top‑ups.
Background: Law No. 466‑IX
Previously subparagraph 164.2.19 of the TCU allowed part of large pensions to be taxed: from 2016 an 18% tax was withheld on the amount exceeding ten living‑wage minimums for incapacitated persons. By decision of the Constitutional Court No. 1‑r/2018 of 27 February 2018 such taxation was declared unconstitutional. The provision was finally removed by Law No. 466‑IX, and from 23 May 2020 no tax is levied on PFU pensions at all.
Other pensioner income: what is taxable
Salary of a working pensioner
Reaching pension age does not give salary privileges. The employer withholds 18% personal income tax (PIT) and 5% military levy (VZ), so the employee receives 77% of the gross amount net. The employer pays the single social contribution (SSC) of 22% at its own expense; the pensioner does not pay SSC from salary, but these contributions entitle them to a pension recalculation for additional service.
Rent and sale of real estate
Income from letting an apartment is taxed at 18% PIT and 5% VZ. If the tenant is a company or an individual entrepreneur (FOP), the tax is withheld by them; if the tenant is a private individual, the owner pays the tax themselves quarterly within 40 days after the end of the quarter and files an annual declaration. Law No. 4903‑IX on a 5% rate for rental had not been signed as of mid‑October 2026, so until it takes effect the 18% rate applies.
The first sale in a year of housing that has been owned for more than three years or was inherited is not taxable. A second sale in a year or sale of an object owned for less than three years is subject to 5% PIT and 5% VZ, which are paid before the notarial certification of the contract.
Deposits and insurance payments
Interest on deposits and on card balances is taxed at a total of 23%, and the bank withholds the tax itself. Only income from domestic government bonds (OVDP) remains tax‑free. An insurance payout from a resident insurer on survival to the term specified in a life insurance contract is not included in taxable income, but in case of early contract termination taxation depends on the terms and should be clarified with the insurer.
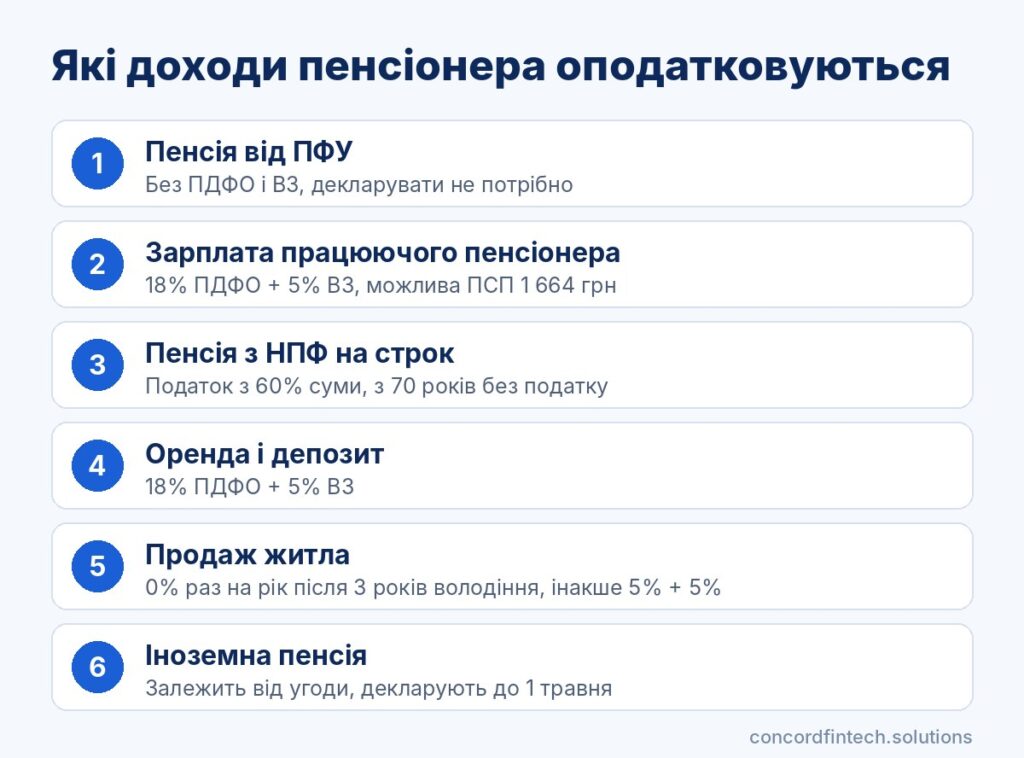
| Type of income | PIT | VZ | Note |
|---|---|---|---|
| Pension from the PFU | 0% | 0% | Since 23.05.2020 regardless of amount |
| Salary | 18% | 5% | Withheld by the employer, tax‑free personal allowance (PSP) may apply |
| Pension from an NPF for a fixed term | 18% on 60% of the amount | 5% on 60% of the amount | Tax‑free from age 70 or for Group I disability |
| Rental of housing | 18% | 5% | Paid by tenant‑agent or by the owner personally |
| Sale of housing | 0% or 5% | 0% or 5% | 0% on the first sale in a year after 3 years of ownership |
| Deposit | 18% | 5% | Withheld by the bank |
| Foreign pension | 18% or 0% | 5% or 0% | Depends on a double taxation avoidance agreement |
Taxation of payments from non‑state pension funds
General rules
Payments from a non‑state pension fund (NPF) are not PFU pensions, so the exemption under subparagraph 165.1.1 does not apply to them. For a pension paid for a fixed term paragraph 170.8 of the TCU exempts 40% of each payment from tax, while the remaining 60% is taxed at 18% PIT and 5% VZ. The fund administrator withholds and pays the tax, so it is not necessary to file a declaration on such payments.
Concessions
Payments are fully tax‑exempt for participants aged 70 or over, persons with Group I disability and children under 18. First‑ and second‑degree heirs receive the deceased participant’s funds tax‑free, while other heirs pay 5%. Lump‑sum payments have their own rules, so it is worth clarifying the calculation with the administrator before applying.
Example
A 66‑year‑old pensioner receives 5 000 UAH per month from an NPF. The taxable base is 60%, i.e. 3 000 UAH, from which 540 UAH PIT and 150 UAH VZ are withheld, and 4 310 UAH is credited to the account. After turning 70 the same 5 000 UAH will be received in full.
Pensions from abroad
Declaration
A Ukrainian tax resident is obliged to declare foreign income, and a pension is no exception. A pension received in 2026 must be reported in the declaration of assets and income, which is filed by 1 May 2027 (we recommend by 30 April), and tax is paid by 31 July 2027. If a person permanently lives abroad and has lost Ukrainian tax residency, a foreign pension is not declared in Ukraine.
Avoiding double taxation
Under subparagraph “e” of 165.1.1 of the TCU a foreign pension is not taxed in Ukraine if an international agreement ratified by the Verkhovna Rada provides that it is not taxable or is taxable only in the country of payment. If the agreement leaves taxing rights to Ukraine, the pension is subject to 18% PIT and 5% VZ. Tax paid abroad can be credited against PIT on the basis of a certificate from the foreign tax authority, but double taxation agreements do not cover the military levy.
Currency
A pension in foreign currency is converted into hryvnia at the official exchange rate of the National Bank of Ukraine (NBU) on the date it is accrued. Therefore, for the declaration it is advisable to keep statements with dates and amounts of each payment. If payments arrived monthly, each is converted at the exchange rate of its day.
Concessions for pensioners: PSP, tax deduction and property taxes
Tax social allowance
A working pensioner is entitled to the tax social allowance (PSP) on the same terms as other employees, because receiving a pension does not prevent this. In 2026 the allowance is 1 664 UAH if the salary does not exceed 4 660 UAH, and it applies at only one employer on the basis of a written application. PSP is not applied to the pension itself, since the pension is already untaxed.
Tax deduction
A tax deduction refunds part of the PIT paid from salary, for example for education, contributions to an NPF or life insurance. A pensioner who only receives a pension cannot benefit from the deduction because they did not pay PIT. Only 18% of PIT is refundable; the military levy is not refundable, and an application for 2026 can be submitted until 31 December 2027.
Property tax and land tax
There is no nationwide special property tax concession for pensioners, but there is the general reduction of the taxable base by 60 sq. m for an apartment and 120 sq. m for a house. Local councils can additionally exempt low‑income pensioners, so the decision should be checked on the community’s website. Pensioners by age are exempt from land tax under Article 281 of the TCU within norms: up to 0.10 ha for a house in a city, 0.25 ha in a village, 0.12 ha for gardening plots and 2 ha for a personal peasant farm.
Myths about pension taxation
Tax on pensions above three minimum wages
This belief dates back to 2015, when tax was indeed levied on part of a pension above three minimum wages. Later the threshold was changed, and the provision of subparagraph 164.2.19 was completely excluded in 2020. The most common outdated notions are as follows:
- large pensions are subject to 18% PIT;
- military levy is withheld from pensions;
- pension must be declared annually;
- a working pensioner loses the right to the PSP;
- military and special pensions are taxed separately.
Military levy on pensions
The increase of the VZ rate to 5% from 1 December 2024 did not affect pensions. The levy is withheld from salary, rent and deposits, but not from PFU payments. If a pensioner sees a withholding in their statement, it is most often a repayment of an overpaid pension or an enforcement proceeding, not a tax.
Tax on special pensions
Pensions for judges, prosecutors, civil servants and military personnel are also exempt from PIT and VZ. Their amount is limited only by the maximum set by pension legislation, but that is not a tax.
How to reclaim unlawfully withheld tax
Contact the PFU
If you see an unexplained withholding in your pension calculation, first submit an application to the territorial office of the PFU via the fund’s portal or service centre. The Fund is obliged to explain the basis and, if the withholding was erroneous, to refund the money.
Contact the State Tax Service
Overpaid tax, including from NPF or deposit payments, is refunded on application to the State Tax Service (STS) or via the annual declaration. The limitation period for refund is 1,095 days from the date of payment. Attach a certificate from the tax agent or a statement from the Electronic Cabinet confirming the withholding.
Court
If the PFU or STS refuse, the decision can be appealed to the administrative court within six months from the date the person became aware of the violation. The suit is filed at the claimant’s place of residence or at the defendant’s location. Before suing, it is worth collecting the authority’s written refusal, the pension calculation and bank statements.
Frequently asked questions
Do I need to declare my pension?
A PFU pension does not need to be declared because it is not taxable. A declaration is filed only when there are other incomes without a tax agent, for example rent from a private individual or a foreign pension.
Does a pensioner who is an individual entrepreneur pay tax?
A pensioner who is an individual entrepreneur (FOP) pays the single tax and the military levy on general grounds; there is no special concession. However, they are exempt from paying the single social contribution (SSC) for themselves if they receive a pension for age, disability or length of service.
Is a pension from Poland taxable?
The answer depends on the clause on pensions in the convention between Ukraine and Poland and on the type of pension. If the right to tax belongs to Ukraine, the resident declares the pension and pays 18% PIT with credit for Polish tax and 5% VZ, so it is worth obtaining individual advice from the State Tax Service (STS).