How it looks for someone living abroad
Imagine a Ukrainian who has been living abroad for some time and decides to sell an apartment in Ukraine. The first thought may be the price and finding a buyer. The second thought is often about taxes and what the consequences will be for the wallet.
Vadym Oksentyuk, CEO of the Centre for Unblocking value-added tax (VAT) draws attention to the fact that before calculating taxes you need to check your tax status. A mistake in your status can materially change the amount of tax and unpleasantly surprise the seller.
When a non-resident does not pay personal income tax (PIT) and the military levy
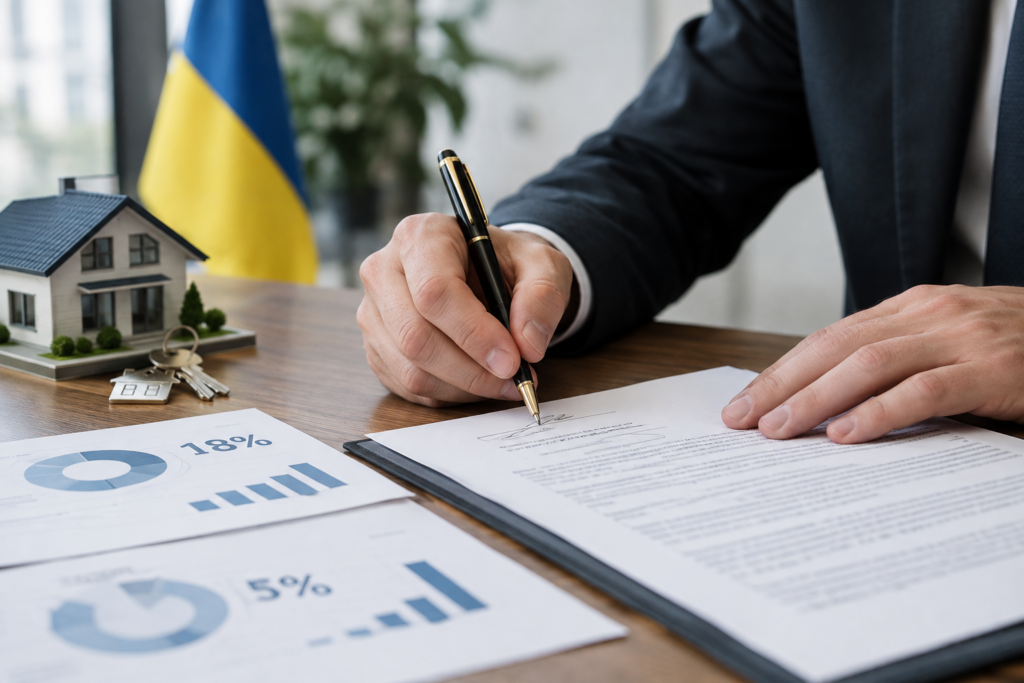
For an individual who is considered a non-resident, the standard tax rate on income from the sale of real estate is 18% personal income tax (PIT) and an additional 5% military levy. Together this gives a 23% tax burden if the exemption does not apply.
However, the Tax Code provides exceptions. Under para. 172.1, income from the first sale of residential property within a year is not taxed if the property was owned for more than three years. This rule applies to non-residents as well.
Separately, the State Tax Service (DPS) in its individual consultation of 24 September 2026 confirmed that a non-resident who, for the first time in a year, sells a residential building and had owned it for more than three years does not pay either PIT or the military levy. At the same time, the three-year condition does not apply to inherited property.
When the 23% rate applies
If the exemption under para. 172.1 does not apply, an individual non-resident is subject to 18% PIT plus a 5% military levy. In total this is 23% of the transaction income under the tax rules.
For comparison, a resident individual on a similar transaction may face a different PIT rate, which sometimes can be 5%. Therefore, for a seller who has lost resident status the difference in tax can be substantial. Taxation is also tied to the value of the transaction, taking into account rules on the valuation of real estate.
Why this is not a new rule
The provision on taxation of real estate sales by non-resident individuals has been in the Tax Code for a long time. The State Tax Service (DPS) referred to para. 172.9 in its explanations back in 2011–2012 and now repeats the same approaches.
In other words, the rules did not appear because of the start of the full-scale war. However, recently they have become more noticeable due to the large number of Ukrainians who have been living abroad for a long time and are selling property in Ukraine. It is also important to remember that holding another citizenship in itself does not make a person a tax non-resident. Tax residency rules are used to determine status, not just the passport.
What information is available about such transactions
There is no open official statistics that would show in detail the number of sales of Ukrainian real estate by non-resident individuals and the share of transactions taxed at the 18% rate. Civil servants do not publish such a breakdown in the public domain.
Instead, the State Tax Service (DPS) continues to consider individual enquiries and provide consultations. For example, in September 2026 the tax authority reviewed an enquiry from a non-resident regarding the sale of a share in a residential building. Therefore, the practical advice is to check your tax status before signing a sales contract to avoid unexpected liabilities.
What the seller should do before the deal
Before signing a contract or calculating net profit, a seller should determine whether they are a tax resident. This is the key question that affects the amount of tax and the possibility of using the exemption under para. 172.1.
If there are doubts, it is better to request an individual consultation from the State Tax Service (DPS) or consult a specialist who knows the nuances of the Ukrainian Tax Code. A mistake in interpreting status can change the final amount payable by tens of percentage points of the sale.