
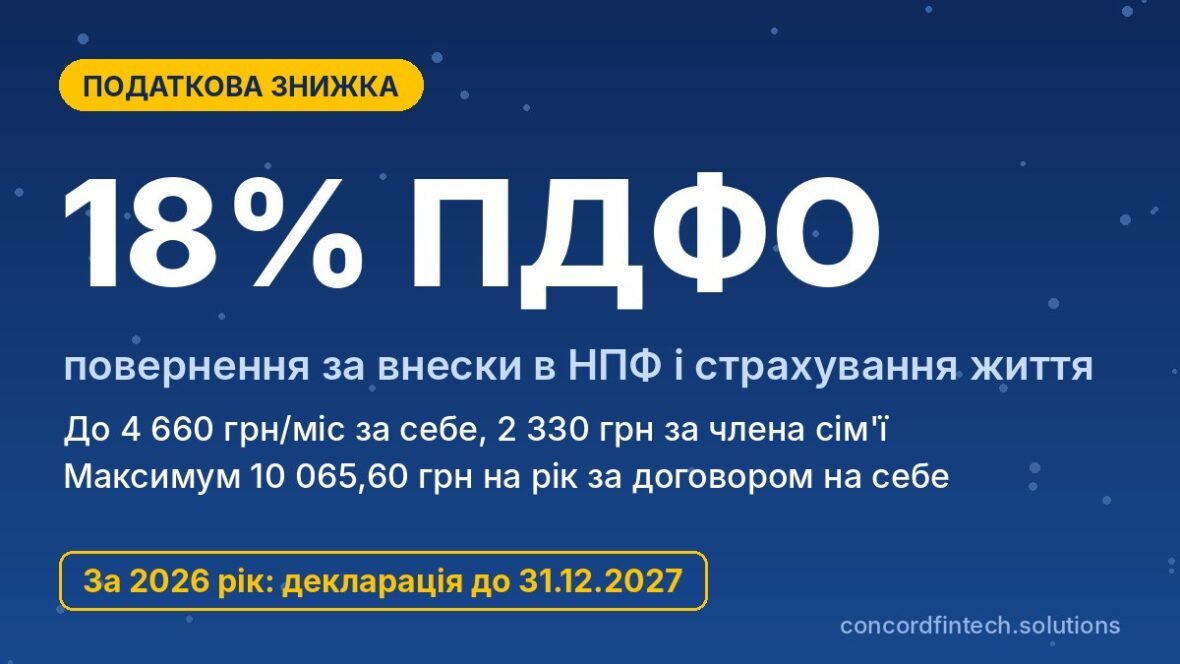
If you pay contributions under a long-term life insurance contract or a pension contract with a non-state pension fund (NPF), the state will refund 18% of those expenses from the personal income tax (PIT) withheld from your salary. For 2026 the limit is 4 660 UAH per month for a contract on your own behalf and 2 330 UAH for each insured first‑degree family member. The declaration with Appendix F3 for 2026 can be submitted from 1 January until 31 December 2027, and the right for 2025 remains available until 31 December 2026.
Below we explain which contracts qualify, how to calculate the amount and how to submit the declaration. We also separately explain the tax consequences of early termination of a contract.
Which contracts qualify for the deduction
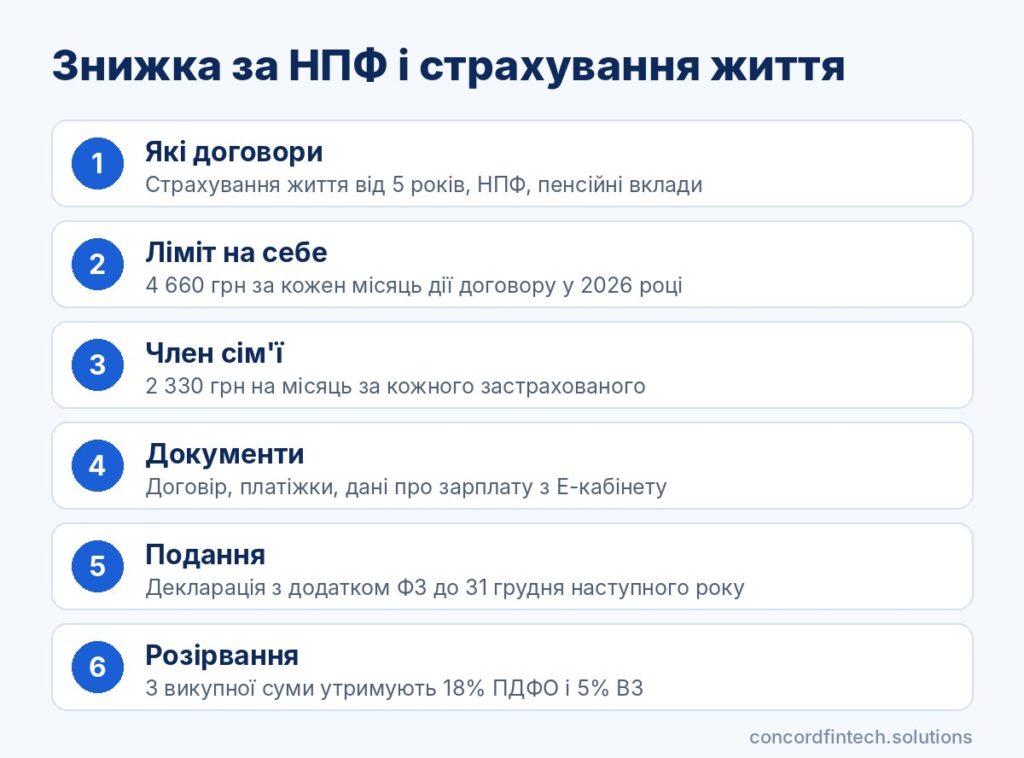
Long‑term life insurance
Subparagraph 166.3.5 of the Tax Code of Ukraine (TCU) allows insurance payments under a long‑term life insurance contract to be taken into account. A contract is considered long‑term if it runs for five years or more and does not provide for partial payouts during the first five years, except in cases of death, illness or disability (subparagraph 14.1.52 of the TCU). Annual policies, medical insurance or CASCO do not qualify for the deduction.
NPF, pension deposits and insurance within non‑state pension provision
The second group includes pension contributions under a contract with a non‑state pension fund (NPF) and insurance contracts within non‑state pension provision (NSPP). The law also mentions contributions to pension deposit accounts in banks and to bank‑managed funds. In practice, such bank products are rare.
Requirements for the insurer and the payer
The insurer or fund must be a resident of Ukraine with a licence, so a policy from a foreign company does not qualify for the deduction. The payer must pay from their own funds, and the insured person may be the payer or a first‑degree family member: spouse, children or parents. Contributions paid by the employer are not considered your expenses and are not included in the deduction.
Deduction limits for 2026
Monthly limit and full months of contract coverage
The limit equals 1.4 times the subsistence minimum for able‑bodied persons as of 1 January, rounded to 10 UAH. In 2026 this is 3 328 UAH × 1.4 = 4 660 UAH; for 2025 it was 4 240 UAH. Each full or partial month of the contract in the reporting year is counted, so a one‑off payment under a new contract in November will be counted only for two months.
| Type of expense | Limit for 2026 | Note |
|---|---|---|
| Life insurance or NPF for yourself | 4 660 UAH/month, up to 55 920 UAH per year | Maximum refund up to 10 065.60 UAH |
| The same for a first‑degree family member | 2 330 UAH/month per person, up to 27 960 UAH per year | Maximum refund up to 5 032.80 UAH per person |
| All deduction types combined | Not more than annual salary | The salary is reduced by the tax social relief (TSR), if it was applied |
Overall cap linked to salary
The total deduction together with other expenses, for example education costs, cannot exceed the annual salary from which PIT was withheld (paragraph 166.4.2 of the TCU). Only 18% of the eligible amount is refunded; the military levy of 5% remains in the budget.
Documents for the claim
Contract and payment documents
You need a copy of the contract and receipts or bank statements showing the payer, the recipient, the amount and the date of payment in the reporting year. Copies are attached to the declaration, while the originals should be kept for the statute‑of‑limitations period.
Certificate from the insurer and income data
Insurers and funds usually issue a certificate of the total contributions for the year. Data on salary and withheld PIT can be obtained in the Electronic Cabinet via a request for amounts of paid income; the response comes within minutes. For a contract on a family member add a marriage or birth certificate.
How to submit the declaration in the Electronic Cabinet
Step‑by‑step instructions
The most convenient way is to submit the declaration online, since documents are then added as scanned copies. The procedure is as follows.
- Log in to the taxpayer’s Electronic Cabinet at cabinet.tax.gov.ua using Diia.Signature, id.gov.ua or a file key.
- Generate a request for amounts of paid income for the required year and verify the salary and PIT amounts.
- Create the tax declaration of property and income for the reporting year, marking the type as “reporting”.
- Add Appendix F3, state the amount of expenses under the contract within the limit and calculate the refund.
- Enter the details of your IBAN account for receipt of funds.
- Attach scanned copies of the contract and payment documents, sign the declaration and submit it, then check receipt No. 2.
Submission deadline and review
The declaration for the 2026 deduction is accepted until 31 December 2027. The tax authority checks the data and transfers the funds within 60 calendar days after receiving the declaration. If the right is not used in time, it is not carried forward to subsequent years (paragraph 166.4.3 of the TCU).
Examples of refund calculations
Contract for yourself and for your husband
Olena earns 25 000 UAH salary per month and has paid 3 000 UAH monthly since 2023 for a life insurance contract on herself. In 2026 she paid 36 000 UAH, which is below the 55 920 UAH limit, so she will be refunded 36 000 × 18% = 6 480 UAH. For the contract on her husband she paid 30 000 UAH, but only 2 330 × 12 = 27 960 UAH will be considered, which gives another 5 032.80 UAH, a total of 11 512.80 UAH.
New contract at the end of the year
Andrii signed a pension contract with an NPF on 10 November 2026 and immediately paid 50 000 UAH. The contract was in force for two partial months in 2026, so only 4 660 × 2 = 9 320 UAH will qualify for the deduction and the refund will be 1 677.60 UAH. If he had spread the same amount over contributions during 2027, he would have reclaimed 9 000 UAH.
Early termination and refusals of the deduction
Tax on the surrender value
If the policyholder terminates a long‑term life insurance contract prematurely, the insurer as a tax agent withholds 18% PIT from the surrender value (sub‑subparagraph “b” of subparagraph 170.8.2 of the TCU) and a 5% military levy. For example, after three years of paying 30 000 UAH per year a person reclaimed 16 200 UAH in refunds, but on surrender of a sum of 80 000 UAH the insurer will withhold 18 400 UAH in taxes. For NPFs a one‑off early payment is possible only in cases defined by law, and taxes are then calculated on the whole amount, whereas transferring to another fund does not cancel the deduction.
Common reasons for refusal
The tax authority most often refuses when the contract is not long‑term, the insurer is a non‑resident, or the payment was made by another person. Frequently a new contract is counted as 12 months instead of the actual months. If you have no salary - only income as an individual entrepreneur (FOP) or a pension - you are not entitled to the deduction.
How to appeal a decision
If you disagree with the audit conclusion, submit a complaint to the State Tax Service of Ukraine (STS) within 10 working days after receiving the decision; an error in your own calculations can be corrected with an amended declaration. If administrative appeal fails, the tax decision can be challenged in the administrative court.
Frequently asked questions
Can I get the deduction if I am an individual entrepreneur (FOP)?
There is no deduction for income from FOP on any tax system, because the deduction refunds only PIT from salaries. If the entrepreneur also works under an employment contract, they can claim the deduction against the salary from that contract.
What is the deadline for submitting the declaration?
The deduction for 2026 expenses must be claimed by 31 December 2027 inclusive. For 2025 you can still file until 31 December 2026 with a limit of 4 240 UAH per month for yourself.
How much can I get back?
For a contract on yourself the maximum is 10 065.60 UAH for 2026; for each family member an additional up to 5 032.80 UAH. The actual amount cannot exceed the PIT withheld from your salary for the year.