Who must declare foreign income
Tax residents of Ukraine must report in their annual tax declaration income received from sources outside the customs territory of Ukraine. “Income” means any receipts from activity abroad that are included in the total annual taxable income of a resident individual.
A declaration is the official document in which a taxpayer reports their income and the taxes due. A tax agent is a person or organisation that withholds and remits taxes on behalf of the taxpayer. Aggregate income is the total annual income from all sources that is subject to taxation.
Main tax rates on foreign income
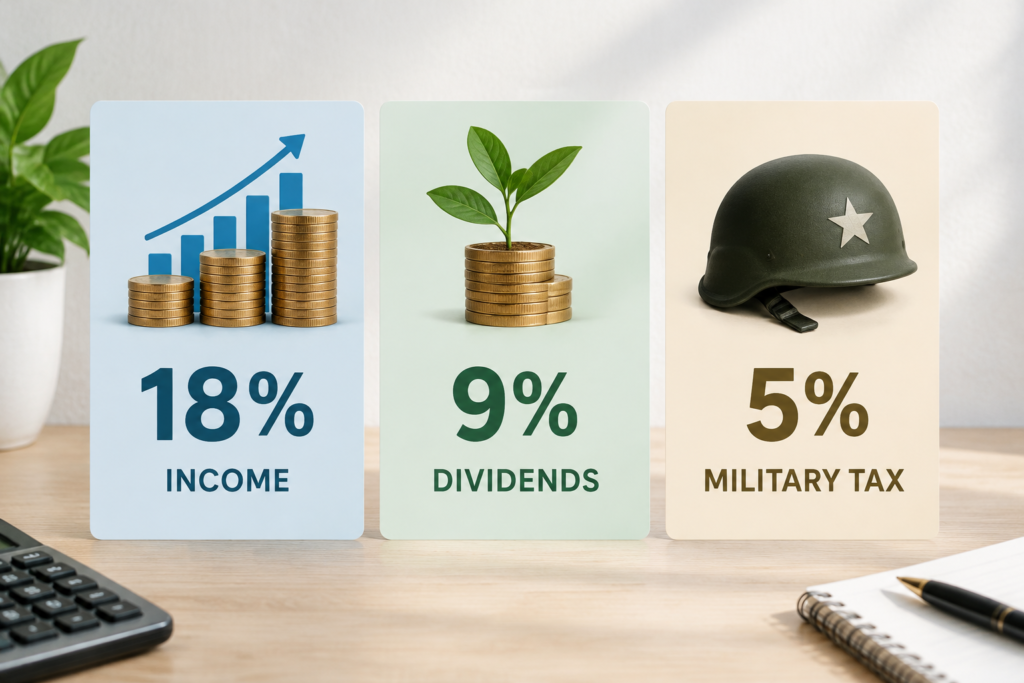
| Type of tax | Rate | Brief |
|---|---|---|
| Personal income tax | 18% | General rate for a resident’s foreign income |
| Dividends paid by non-residents | 9% | Special rate established by the Tax Code of Ukraine |
| Military levy | 5% | Applies to amounts of foreign income as a separate levy |
Thus, the overall tax on most foreign receipts is 18 percent. Dividends from non-residents are subject to a different rate of 9 percent. In addition, a military levy of 5 percent applies to foreign income.
The laws also provide exemptions. Some types of income are exempt from taxation under the provisions of the Tax Code of Ukraine or international agreements. If you have doubts about a particular type of income, you should check its status with the State Tax Service of Ukraine (STS).
Double taxation and taxpayer actions
If tax has already been paid abroad on foreign income, in cases provided for by international agreements the taxpayer may reduce their annual tax liability in Ukraine by the amount of taxes paid in another country. This is done when filing the annual tax declaration.
The specific steps to take when filing the declaration and the list of documents to confirm taxes paid abroad at source are not detailed. Therefore, the taxpayer should contact the State Tax Service of Ukraine (STS) to clarify procedures and requirements for supporting documents, or check the information on the STS’s official resources. Report foreign income in your annual declaration and indicate amounts according to the available evidence of receipts and taxes paid abroad.
It is important to reiterate: receiving income outside Ukraine does not in itself exempt you from the obligation to declare it. The ability to account for taxes paid abroad exists only within the limits set by the relevant international agreements.
For more on tax systems in other countries and the factors that affect tax formation in Europe, read the article — Taxes in European countries: how they are formed and what they depend on