This piece compares business taxation in four European countries: Germany, Poland, the Czech Republic and Spain. It sets out not only corporate tax rates but also the other components of the overall burden.
Main rates and components of the tax burden
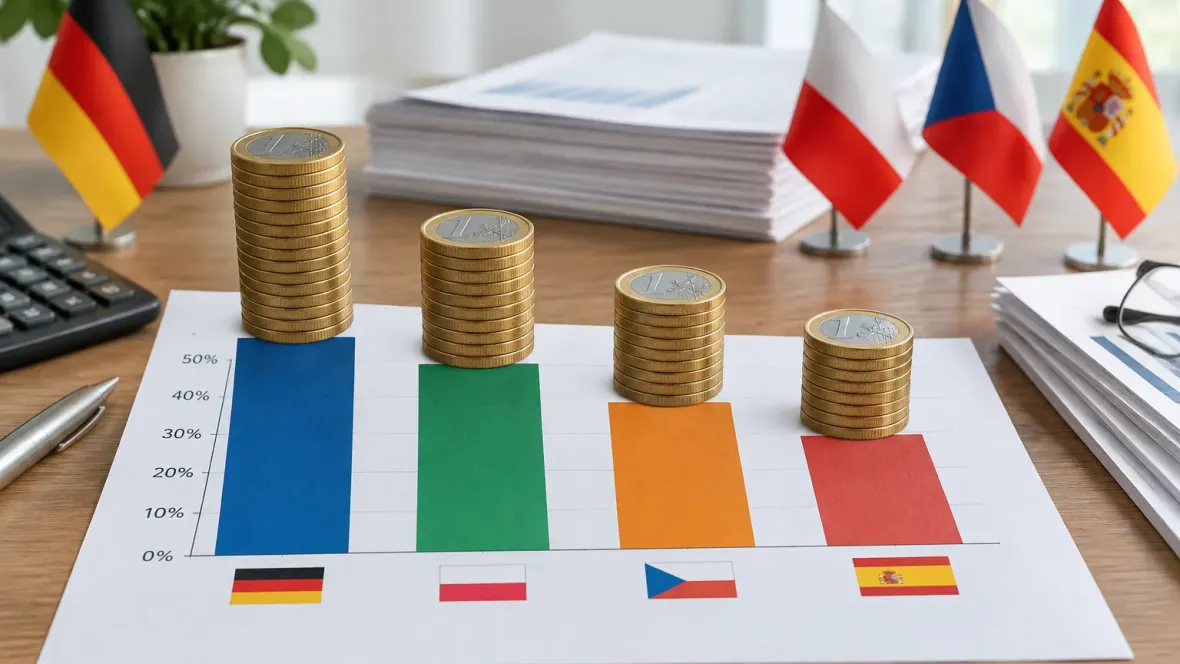
Federal corporate tax rates in the selected countries are: Germany — 15%, Poland — 19%, the Czech Republic — 21%, Spain — 25%. However, comparing countries by these rates alone is insufficient, because the burden also includes value-added tax (VAT), payroll taxes and contributions, taxation of dividends, local taxes, accounting costs and reporting requirements.
Different countries also offer favourable regimes for small businesses, start-ups and certain sectors. This article examines the full structure of the tax burden — from the cost of an employee and VAT to dividend taxation and available incentives.
Germany: 15% federal tax and local trade tax
In Germany the federal corporate tax rate is 15%, to which a solidarity surcharge of 5.5% of that tax is added, resulting in roughly 15.8% of taxable profit. But the overall burden also includes a local trade tax (Gewerbesteuer), which is set by municipalities.
The basic trade-tax rate is 3.5%, which is multiplied by a municipal multiplier, so there is no single nationwide combined corporate-tax rate in Germany.