
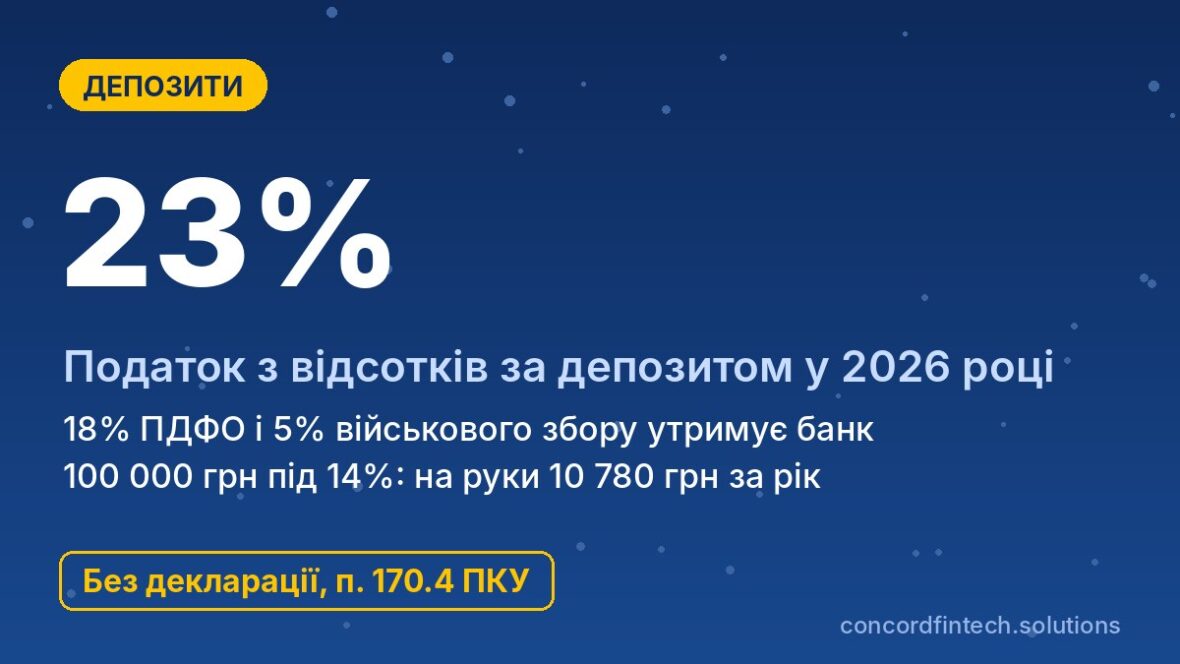
The deposit tax in 2026 is 23% of accrued interest: 18% personal income tax (PIT) and 5% military levy (ML). The bank withholds it at the moment interest is credited, so the depositor receives the net amount in their account and does not need to declare it. Put simply, from every 100 UAH of interest you receive 77 UAH net.
The same rules apply to foreign‑currency deposits, savings accounts, interest on card balances and deposit certificates. Below we explain how to calculate net income for any rate, how capitalization works, whether cashback is taxable and what to do if the bank makes a withholding error.
How deposit interest is taxed
Rate: 18% personal income tax and 5% military levy
Interest on deposits is passive income, and clause 167.1 of the Tax Code of Ukraine sets a personal income tax rate of 18% for such income. From 1 December 2024 the military levy on these incomes increased from 1.5% to 5%, and this rate applies throughout 2026. Together the total is 23% of the accrued interest.
The deposit amount, the term of the contract and the number of deposits do not affect the rate. There is no tax‑free minimum for interest, so tax is withheld even on a few hryvnias of income in a savings account.
The bank as the tax agent
Subparagraph 170.4.1 of the Code defines that interest on current or deposit (savings) accounts is finally taxed by the tax agent at the moment of accrual. The agent is the bank that credits the interest, so the tax is withheld on the same day the interest appears in the contract, not when you withdraw it. If interest is credited monthly, the tax is withheld monthly as well.
The withheld tax is remitted by the bank to the budget and reported in its tax return. The depositor does not need to pay anything themselves or notify the tax authority about opening the deposit.
Foreign‑currency deposits and exchange‑rate differences
Interest on deposits in dollars or euros is taxed at the same rates of 18% and 5%. The bank withholds the tax in the currency of the deposit, and to pay it to the budget converts the amount into hryvnia at the official rate of the National Bank of Ukraine (NBU) on the date the income is accrued. For example, from 150 USD of interest the depositor will receive 115.50 USD, and 34.50 USD will go to tax.
Only the interest is taxed, not the principal. Returning your own funds is not income, so an appreciation of the dollar during the deposit term does not create a separate tax obligation.
Real deposit yield after taxes
Formula: rate × 0.77
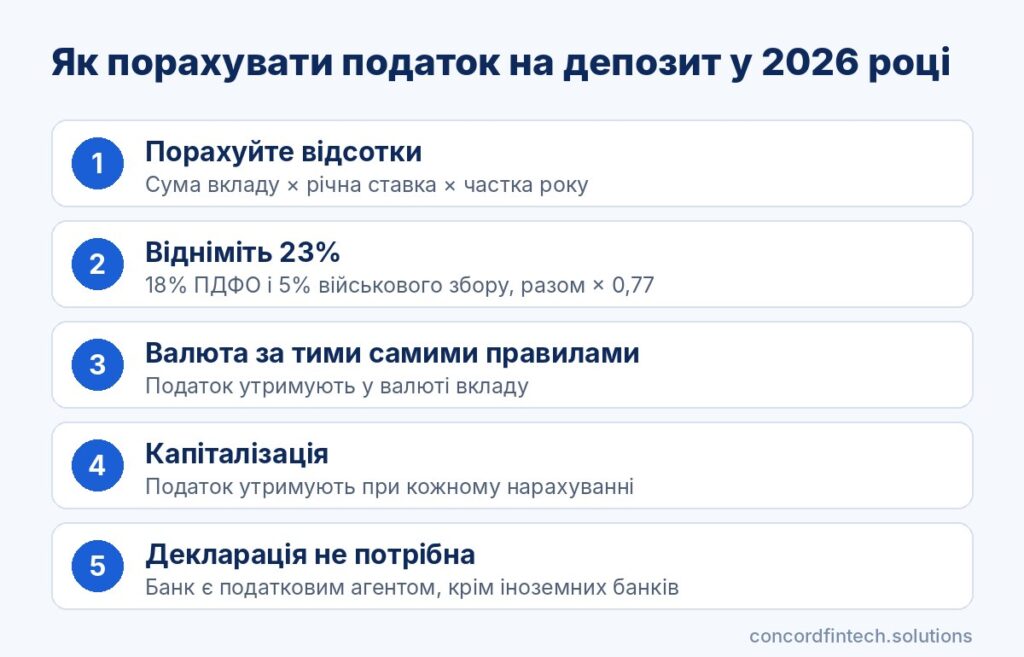
To find the net rate, multiply the nominal rate in the contract by 0.77. A deposit at 14% per annum yields 10.78% after tax; 12% becomes 9.24%; and a foreign‑currency deposit at 3% becomes 2.31%. This is the figure you should compare when choosing between banks or other ways of storing money.
The calculation takes a minute and does not require a bank calculator. You can calculate net income on a deposit in three steps:
- Multiply the deposit amount by the annual rate and by the fraction of the year, for example 6/12 for a six‑month deposit.
- Subtract 23% from the resulting interest, i.e. multiply it by 0.77.
- Compare the net income with inflation for the same period to assess real growth.
Example: 100 000 UAH at 14% per year
A depositor places 100 000 UAH for 12 months at 14% per annum with monthly interest payments. Over the year the bank will credit 14 000 UAH, from which it will withhold 2 520 UAH as personal income tax and 700 UAH as the military levy. The depositor will receive 10 780 UAH net, or approximately 898 UAH per month.
Monthly accruals amount to 1 166.67 UAH, from which the bank withholds 210 UAH as personal income tax and 58.33 UAH as the levy. Therefore in the mobile app you see a monthly incoming amount of about 898.33 UAH, not 1 166.67 UAH.
The impact of inflation on real income
According to the State Statistics Service, annual inflation in September 2026 was 10.0%. If prices continue to rise at that rate, a net return of 10.78% only slightly outpaces inflation, and the real increase in purchasing power is around 0.7% per year. In such a situation a deposit is more likely to protect money from devaluation than to significantly multiply it.
Foreign‑currency deposits with nominal yields of 2–3% before tax do not protect against hryvnia inflation, but their outcome also depends on the exchange rate. Therefore comparing a hryvnia and a foreign‑currency deposit by rate alone is incorrect — you must consider tax and expected exchange‑rate dynamics.
| Instrument (example) | Nominal rate | Tax | Net yield |
|---|---|---|---|
| Deposit 100 000 UAH for 12 months, monthly payments | 14% | 23% (3 220 UAH) | 10.78% (10 780 UAH) |
| Deposit 100 000 UAH for 12 months with capitalization | 14% | 23% | about 11.33% (11 329 UAH) |
| Deposit 5 000 USD for 12 months | 3% | 23% (34.50 USD) | 2.31% (115.50 USD) |
| Interest on card balance 50 000 UAH for a month | 10% | 23% (95.83 UAH) | 7.7% (320.83 UAH) |
| Ukrainian government bonds | as per issue terms | 0% | equals the nominal rate |
The rates in the table are examples for calculation, not offers from specific banks. Check actual terms in the contract on the date you open a deposit.
Capitalization, certificates and tax‑free income
Capitalization of interest
With capitalization, interest is added to the deposit sum each month and the next month interest is calculated on the larger amount. Tax is withheld at each accrual, so only the net portion of interest is added to the principal. For 100 000 UAH at 14% per year with monthly capitalization the net income will be about 11 329 UAH instead of 10 780 UAH with standard payments.
The difference arises due to compound interest, not a tax benefit. The longer the term and the higher the rate, the more noticeable the effect of capitalization.
Deposit and savings certificates
Income on a named savings (deposit) certificate of a bank is taxed the same way as interest on a regular deposit. The bank withholds 18% personal income tax and 5% military levy when income is accrued or paid, and the certificate holder receives the net amount. There is no separate requirement to declare such income.
Income from which the bank does not withhold tax
Income from domestic government bonds, i.e. Ukrainian government bonds (OVDP), is exempt from tax — this is the main tax difference from deposits. It is important for depositors to understand which inflows to an account are taxed and which are not. Briefly the split looks like this:
- taxed at 23%: interest on deposits, savings accounts, card balances and deposit certificates;
- taxed at 23% according to the position of the State Tax Service (DPS): bank cashback for purchases;
- not taxed: return of the deposit principal, income from Ukrainian government bonds (OVDP), change in the hryvnia value of a foreign‑currency deposit due to exchange‑rate movements.
Deposit guarantees by the Fund
Tax does not depend on whether a deposit is guaranteed, but this matters when choosing a bank. During martial law and for three months after its end the Deposit Guarantee Fund reimburses deposits of individuals in full. After that period the guaranteed amount will be 600 000 UAH per depositor in one bank.
Interest on card balances and cashback
Tax on interest on balances
Many banks credit interest on customers’ own funds on a card or current account. Subparagraph 170.4.1 explicitly covers interest on current accounts, so such income is taxed at the same 23%. For example, if 416.67 UAH is accrued on a 50 000 UAH balance for a month at 10% per annum, the card will receive 320.83 UAH.
Is cashback taxable?
The Tax Code contains no separate exemption for bank cashback. The State Tax Service (DPS) in its explanations considers the partial refund on a purchase to be income of an individual, which is taxable at 18% personal income tax and 5% military levy, with the bank acting as the tax agent. Therefore cashback you see in the app should be credited by the bank with tax withheld, and you do not need to declare it yourself.
The state programme “National Cashback” is separate, because by law its payments were exempt from personal income tax and the military levy for 2024–2025. Whether this exemption was extended to payments in 2026 should be checked in current explanations by the State Tax Service (DPS).
Savings accounts and “piggy‑bank” features
Savings accounts, “piggy‑banks” and similar features in mobile apps are legally current or deposit accounts. Interest on them is taxed at 23% and withheld by the bank when credited, even if paid daily. So always multiply the yield shown in the app by 0.77.
Declaration and checking withheld tax
When no declaration is needed
Interest from a Ukrainian bank is finally taxed at the moment of accrual, so you do not need to file a declaration of property and income for it. This applies to deposits in hryvnia and foreign currency, interest on balances and certificates. A declaration is only required when there are other incomes that must be declared.
It is different for interest from a foreign bank, because there is no Ukrainian tax agent there. Such income must be declared and you must pay 18% personal income tax and 5% military levy yourself; we recommend filing the 2026 declaration by 30 April 2027.
Why interest may not appear in the register
The bank reports interest in its tax return as a single aggregated sum for all customers, without listing each individual. Therefore interest from deposits is usually absent from the statements in the State Register of Individuals’ Income that you can order in the Electronic Cabinet. This is not an error and not a sign that the tax was not paid.
A bank statement and correcting mistakes
Only the bank can confirm the amount of accrued interest and the tax withheld. You can order such a certificate or statement in a branch or in the app, and it will be needed if you must confirm the source of funds or verify the calculation. If you notice that the bank withheld more than 23% or withheld tax on an amount that is not interest, contact the bank with a written request, because the tax agent is responsible for correcting its calculations.
The most common confusion arises when a deposit is terminated early and the bank recalculates interest at a lower contractual rate. In that case check whether the tax amount has been adjusted along with the interest; if you disagree with the bank’s response you can contact the State Tax Service (DPS).
Frequently asked questions
Does the bank withhold tax on a foreign‑currency deposit?
Yes, the bank withholds 18% personal income tax (PIT) and 5% military levy (ML) on interest from a foreign‑currency deposit in the currency of the deposit. For budget payments the amount is converted into hryvnia at the NBU exchange rate on the accrual date, and exchange‑rate gains on the principal are not taxed.
Do I need to declare income from a deposit?
No, if the deposit is opened in a Ukrainian bank, because the bank finally taxes the interest as the tax agent. You only need to declare interest from foreign banks from which no Ukrainian tax was withheld.
Which is better: a deposit or government bonds?
Income from Ukrainian government bonds (OVDP) is not taxed, whereas interest on a deposit is taxed at 23%. So compare the net yield of a deposit — i.e. the rate multiplied by 0.77 — with the bond yield, and also consider liquidity and maturities of each instrument.
Is cashback taxable?
According to the position of the State Tax Service (DPS), bank cashback is income and is taxed at 18% personal income tax and 5% military levy, withheld by the bank. Payments under the state “National Cashback” programme had a separate tax exemption, so they should not be confused with ordinary bank cashback.